


How Investors May Respond To Zscaler (ZS) AI Push Meets Slower Growth
- Zscaler reported full-year 2026 sales of US$3,352.52 million, with a net loss of US$63.18 million. The company also issued fiscal 2027 guidance implying mid-teens revenue and ARR growth, and rolled out its AI-first Agentic SOC platform, now available globally.
- The combination of strong AI-focused product launches such as Agentic SOC and management’s outlook for slower growth highlights the execution demands on Zscaler’s sales motion, product adoption and cost discipline.
- We will now look at how Zscaler’s slower fiscal 2027 growth guidance, alongside the Agentic SOC launch, shapes its investment narrative.
Scan how Zscaler’s AI-first push compares with other security and infrastructure plays by hunting through 60 AI infrastructure stocks shaping the next leg of AI-driven defenses and data protection.
Zscaler Investment Narrative Recap
Zscaler asks you to back a long runway for zero trust security, AI driven defenses and higher value per customer, while accepting that profitability is still a work in progress. The fiscal 2027 guide for high teens revenue and ARR growth puts a spotlight on whether the sales transition and broader platform story can keep large deals flowing.
The key near term catalyst is execution on AI centric products like Agentic SOC without letting costs run away while the firm is still reporting net losses. The biggest risk is that large cloud providers and established security vendors tighten integration faster than Zscaler can prove its newer offerings are must have rather than nice to have.
The launch of Zscaler Agentic SOC is the clearest recent swing at that catalyst. Management is leaning on its zero trust network position, 750 billion daily transactions and a broad telemetry set to feed AI agents that handle triage, investigation and response while tying directly into Zscaler controls and third party tools.
For you, the question is whether this product can translate into meaningful ARR contribution against the backdrop of guided growth deceleration and ongoing net losses. Execution risk sits in customer adoption speed, integration quality with existing SOC stacks and the cost of maintaining advanced AI partnerships with Anthropic, OpenAI and others while competition crowds into AI security.
Zscaler Forecast Framing And Valuation Tension
Zscaler's narrative projects US$5.1b revenue and US$132.0 million earnings by 2029. This forecast is based on 17.1% yearly revenue growth and a swing in earnings of about US$209 million from a loss of US$77.4 million today.
Uncover why Zscaler's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
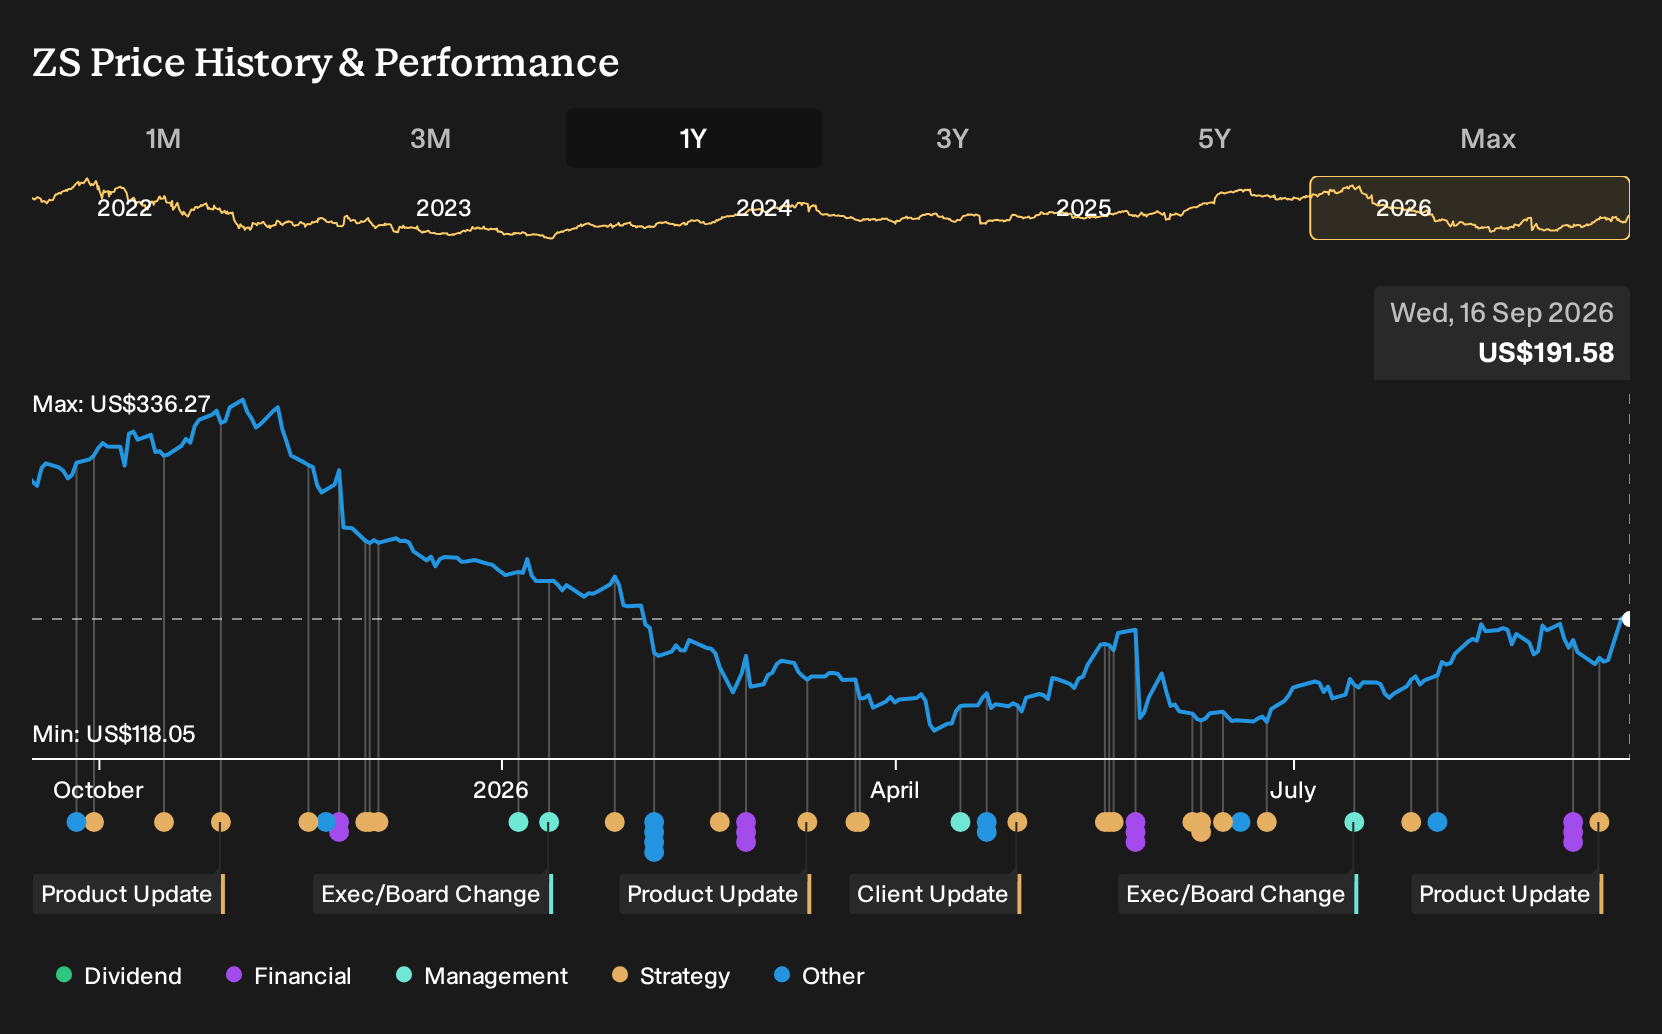
Exploring Other Perspectives
The sharpest contrast comes from bearish analysts who worry less about Zscaler’s AI-first Agentic SOC and more about thin profitability. Before this news, the lowest group was only penciling in about US$5.2b revenue and US$50.0 million earnings by 2029. That is far below consensus and shows how widely views can differ.
Explore 4 other Zscaler fair value estimates, including one that suggests it could be worth just $196.95.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zscaler research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Zscaler. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zscaler's overall financial health at a glance.
Looking for more investment ideas beyond Zscaler?
If Zscaler has sharpened your focus on where growth, quality and risk management intersect, it can help to widen the lens and see how other businesses stack up on those same dimensions.
- For investors who want a shot at value with quality fundamentals, review a focused group of 33 high quality undervalued stocks that score well on both cash flows and balance sheet strength.
- If capital preservation comes first for you, filter the market down to 11 resilient stocks with low risk scores that may offer a smoother ride than more volatile peers.
- To broaden your research with less widely followed opportunities, scan a curated pool of 16 high quality undiscovered gems that pair healthy fundamentals with lower current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com