


Is Subscription Growth Altering The Investment Case For Agilysys (AGYS)?
- Agilysys recently featured at the Piper Sandler 5th Annual Growth Frontiers Conference in Nashville, where CFO Dave Wood discussed the hospitality software provider’s operations and met with investors in one-on-one and group sessions.
- The company reported 26% subscription revenue growth in the first quarter of fiscal 2027 and a 90% increase in fiscal 2026 operating income, reflecting the impact of its shift toward a higher-margin recurring model and unified platform.
- We will now assess how Agilysys' subscription momentum could influence the investment narrative around its hospitality software business model.
Agilysys Investment Narrative Recap
To own Agilysys, you have to believe the hospitality software shift to subscriptions keeps building and that its unified platform continues to support high retention and pricing power. The recent Piper Sandler appearance and Q1 FY27 subscription growth of 26% reinforce that recurring model, so the core long term thesis stays intact.
In the near term, the key swing factor is whether operating leverage similar to the 90% fiscal 2026 operating income increase can persist as sales and product spend stay elevated. The largest risk remains concentrated exposure to hotels, resorts, casinos, and food service if travel trends soften and customers slow upgrades or new deployments.
The most relevant data point for this conference backdrop is Agilysys’ recent options activity, with the October 16, 2026 US$45 put showing very high implied volatility. That indicates the options market is bracing for a sizable move in the equity around upcoming information, even if the direction is unclear.
For shareholders, that options signal sits on top of existing catalysts tied to SaaS mix, ARR expansion, and AI features in the product suite. It also amplifies execution risk if any stumble in subscription growth, margins, or hospitality demand emerges, since a tightly wound options setup can magnify short term price swings around new data.
Agilysys' current consensus narrative points to revenues of US$523.9 million and earnings of US$91.9 million by 2029, based on analysts assuming 16.6% yearly top line growth and an earnings move of about 2.1x from today’s US$42.9 million level.
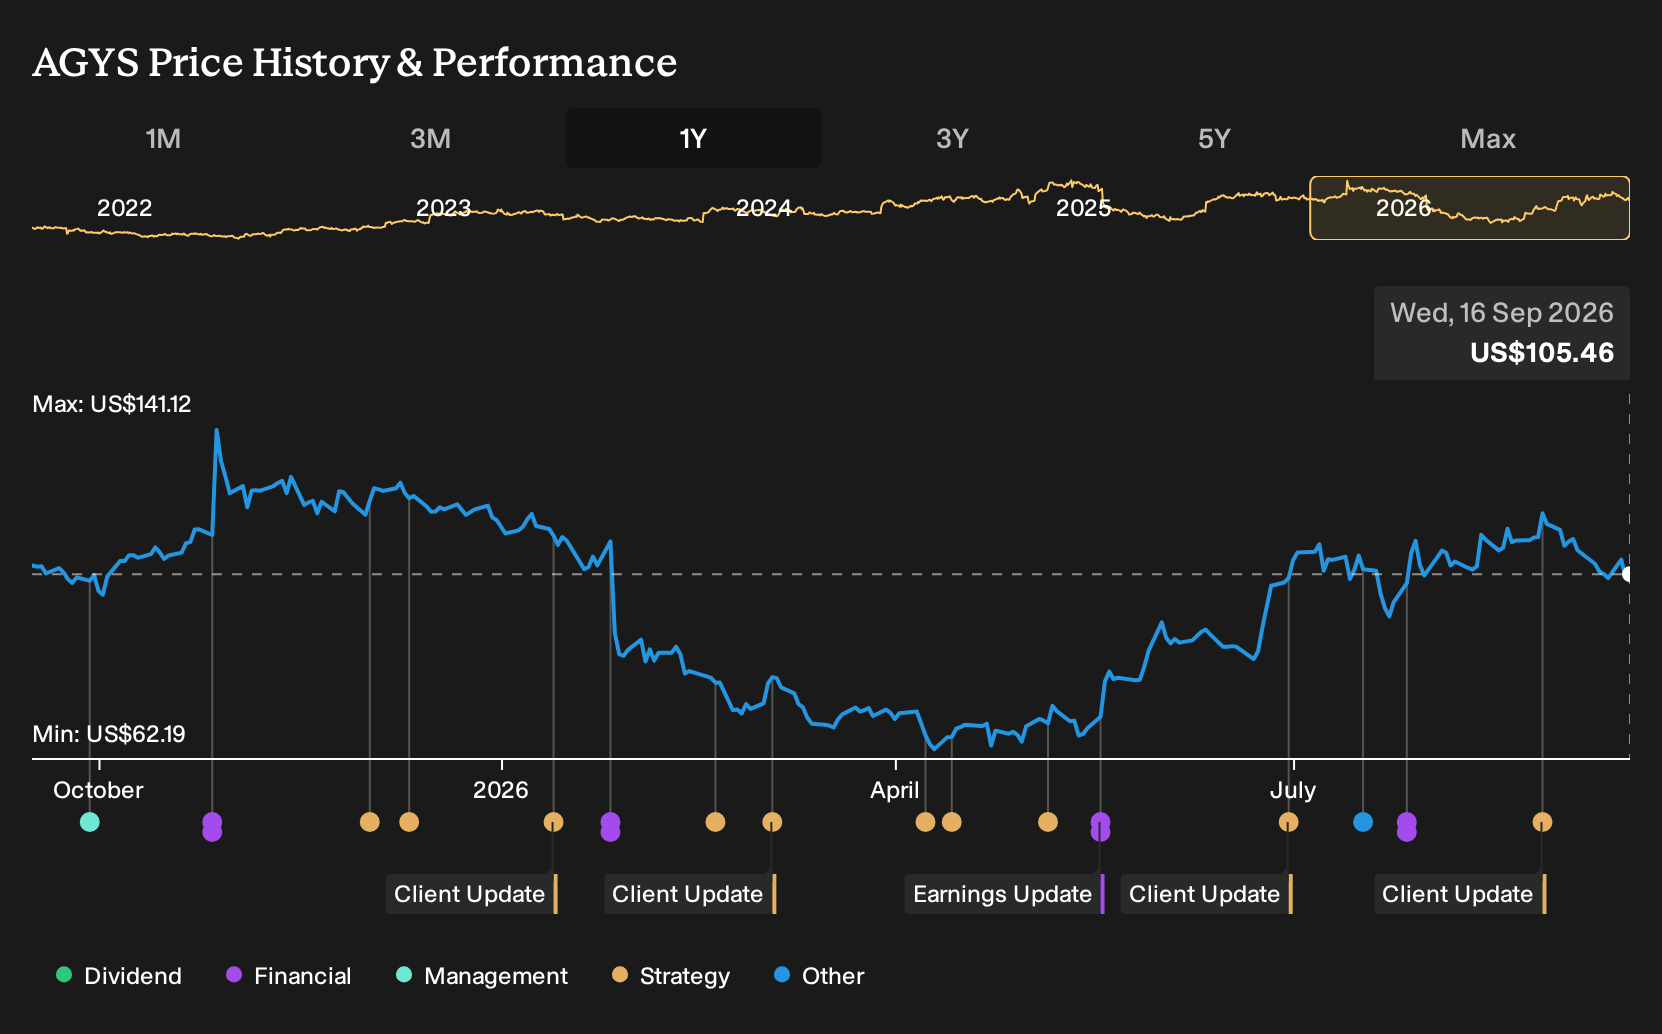
Uncover why Agilysys' fair value indicates a 27% potential upside to its current price, a gap that could narrow quickly if investor sentiment shifts.
Exploring Other Perspectives
One tension point in the alternate Agilysys story is cybersecurity cost pressure. The most cautious analysts already penciled in 15.5% annual revenue growth to about US$509.5 million and earnings of US$98.8 million by 2029, yet still argued margins could be squeezed. That was all before this week’s conference, so those views might shift.
Explore 3 other Agilysys fair value estimates, including one that suggests as much as 81% downside from the current price!
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Agilysys research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agilysys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agilysys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Agilysys?
Once you have a view on Agilysys, it often helps to benchmark that thesis against other stocks with clear financial profiles and different risk levels.
- For investors who want potential upside without stretching quality too far, scan through 16 high quality undiscovered gems that combine solid fundamentals with less crowded ownership.
- If capital preservation is a priority and you prefer steadier business profiles, filter for 11 resilient stocks with low risk scores to see companies with more resilient risk scores.
- For readers who care most about balance sheet strength and fundamental durability, shortlist candidates using a list of solid balance sheet and fundamentals (22 results) that can help anchor a long term portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com