


Does CE Mark Approval Change The Bull Case For Intuitive Surgical Stock (ISRG)?
- Intuitive Surgical received CE mark approval for the da Vinci SP system in Europe for transvaginal gynecologic procedures, widening its labeled use in single port, natural orifice surgery across multiple disciplines.
- This new indication deepens Intuitive Surgical's reach in women's health and could support higher utilization of existing da Vinci SP installations through more procedure types per system.
- We will look at how Intuitive Surgical's investment narrative is shaped by this new European transvaginal da Vinci SP approval.
Intuitive Surgical Investment Narrative Recap
To own Intuitive Surgical, you need to believe robotic assisted, minimally invasive procedures keep gaining share across more specialties and geographies, and that the company can keep building recurring instrument and service usage on top of a large installed base. The new European transvaginal approval supports that story, but by itself is unlikely to shift the near term picture dramatically.
The key short term catalyst still looks like overall da Vinci procedure volumes and hospital capital appetite. These remain sensitive to budget constraints in markets such as Europe, Japan, and China. The main operational risk is slower system placements or upgrade cycles if governments and hospitals remain tight on spending or push harder on cost effectiveness and reimbursement.
The recent large meta analysis on da Vinci outcomes is highly relevant to this new indication. It adds clinical backing for robotic assisted surgery across 13 common benign conditions, which matters when payers and hospital committees scrutinize cost versus benefit for expanding access to procedures like transvaginal gynecologic surgery.
If that evidence continues to support perioperative outcomes, it can help Intuitive Surgical argue for broader adoption and protect procedure volumes against cheaper laparoscopic or open approaches. The flip side for investors is execution risk. Health systems facing budget pressure may still prioritize lower upfront capital or extended use instruments from competitors, even with supportive data in hand.
What The New Approval Means For Intuitive Surgical's Numbers
The fresh European green light for transvaginal gynecologic use does not overhaul Intuitive Surgical's analyst playbook, but it slots neatly into an existing growth script. Forecasts already build in a sizable expansion, with analysts assuming revenue increases at 11.8% a year over the next 3 years as more procedures migrate to robotic platforms and installed systems see heavier use.
On profitability, the story in the models is about gradual improvement rather than a step change from any single regulatory win. Consensus views point to profit margins moving from 28.4% today to 30.3% in 3 years. This implies analysts see operating leverage as volumes scale and higher value procedures such as transvaginal gynecologic cases add to procedure mix and instrument pull through.
For earnings, the sell side is anchoring on a long dated target set around 2029. The group expects Intuitive Surgical to generate US$4.7b of earnings by that point, up from US$3.1b today, with the more cautious forecasts still sitting at US$4.2b. That is an earnings increase of roughly US$1.6b across the period, a step that would likely require both stronger utilization of the da Vinci fleet and continued pricing and mix support in instruments and services.
Those profit projections feed directly into how analysts frame valuation. To make their numbers hang together, they assume the stock trades on a P/E of 44.4x those 2029 earnings, compared with about 41.9x today and a US Medical Equipment industry level around 27.0x. In practical terms this means investors are being asked to pay a premium multiple for a business that consensus expects to pair mid teens style revenue expansion with margin uplift, supported in part by regulatory moves such as this new European da Vinci SP transvaginal indication.
Differences inside the analyst community show up both in earnings and in price targets. On the price side, the current set of models points to a consensus target of US$478.01 per share, compared with a present share price of US$371.88. The most optimistic targets reach US$685.00 while the most cautious come in at US$324.00, suggesting a wide range of views on how far procedure growth, geographic expansion, and add on capabilities such as natural orifice surgery can extend Intuitive Surgical's economic moat.
The scenario that underpins that central price target depends on sizeable top line and bottom line steps by 2029. Analysts who back that view are working with revenue of about US$15.4b and earnings of US$4.7b in that year, discounted using a rate around 7.5%. The new European approval for transvaginal da Vinci SP use is one piece of the puzzle that can support those volume and earnings ambitions if it leads to broader adoption in gynecology and stronger utilization of the installed SP base.
Intuitive Surgical's narrative projects US$15.4b revenue and US$4.7b earnings by 2029. This requires 11.8% yearly revenue growth and an earnings increase of about US$1.6b from US$3.1b today.
Uncover why Intuitive Surgical's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
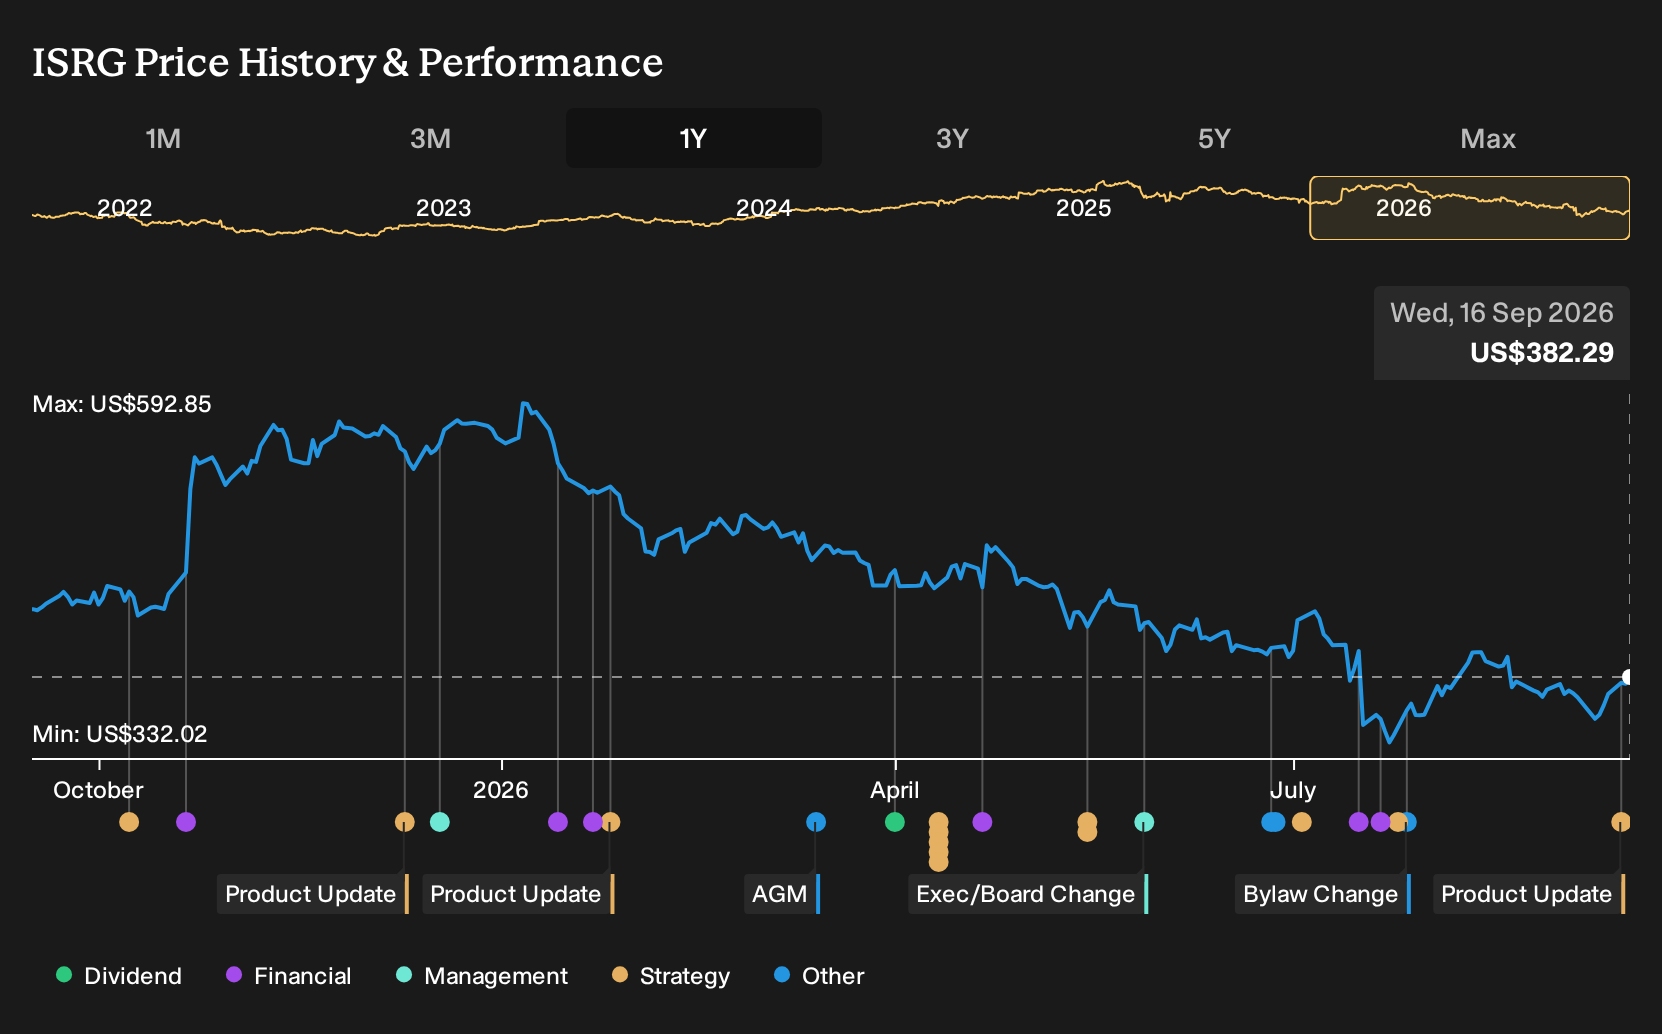
Exploring Other Perspectives
You can read this CE mark for transvaginal SP access as a test of a much more optimistic story. The most bullish analysts were already modeling revenue of US$17.2b and earnings of US$4.9b by 2029. Those forecasts came before this approval, so your view on Intuitive Surgical might shift meaningfully as models catch up.
Explore 11 other Intuitive Surgical fair value estimates, including one that suggests as much as 65% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely result from following the herd, so trust your own analysis.
- A great starting point for your Intuitive Surgical research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Intuitive Surgical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Intuitive Surgical's overall financial position at a glance.
Looking For More Ideas Beyond Intuitive Surgical?
If you like the long term themes behind Intuitive Surgical but want a broader watchlist, the Simply Wall St Screener can surface other stocks that fit the kind of risk and quality profile you care about most.
- If capital protection comes first for you, start with a basket of companies screened for resilience through a 11 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors hunting for quality at a fair price, focus on businesses flagged as potential mispricings through our curated 33 high quality undervalued stocks that might fit a value-first mindset.
- If you prefer strong financial footing as a baseline, filter for companies with healthier balance sheets using a targeted list of solid balance sheet and fundamentals (22 results) that can help you build a sturdier core portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com