


First Financial Bankshares (FFIN), What Is Behind The Latest Attention?
First Financial Bankshares (FFIN) shares most recently closed at US$33.32, which gives the regional lender an equity value of about US$4.79b and sets the starting point for assessing current market expectations.
Over the past year, First Financial Bankshares has seen its share price return move between short bursts of strength and periods of softness, with a 1-day share price decline of 0.92% and a 30-day share price return down 4.42%. However, a 10.99% year-to-date share price gain and a 3-year total shareholder return of 37.56% suggest that longer term momentum has been stronger than the recent pullback implies.
Scan beyond First Financial Bankshares and compare its recent pullback and longer term returns with a hand picked group of 11 resilient stocks with low risk scores.
Bulls see First Financial Bankshares as a quality regional lender catching its breath after a strong multi year run, while bears view the recent softness as fatigue. Which side does the current valuation support?
Price-to-Earnings of 17.6x: Is it justified?
On simple headline numbers, First Financial Bankshares trades on a P/E of 17.6x while the wider US Banks group sits nearer 11.9x, so the market is paying a clear premium for each dollar of earnings at the recent $33.32 share price.
The P/E ratio compares what investors are willing to pay today with the business's current earnings. This matters a lot for a bank where profitability depends on spreads, fee income and credit quality. A higher multiple like 17.6x often reflects investors assigning value to factors such as earnings resilience, balance sheet strength or management quality rather than just headline growth.
Context puts that premium in an interesting light. First Financial Bankshares earns a 13.5% Return on Equity, has high quality earnings, and has seen profit growth of 9.5% over the past year and 2.2% per year over five years, supported by annual revenue of $637.203m and net income of $269.012m. Yet this 17.6x P/E looks expensive relative to the estimated fair P/E of 12.7x, which is a level the market could shift toward if investors reassess how much they want to pay for those earnings.
Explore the SWS fair ratio for First Financial Bankshares.
Result: Price-to-Earnings of 17.6x (OVERVALUED)
Still, if credit quality or loan demand weakens across First Financial Bankshares' Texas markets, that premium P/E could quickly look less comfortable.
Find out about the key risks to this First Financial Bankshares narrative.
Another view on First Financial Bankshares' value
The 17.6x P/E suggests First Financial Bankshares may be expensive on an earnings basis. However, the SWS DCF model points in a different direction. At $33.32, the share price is about 27.9% below an estimated future cash flow value of roughly $46.20. Which yardstick deserves more weight for you?
Look into how the SWS DCF model arrives at its fair value.
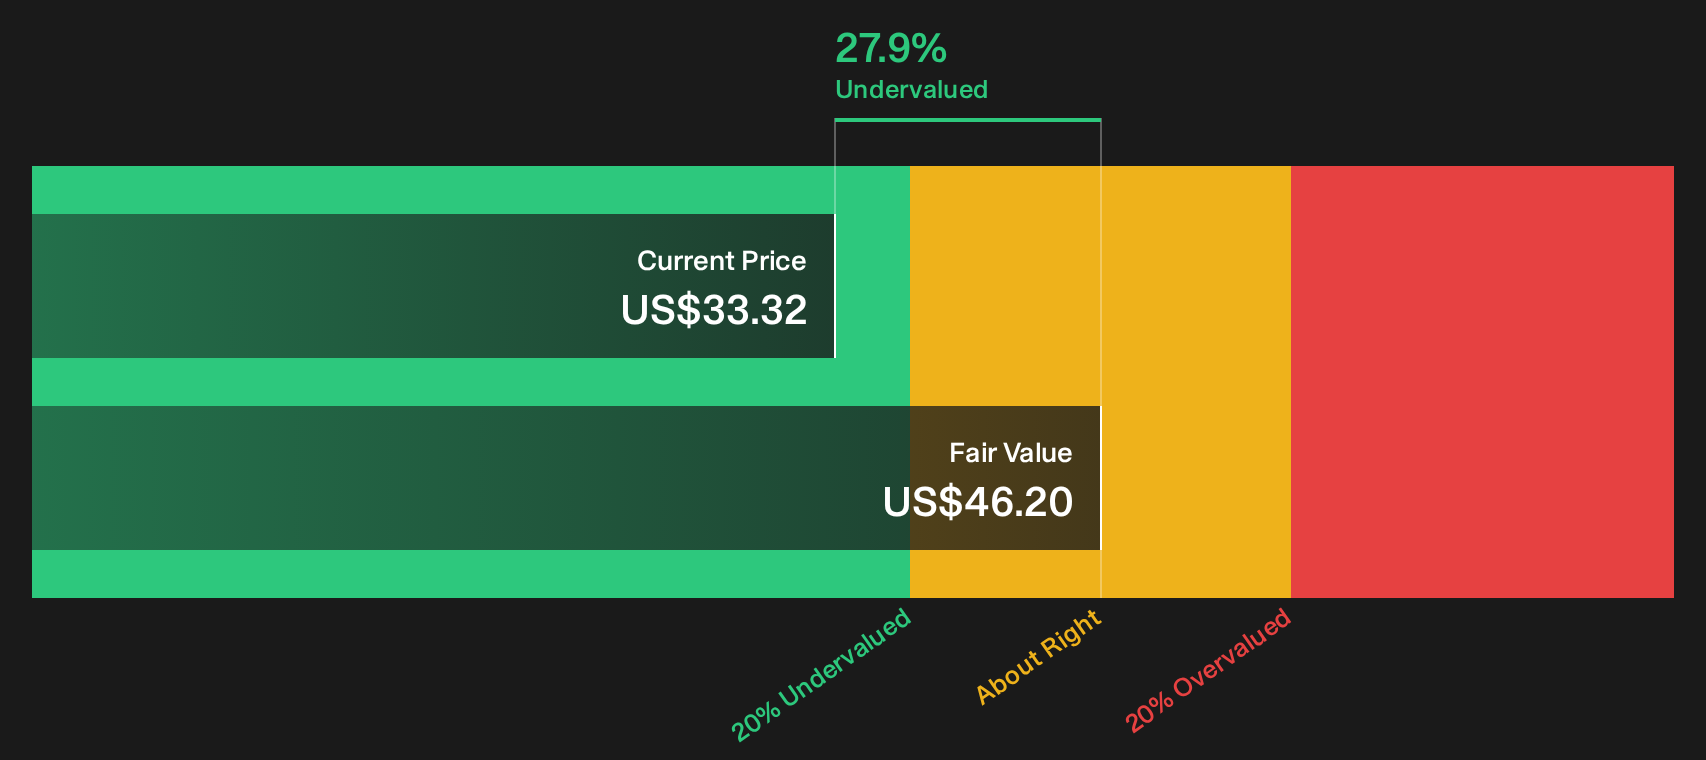
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Financial Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on First Financial Bankshares so far. If you want your view to be grounded in the full picture of both caution and upside, go straight to the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond First Financial Bankshares?
If you only stop at First Financial Bankshares, you risk missing other opportunities that might line up even better with your goals and risk tolerance.
- Target potential mispriced opportunities by scanning a curated set of 33 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Strengthen the resilience of your holdings by reviewing a list of solid balance sheet and fundamentals (22 results) that can help anchor your portfolio in tougher conditions.
- Hunt for underfollowed opportunities before they hit the mainstream by checking a focused group of 16 high quality undiscovered gems that already show solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com