


Ross Stores (ROST) Stock Looks Fully Valued At Current Earnings Levels
Ross Stores has delivered a powerful long term share price run, which now puts a spotlight on whether the current valuation is adequately supported by its earnings base. With the stock not far from recent highs, the question for investors is how much of that earnings story is already reflected in the US$224.80 price tag.
- Over the past 5 years, Ross Stores has returned 107.9%, which puts real weight on the question of whether its earnings justify that kind of compounding share price performance.
- The retailer’s off price model and focus on cost control can support relatively resilient profitability, which directly feeds into how investors assess the earnings multiple they are paying today.
- The analysts covering Ross Stores have run their own numbers. See what analysts think Ross Stores's shares could be worth.
The stock's next move may depend on whether Ross Stores' current share price is well aligned with what its earnings can reasonably support.
If you are weighing Ross Stores against other opportunities where earnings support is a key filter, a focused screener built around 33 high quality undervalued stocks can be a useful next step in your research.
Is Ross Stores Getting Expensive on Earnings?
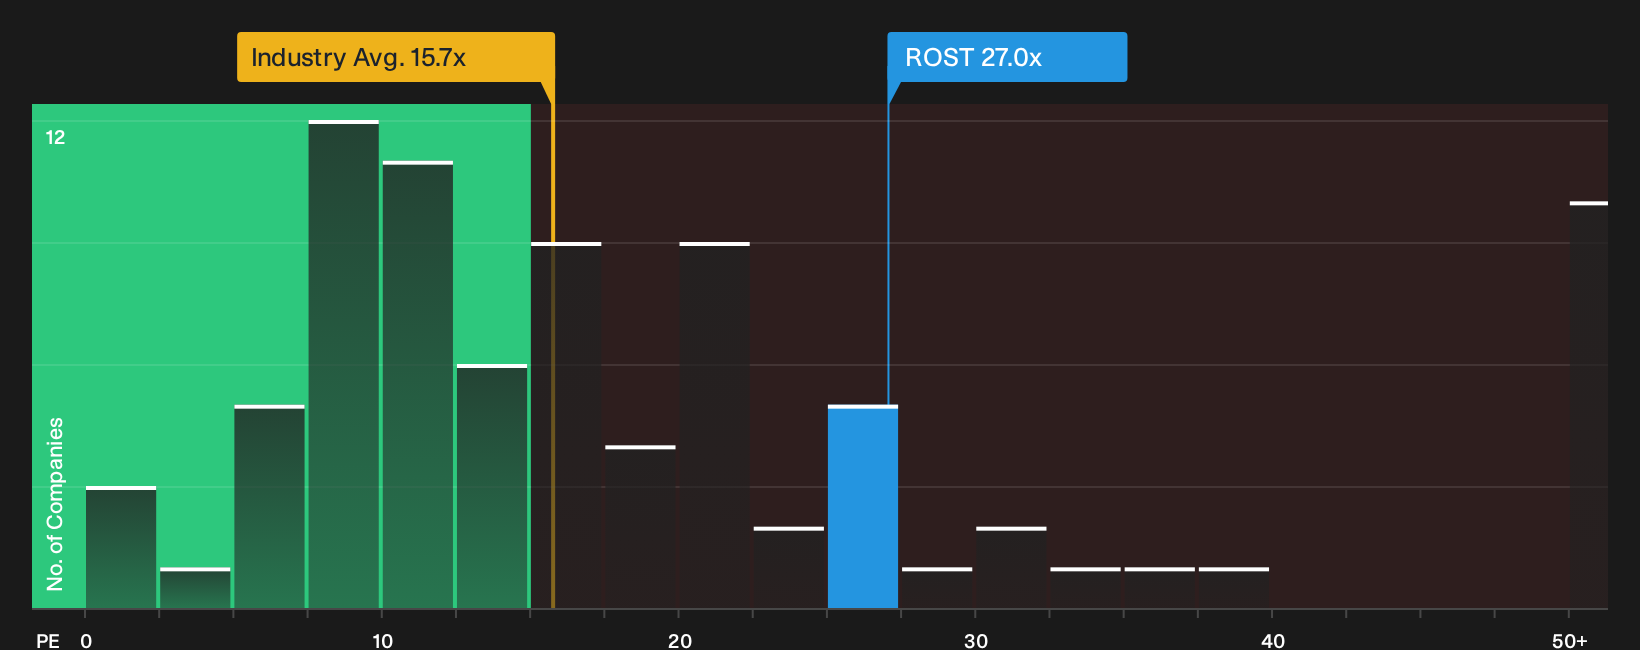
The P/E ratio fits Ross Stores well because earnings remain the clearest anchor for how investors frame the off price model. At roughly 27.0x, the stock trades at a clear premium to the Specialty Retail industry average of about 15.7x and a peer group closer to 15.0x. Buyers today are therefore paying a higher price for each dollar of reported profit than is typical for the sector.
The valuation framework that blends Ross Stores' growth profile, profitability, size and risk points to a lower P/E as a more balanced reference. This leaves the current multiple screening as overvalued on this lens. For anyone considering an entry, the real question is whether the off price model, margin structure and cash generation justify paying that richer multiple relative to other retailers with lower headline P/E ratios. Explore the numbers behind Ross Stores's P/E valuation.
The Ross Stores Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ross Stores pick up where the P/E puzzle leaves off and describe which growth, margin and earnings paths would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today on the Community page. Each scenario ties its figures to a clear view on how Ross Stores' future profitability, top line and risk profile could change, giving you something concrete to revisit as fresh results are released.
Ross Stores splits opinion, with some investors seeing meaningful upside while others think the share price already runs well ahead of the fundamentals.
Bull case: 17% undervalued
"Investments in supply chain infrastructure and operational initiatives (e.g., new distribution center, store refreshes, rollout of self-checkout) are establishing a foundation for greater operating leverage and cost discipline..."
Discover why this Narrative puts Ross Stores at 17% undervalued.
Bear case: 201% overvalued
"The reason not to overpay for it is that Ross is the structurally smaller player in a business where buying scale is the moat itself..."
Explore why this Narrative puts Ross Stores at 201% overvalued.
Ross Stores valuation still leaves one leadership question hanging
Balance sheets and multiples are only half the story, because the people steering Ross Stores and how they are rewarded can tilt long term outcomes in ways the numbers here do not cover. See who runs Ross Stores and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com