


Dollarama (TSX:DOL) Stock Wrestles With Premium Valuation After Strong Q2
Dollarama’s share price came into this earnings print looking stretched, with a P/E of 34.5x and a stock that has drifted about 7% lower over the past three months as investors cooled on premium valuations. Then Q2 landed with a simple message that cuts through the mood swings. Revenue reached about CA$2.0b and earnings per share were CA$1.29, and the profit engine that justifies that rich multiple stayed firmly intact.
The sentiment gap is clear. A tired chart met a still powerful earnings machine, and traders now have to decide which story to believe.
Love Dollarama’s earnings machine but uneasy about paying a P/E of 34.5x for it? Check out the 1 resilient stocks with low risk scores to see how this retailer stacks up against other resilient compounders with more modest multiples.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): CA$2,026.6m vs. CA$1,723.8m (up about 17.6%)
- Net Income (Q2 2027 vs. Q2 2026): CA$349.3m vs. CA$321.5m (up about 8.6%)
- Basic EPS (Q2 2027 vs. Q2 2026): CA$1.29 vs. CA$1.16 (up about 11.3%)
- Same Store Sales Growth (Q2 2027 vs. Q2 2026): Not disclosed vs. 6.0% (prior year benchmark only; current quarter guided via updated full year outlook)
Prefer visual charts instead of another wall of earnings commentary and raw figures? View a full picture of Dollarama’s valuation setup in an easy dashboard format with the company report for Dollarama.
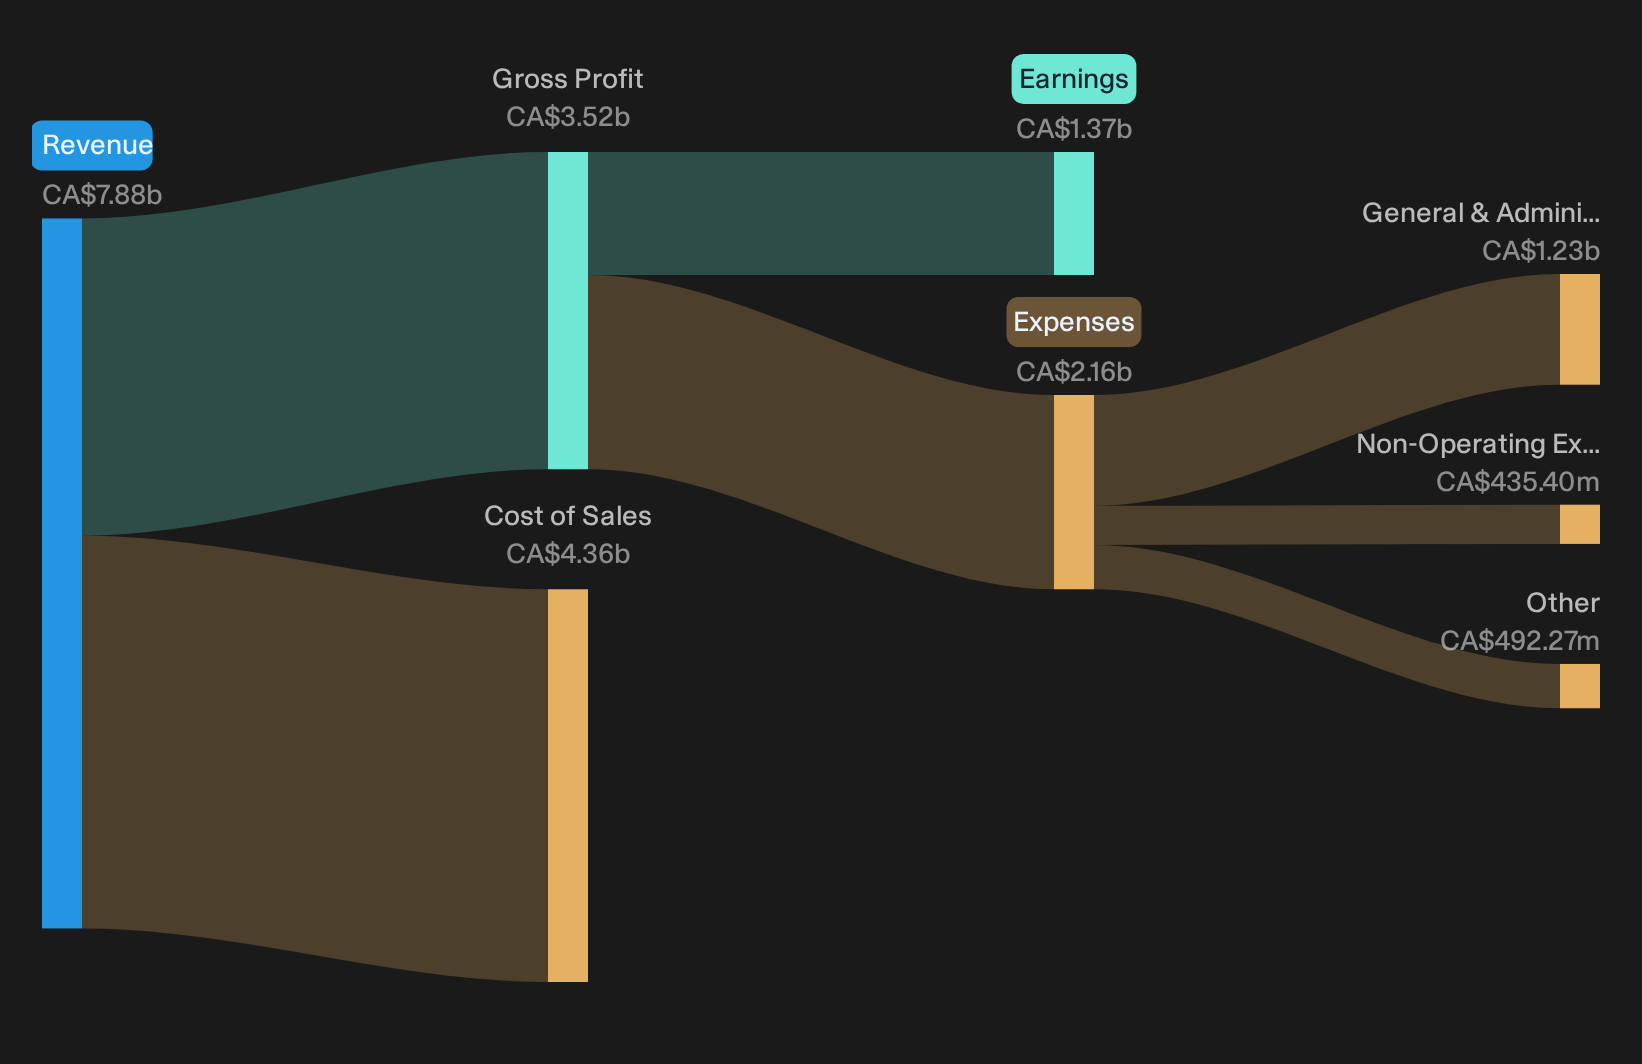
Evaluating Dollarama’s Expansion And Margin Story
The bullish angle says Dollarama can keep adding stores, scale new regions and hold margins as the network fills in. Q2 moved several of those pieces forward. Canadian same store sales of 5.4% with traffic up 3.7% show the value pitch is still pulling shoppers through the door, which is critical if a larger store base is going to stay productive. Management nudged the full year Canadian comp and net new store targets higher while leaving gross margin and SG&A guidance unchanged. This is a concrete sign they see current profitability as sustainable against higher cost pressures.
Internationally, the thesis that overseas growth becomes a second engine is showing early traction. Dollarcity earnings grew solidly, Mexico reached 21 stores with early customer interest, and 60 Australian locations now run on the Dollarama format. Those milestones support the idea that the broader footprint can eventually matter more than Canada alone.
Reveal how Dollarama’s store growth, international rollout and firm margin guidance line up with institutional expectations by checking the consensus price target analysis for Dollarama.Dollarama Bears Focus On International Drag And Growth Ceiling
The bearish line on Dollarama says a saturated Canada, risky overseas push and margin sensitivity will eventually crack the story. Q2 only partly challenges that. Canadian same store sales of 5.4% with flat gross margin guidance at 45.0 to 45.5% show the feared domestic margin squeeze did not arrive this quarter. That said, management openly flagged Australia as a deliberate sales headwind for FY27 as lower price points reset the base, which fits the concern that new markets can weigh on consolidated momentum before they help.
Critics also worry that growth must increasingly come from abroad. The raised Canadian store and SSS targets soften that argument but do not remove it. Mexico remains loss making by design and still tiny at 21 stores, so there is no clear proof yet that international expansion can offset any future slowdown in the mature Canadian network.
After a strong Canadian quarter and a deliberate drag from newer regions, the real question is whether these growing overseas commitments and the higher debt load are early warning signs or just noise. Review our independent risk analysis for Dollarama which shows 2 important warning signs to scan Dollarama’s full risk profile, including potential structural issues that may not be obvious.Stay Ahead Of Your Next Move
If Dollarama’s rich P/E and resilient earnings engine have your attention, register for free with Simply Wall St and add it to a Watchlist to track price against fair value and wait for a setup that fits your plan. Once you own any position, use the Portfolio Command Center to cut through noise and get focused updates on the metrics that matter most to you. Over the longer haul, compare your thinking with thousands of other investors through the Community and spot shifts in sentiment early. By surfacing hidden catalysts and potential risks before they are obvious, Simply Wall St helps you stay a step ahead of the wider market.
Seeking Alternatives Beyond Dollarama?
Fresh ideas move first when breakouts start forming and quiet momentum names stop flying under the radar for now. Scan curated opportunities before the crowd and act now.
- Spot cash rich compounders with room to run by scanning our curated list of solid balance sheet and fundamentals stocks (6 results) while valuations and expectations still look reasonable for patient investors.
- Hunt for under followed potential breakout candidates with strong fundamentals using the curated 9 high quality undiscovered gems before shifting sentiment pulls them into the spotlight.
- Target steady payers built for turbulence by checking the hand picked 2 dividend fortresses while yields and coverage metrics still look appealing for income focused portfolios.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com