


Does Turnaround Doubts Change The Bull Case For Nike Stock (NKE)?
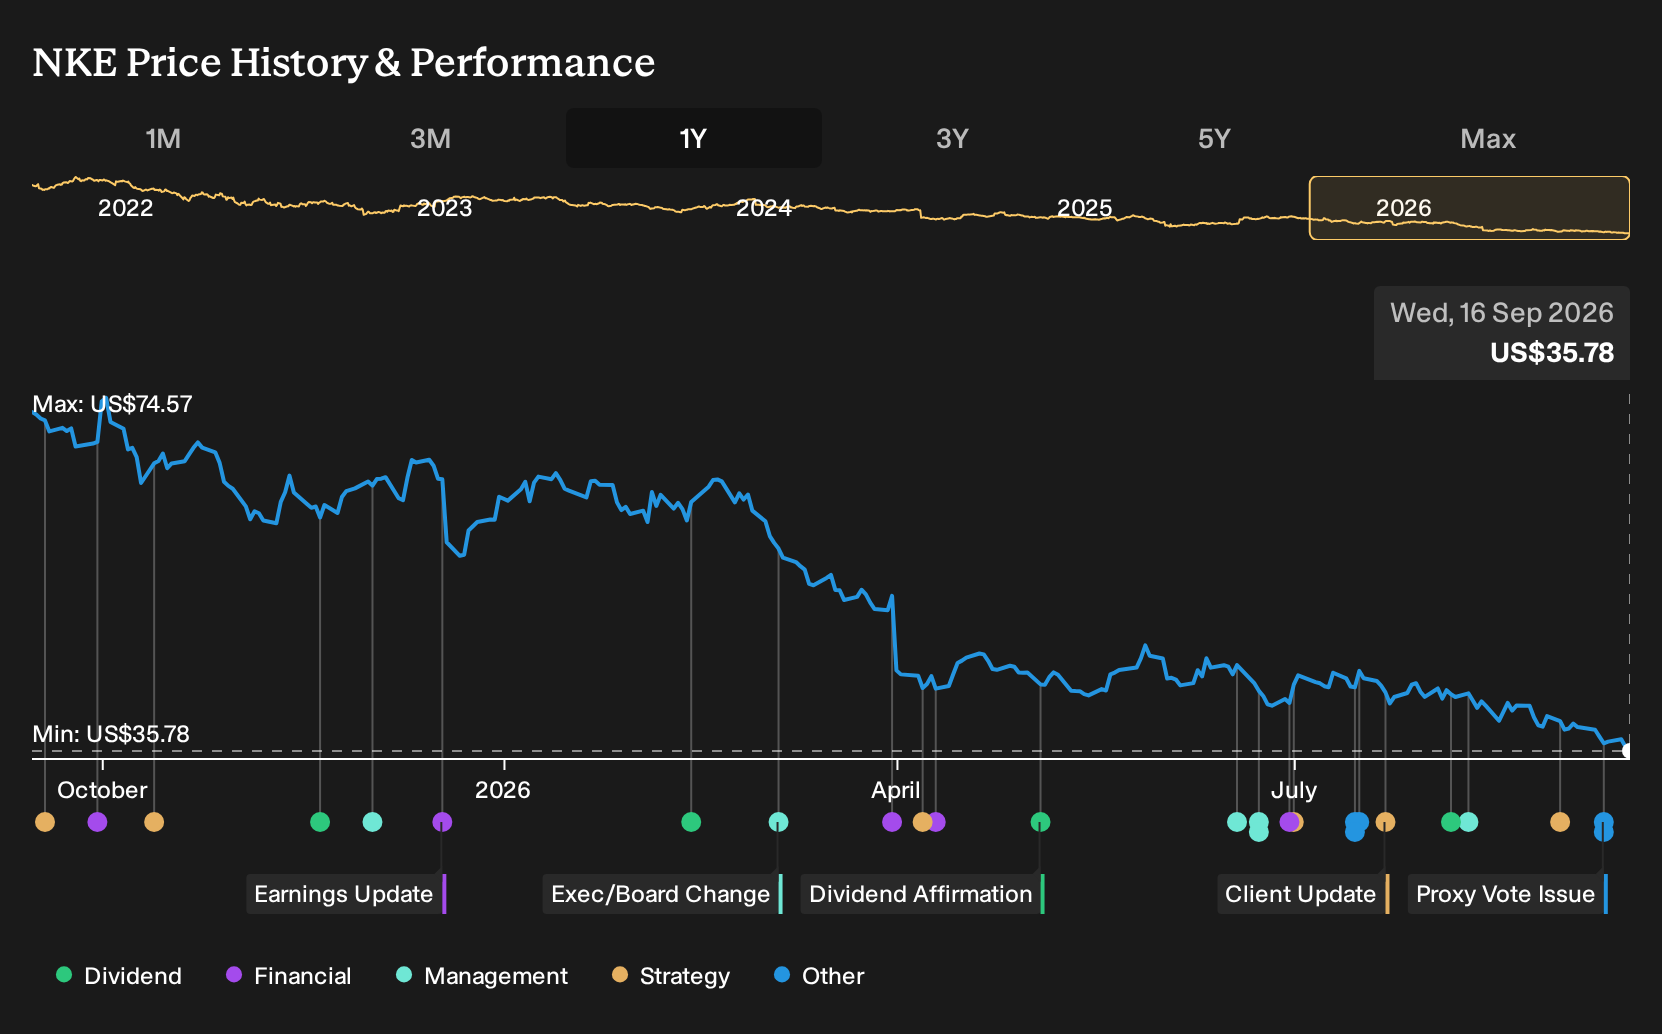
- Nike expanded its board to twelve directors and appointed Alexandre Arnault, Deputy CEO of Moët Hennessy and experienced luxury executive. Shareholders also recently voted down proposals on environmental targets and charitable giving disclosures.
- The combination of a new director with deep brand and digital experience and rejected ESG proposals highlights Nike's focus on operational recovery and brand positioning over additional reporting commitments.
- We will examine how Nike's turnaround narrative is influenced by Arnault's board appointment and the unsuccessful environmental targets proposal.
NIKE Investment Narrative Recap
To own Nike here, you need to believe the brand can turn product refresh, sport performance focus, and cleaner distribution into steadier demand after a tough stretch in key regions. The near term story still leans on better product sell through and more disciplined promotions, rather than a significant acceleration in revenue.
The main short term catalyst is execution around the integrated marketplace and inventory clean up, which directly affects gross margin pressure from markdowns and wholesale discounts. The largest risk remains further revenue softness in Greater China, EMEA, or digital, which could prolong discounting and delay any relief to earnings and cash generation.
The board appointment of Alexandre Arnault is the announcement that fits this moment best. Nike is trying to rebalance between sport performance and lifestyle, reignite demand creation, and regain traction in direct channels while keeping wholesale partners aligned. His background in brand and product at LVMH, Tiffany & Co., and RIMOWA aligns with that operational puzzle.
This move does not change the near term earnings setup by itself, especially with analysts expecting EPS pressure into the upcoming October 1 report. It does slightly strengthen the bench around brand stewardship and digital execution. For investors, the more immediate watchpoints remain China trends, markdown intensity, and whether inventory and promotions start to look less heavy.
Based on current analyst models, NIKE's narrative projects US$49.0b in revenue and US$3.7b in earnings by 2029, supported by an annual revenue growth rate of 1.8% and an earnings increase of about US$0.6b from the current US$3.1b level.
Uncover why NIKE's fair value indicates a 43% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Some of the lowest Nike analysts focus on brand risk rather than margins. They worry that weaker appeal with younger consumers could keep revenue closer to about US$47.8b and earnings near US$3.2b by 2029, far below consensus. Those expectations were set before Arnault joined the board, so you may see those narratives evolve.
Explore 9 other NIKE fair value estimates, including one that suggests it could be worth just $36.83.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your NIKE research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NIKE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NIKE's overall financial health at a glance.
Looking for more NIKE sized investment ideas?
If the NIKE story has you thinking about where else mispriced brand and quality stories might be hiding, the Simply Wall St Screener can help you build a broader watchlist across sectors and risk profiles.
- For investors who want potential upside with tighter risk controls, start with a curated set of 11 resilient stocks with low risk scores that score well on resilience.
- If balance sheet strength matters most to you, focus on companies in our list of solid balance sheet and fundamentals (22 results) to see which businesses might better support long term compounding.
- If you prefer to fish where fewer people are looking but still care about fundamentals, then scan through our 16 high quality undiscovered gems and see which lesser known stocks may warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com