


How Investors May Respond To Supermicro (SMCI) AI Growth And Control Questions
- Super Micro Computer is in focus after Axelera AI’s Europa inference processors were linked to future Dell and Supermicro systems, alongside reports of a record AI hardware backlog, strong recent quarterly results, and upcoming earnings with very large year over year revenue and profit estimates.
- At the same time, renewed scrutiny of Super Micro Computer’s IT controls and questions around future AI spending highlight that execution quality and customer budget decisions remain just as important as new product wins.
- We will now look at how Super Micro Computer’s investment narrative could be affected by strong AI demand alongside fresh control concerns.
Super Micro Computer Investment Narrative Recap
To own Super Micro Computer, you need to believe that AI infrastructure demand stays strong enough for its rack scale servers and liquid cooling offerings to keep winning large deployments, and that the record US$60b backlog can be delivered efficiently. The most important near term catalyst still sits with the upcoming earnings print and how booked AI projects convert into recognized revenue and cash flow.
Fresh scrutiny of IT controls is the biggest risk in the near term. The disclosed material IT control weakness lands right as investors are watching governance around AI infrastructure more closely. If remediation is slow or disclosure quality disappoints, confidence in reported numbers and the durability of that backlog could come under pressure.
The Europa inference processor announcement with Axelera AI is the most relevant operational update here. Super Micro Computer is expected to feature Europa in future systems alongside Dell. This would put it directly in the conversation for on premises inference workloads in sectors such as financial services, healthcare, legal, and government that prioritize data sovereignty and cost efficiency.
This matters for catalysts because it extends Super Micro Computer beyond GPU centric AI training builds into a broader mix of inference oriented deployments. Execution will hinge on how quickly Europa based systems move from potential pipeline into firm orders and how margins compare with existing AI servers. If enterprises slow AI budgets or prefer competitors, the practical impact of this partnership could remain limited.
Super Micro Computer's current narrative assumes revenue reaches US$91.7b and earnings come in at US$3.4b by 2029. Analysts are building this on a 32.9% yearly revenue growth rate and an earnings increase of about US$1.2b from US$2.2b today.
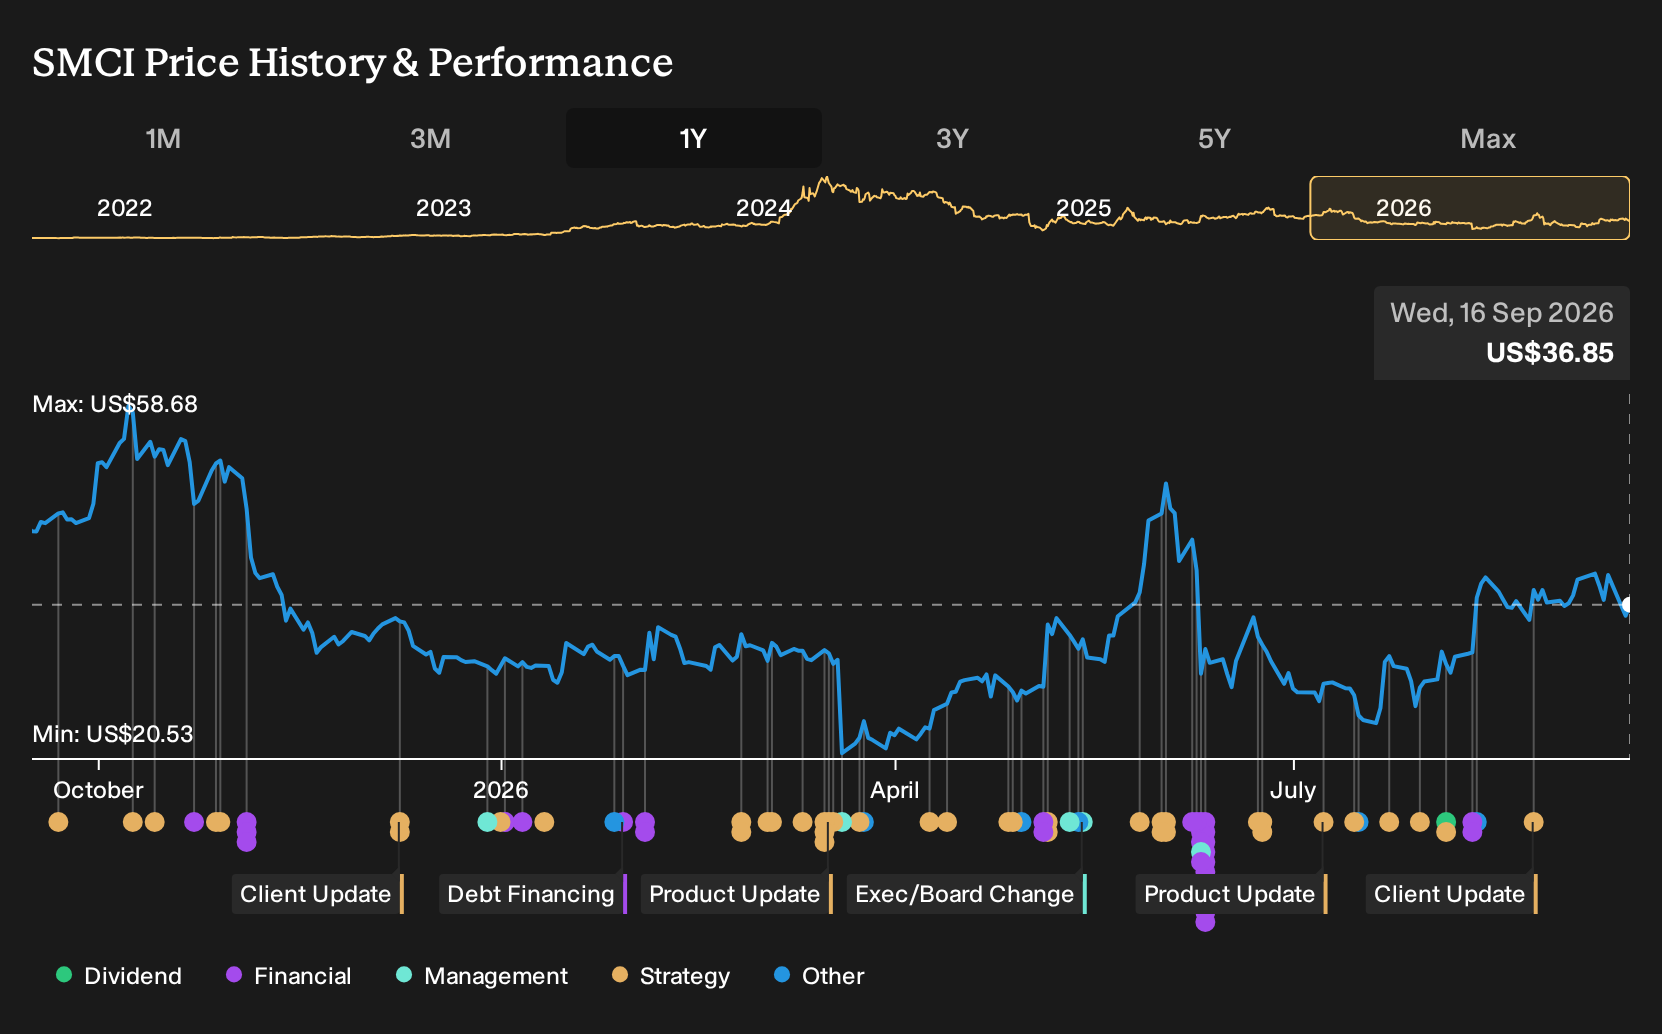
Uncover how Super Micro Computer's fair value indicates a 13% potential upside to its current price, before competitive AI infrastructure expectations close that gap.
Exploring Other Perspectives
One alternative view focuses on Super Micro Computer’s customer concentration risk rather than the Europa upside. Some of the highest analysts worry that losing a major buyer could hit those long AI infrastructure plans, even though they were still pencilling in about US$93.5b of revenue and US$2.8b of earnings by 2029 before this news. You should see this Europa update as a fresh data point that could shift both the bullish and cautious narratives, and use it to stress test which scenario you find more reasonable.
Explore 10 other Super Micro Computer fair value estimates, including one that suggests as much as 56% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Super Micro Computer research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Super Micro Computer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Super Micro Computer's overall financial health at a glance.
Looking for more Super Micro Computer style investment ideas?
If Super Micro Computer has you thinking about where AI infrastructure tailwinds and risk controls intersect, it can help to widen the lens and scan other companies through the Simply Wall St Screener before you commit fresh capital.
- For investors who want stronger fundamentals at a discount, start with a focused set of 33 high quality undervalued stocks that pair quality with more modest pricing.
- If capital preservation is your priority, filter for 11 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- To broaden your watchlist beyond well known tickers, scan a curated pool of 16 high quality undiscovered gems that combine solid metrics with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com