


Should Strong Q4 Growth Require Action From Ubiquiti (UI) Investors?
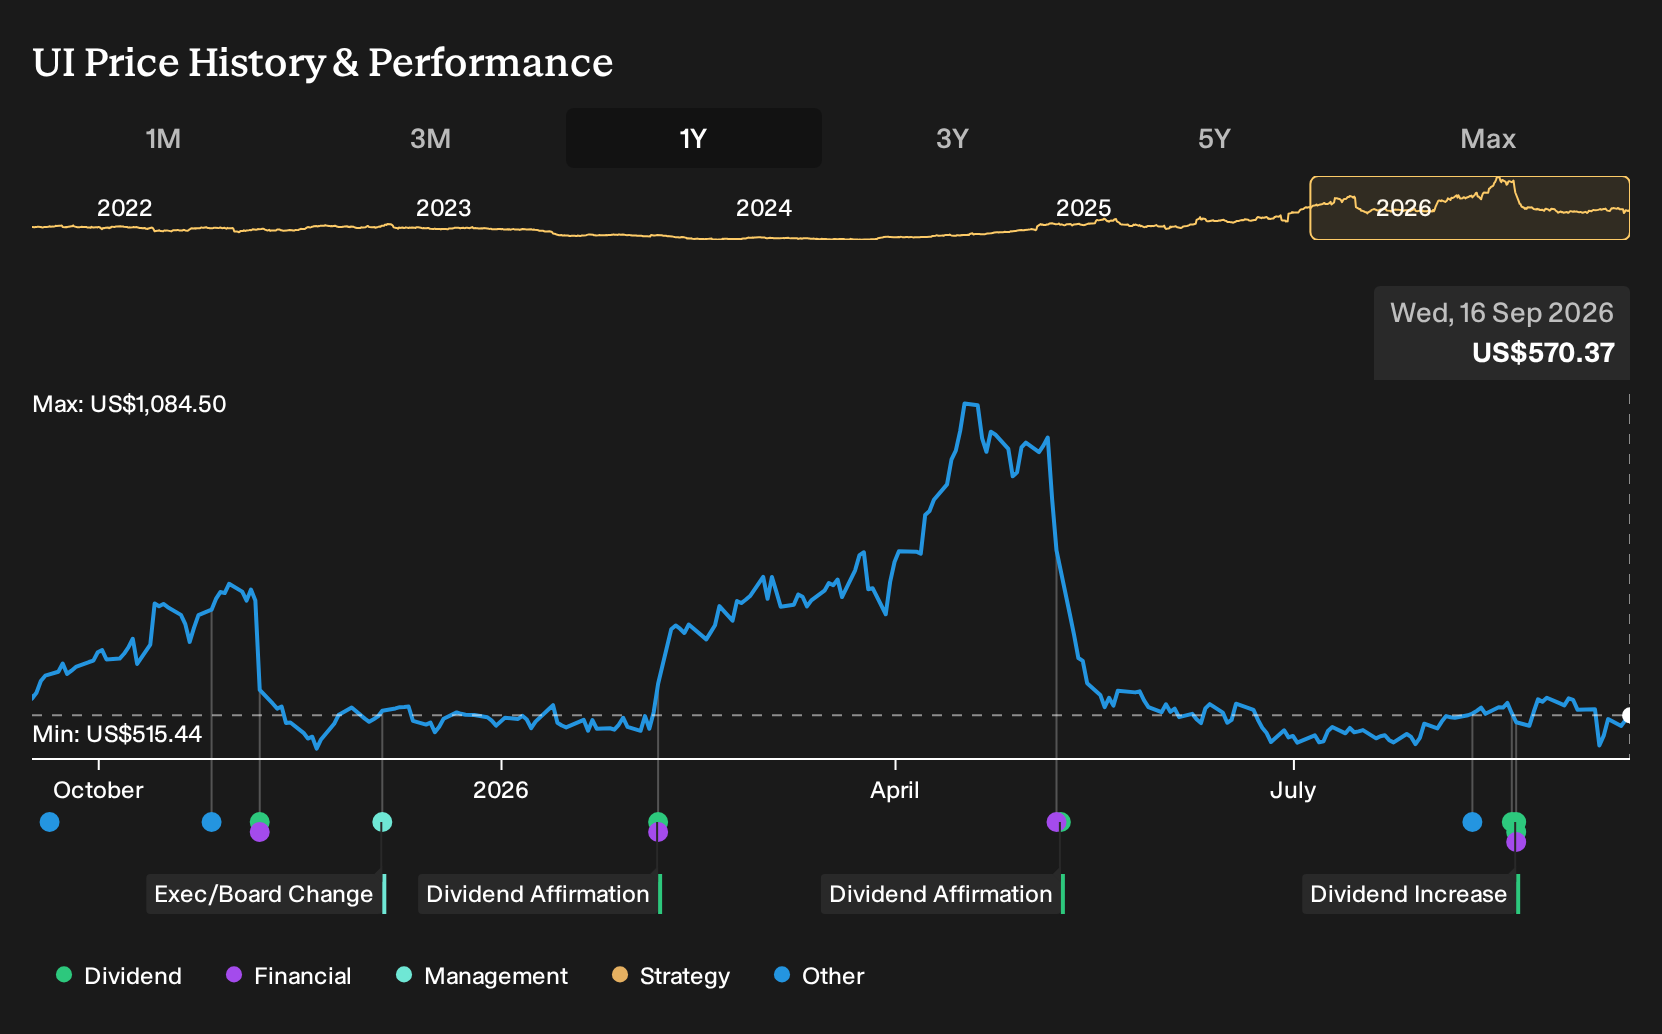
- Ubiquiti reported Q4 fiscal 2026 revenue growth of 23.5%, led by its Enterprise Technology platform across North America, EMEA, and Asia Pacific. The board declared a $1 per share dividend with plans to keep at least that level over the coming year.
- The combination of higher enterprise demand and a committed dividend payout comes alongside pressure points from supply constraints and rising component costs that could weigh on near term gross margins and product availability.
- Now the focus shifts to how Ubiquiti’s investment narrative absorbs strong 23.5% Q4 revenue growth while contending with supply and cost pressures.
What Is Ubiquiti's Investment Narrative?
To own Ubiquiti, you have to buy into a fairly simple idea. The business lives or dies on consistent demand for its networking platforms and on its ability to produce and ship hardware at scale without eroding profitability. The 23.5% Q4 revenue growth and stronger Enterprise Technology traction say customers are showing up. The newly affirmed US$1 per share dividend suggests management is comfortable sharing cash with investors while still funding operations.
The near term story is less about headline growth and more about execution under constraint. Supply bottlenecks and rising component costs directly touch gross margins, pricing power, and how quickly Ubiquiti can convert orders into revenue. If those pressures persist, they could influence how much flexibility the company has around capital spending and future shareholder returns, even with the current dividend stance in place.
Still, there is one element in Ubiquiti’s setup that quietly cuts the other way...
There's only one way to know the right time to buy, sell or hold Ubiquiti. Head to Simply Wall St's company report for the latest analysis of Ubiquiti's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has produced 5 fair value estimates for Ubiquiti, ranging from about US$489 to US$1,146, with views spread across the whole spectrum. Those numbers pre date the recent dividend announcement and the 23.5% Q4 revenue figure, so you are seeing opinions that may shift as more investors reassess the story.
Explore 4 other Ubiquiti fair value estimates, including one that suggests as much as 101% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ubiquiti research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Ubiquiti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ubiquiti's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ubiquiti?
If Ubiquiti has sharpened your thinking around the balance between income and growth, it can be useful to compare it with other companies that share similar traits or offer something completely different. The Simply Wall St Screener lets you scan for specific combinations of balance sheet strength, value, and income so you can build a watchlist that suits how you like to invest.
- Prefer to keep a cushion under your capital and filter for steadier profiles that still have room to grow? Start with a group of 11 resilient stocks with low risk scores that aim to keep downside pressures more contained.
- If you want to tilt toward potential mispricings and are willing to put in the work on each business, use the collection of 16 high quality undiscovered gems as a hunting ground for underfollowed ideas.
- For investors who like the reassurance of stronger finances at the company level, build a shortlist from the list of solid balance sheet and fundamentals (22 results) and focus your research on those that match your return and risk preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com