


Could Power Orchestration Change The Case For TD SYNNEX Stock?
- Hammerhead AI previously announced a collaboration that appoints TD SYNNEX as distributor and integrator for ORCA, software that turns stranded data center power into AI capacity, with a standardized megawatt SKU offered through more than 150,000 resellers.
- The ORCA partnership plugs directly into TD SYNNEX’s Destination AI efforts, tying power orchestration, data center efficiency, and AI workload deployment into a repeatable offering for neoclouds, AI providers, colocation operators, and enterprises.
- We will now assess how TD SYNNEX’s role distributing ORCA power orchestration software could influence its broader investment narrative and risk profile.
Scan beyond TD SYNNEX and size up other potential winners in AI infrastructure by reviewing our hand picked 60 AI infrastructure stocks, which is aligned with this data center power shift.
TD SYNNEX Investment Narrative Recap
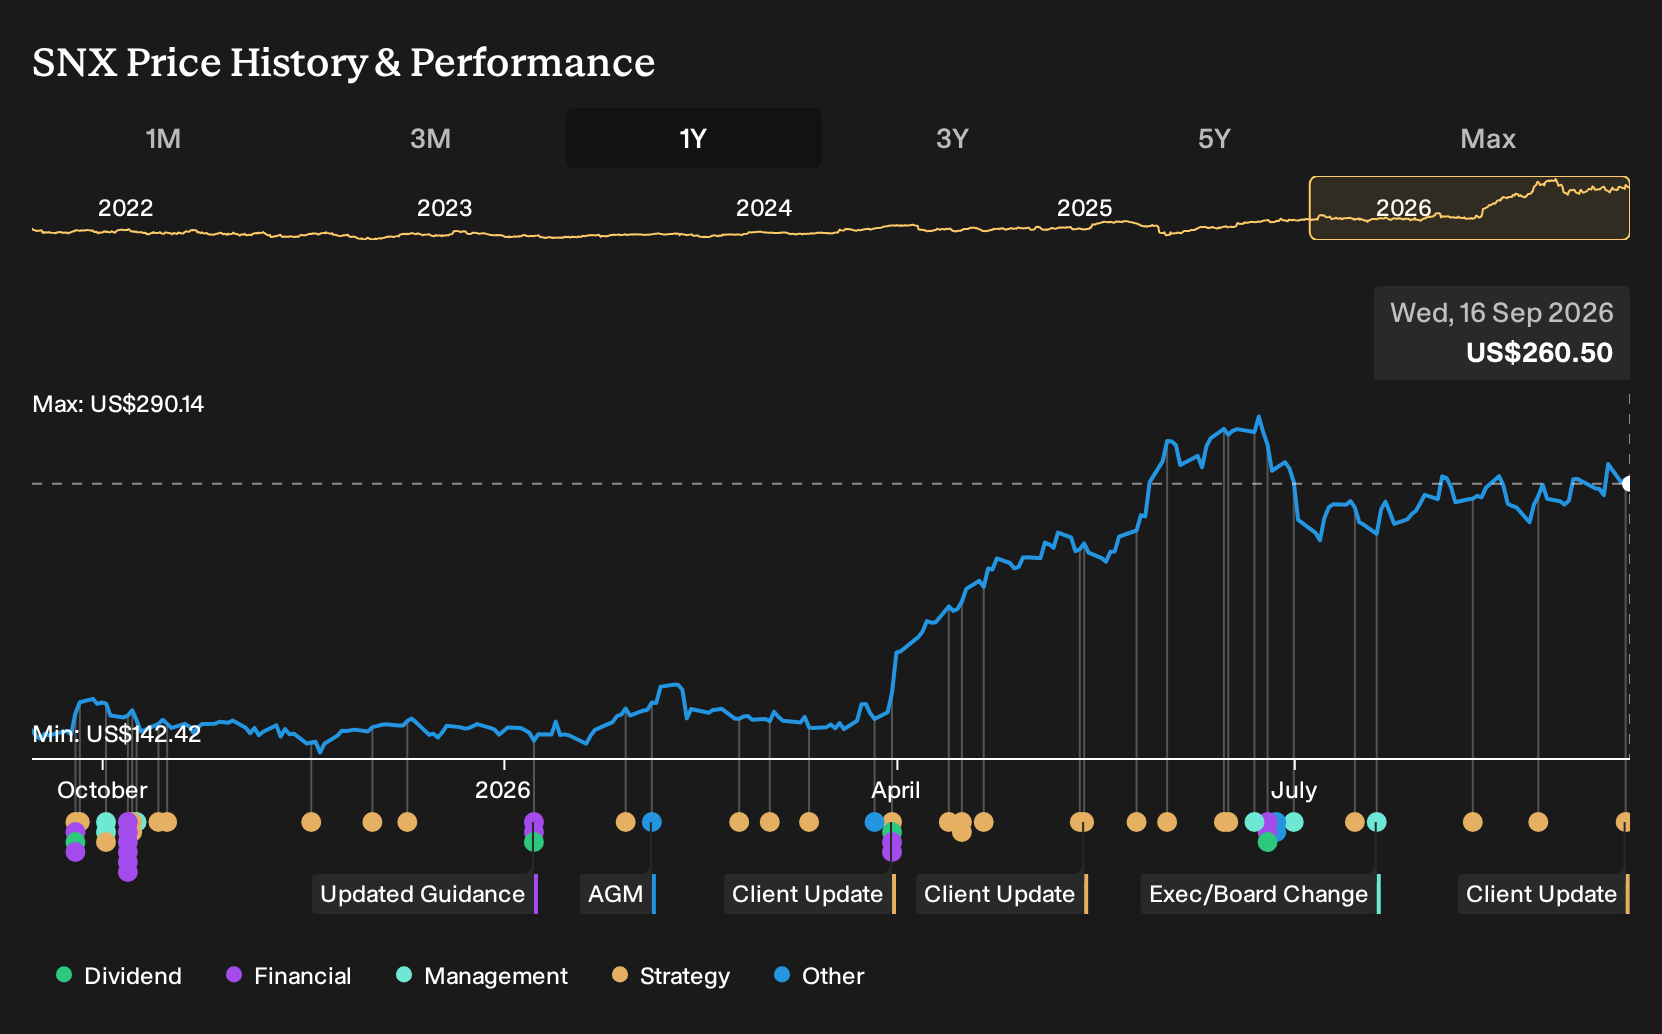
To own TD SYNNEX, you need to believe the distributor can keep shifting its mix toward higher value cloud, software, AI infrastructure and services while managing thin margins and debt that is not fully covered by operating cash flow. The Hammerhead ORCA deal fits that story by plugging TD SYNNEX deeper into AI data center workflows rather than just moving hardware boxes.
In the near term, the key swing factor still sits with execution in Advanced Solutions and Hyve around complex data center and AI builds, especially with some demand already pulled forward into earlier quarters. The biggest risk remains margin and volume pressure if customers slow orders or large accounts, including Hyve’s biggest client, trim spend, which could matter more than any single AI partnership.
The most relevant recent development is the focus on upcoming fiscal Q3 results, where Hyve performance and operating margins are expected to be in the spotlight. That earnings print is likely to shape how investors see the durability of recent earnings growth and whether TD SYNNEX is turning higher value integration work into better profitability.
Layering the ORCA distribution agreement on top of this earnings setup gives Hyve and Advanced Solutions another AI driven offering to sell into data center customers that are constrained by power rather than chips. The operational question is whether TD SYNNEX can convert this software led opportunity into repeatable, margin accretive projects at scale before macro, customer concentration, or as a service shifts erode traditional distribution economics.
TD SYNNEX's narrative projects US$90.7b revenue and US$1.6b earnings by 2029. This implies 9.1% yearly revenue growth and an earnings increase of about US$0.5b from US$1.1b today.
Uncover why TD SYNNEX's fair value indicates a 28% potential upside to its current price before the discount closes.
Exploring Other Perspectives
Some of the lowest TD SYNNEX estimates lean hard into customer concentration risk at Hyve. Those analysts were penciling in revenue of about US$87.2b and earnings of roughly US$1.6b by 2029 on a lower 18.1x P/E. You can treat the new ORCA power orchestration deal as a live test of whether that pessimism holds.
Explore 2 other TD SYNNEX fair value estimates, including one that suggests it could be worth just $289.56.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TD SYNNEX research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TD SYNNEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TD SYNNEX's overall financial health at a glance.
Looking For More Ideas Beyond TD SYNNEX?
If the TD SYNNEX story has you thinking about where else to put fresh capital to work, a focused screener can help you quickly surface stocks that fit your style without trawling through endless tickers.
- For investors who want potential upside with an eye on valuation discipline, consider starting with a curated set of 33 high quality undervalued stocks that already clear basic quality hurdles.
- If stability matters more than excitement, filter for resilience using a 11 resilient stocks with low risk scores that concentrates on businesses with lower risk scores and steadier profiles.
- When you want balance sheet strength to anchor your research, zero in on companies from a list of solid balance sheet and fundamentals (22 results) that pair financial robustness with underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com