


Discovering Undiscovered Gems in Asia for September 2026
As the Asian markets navigate a landscape marked by geopolitical tensions and fluctuating energy prices, investors are keenly observing how these dynamics influence small-cap stocks across the region. With indices like the Russell 2000 experiencing notable declines due to inflation concerns and rising oil prices, identifying promising opportunities in Asia requires a focus on companies that demonstrate resilience through strong fundamentals and adaptability to market shifts.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Delijia Transmission Technology (Jiangsu)Ltd | 7.09% | 14.57% | 15.98% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Shanghai Fudan Microelectronics Group (SEHK:1385)
Simply Wall St Value Rating: ★★★★★☆
Overview: Shanghai Fudan Microelectronics Group Company Limited focuses on the design, development, and sale of integrated circuit products both in Mainland China and internationally, with a market capitalization of HK$42.06 billion.
Operations: The company generates revenue primarily from the sale of integrated circuit products. Its financial performance is highlighted by a gross profit margin that exhibits notable trends over recent periods.
Shanghai Fudan Microelectronics Group is making waves with its impressive earnings growth of 112.4% over the past year, outpacing the semiconductor industry average of 39%. Trading at a significant 46.6% below estimated fair value, it presents an intriguing opportunity for investors. The company's EBIT covers interest payments by a robust 18.6 times, indicating strong financial health. Recent developments include entering a joint venture with Zhuoyuan Ruixin and others, contributing intangible assets valued at CN¥17.5 million to this partnership aimed at expanding their market reach in China’s tech landscape.

Zhuzhou Smelter GroupLtd (SHSE:600961)
Simply Wall St Value Rating: ★★★★★★
Overview: Zhuzhou Smelter Group Co., Ltd. operates in China, producing and selling zinc and alloy products under the Torch brand, with a market capitalization of CN¥27.64 billion.
Operations: The primary revenue stream for Zhuzhou Smelter Group Ltd. comes from its lead and zinc products, generating CN¥25.99 billion. The company's financial performance is influenced by its ability to manage costs associated with production and sales in this segment.
Zhuzhou Smelter Group has captured attention with its robust financial performance and industry positioning. The company's net income soared to CNY 1.95 billion for the first half of 2026, up from CNY 585 million the previous year, reflecting a significant boost in profitability. With earnings per share climbing to CNY 1.8 from CNY 0.51, Zhuzhou's growth outpaces the broader Metals and Mining sector, which saw a more modest increase of 23%. Its debt-to-equity ratio impressively dropped from over 414% to just over 10% in five years, indicating improved financial health and strategic debt management.
- Dive into the specifics of Zhuzhou Smelter GroupLtd here with our thorough health report.
Understand Zhuzhou Smelter GroupLtd's track record by examining our Past report.
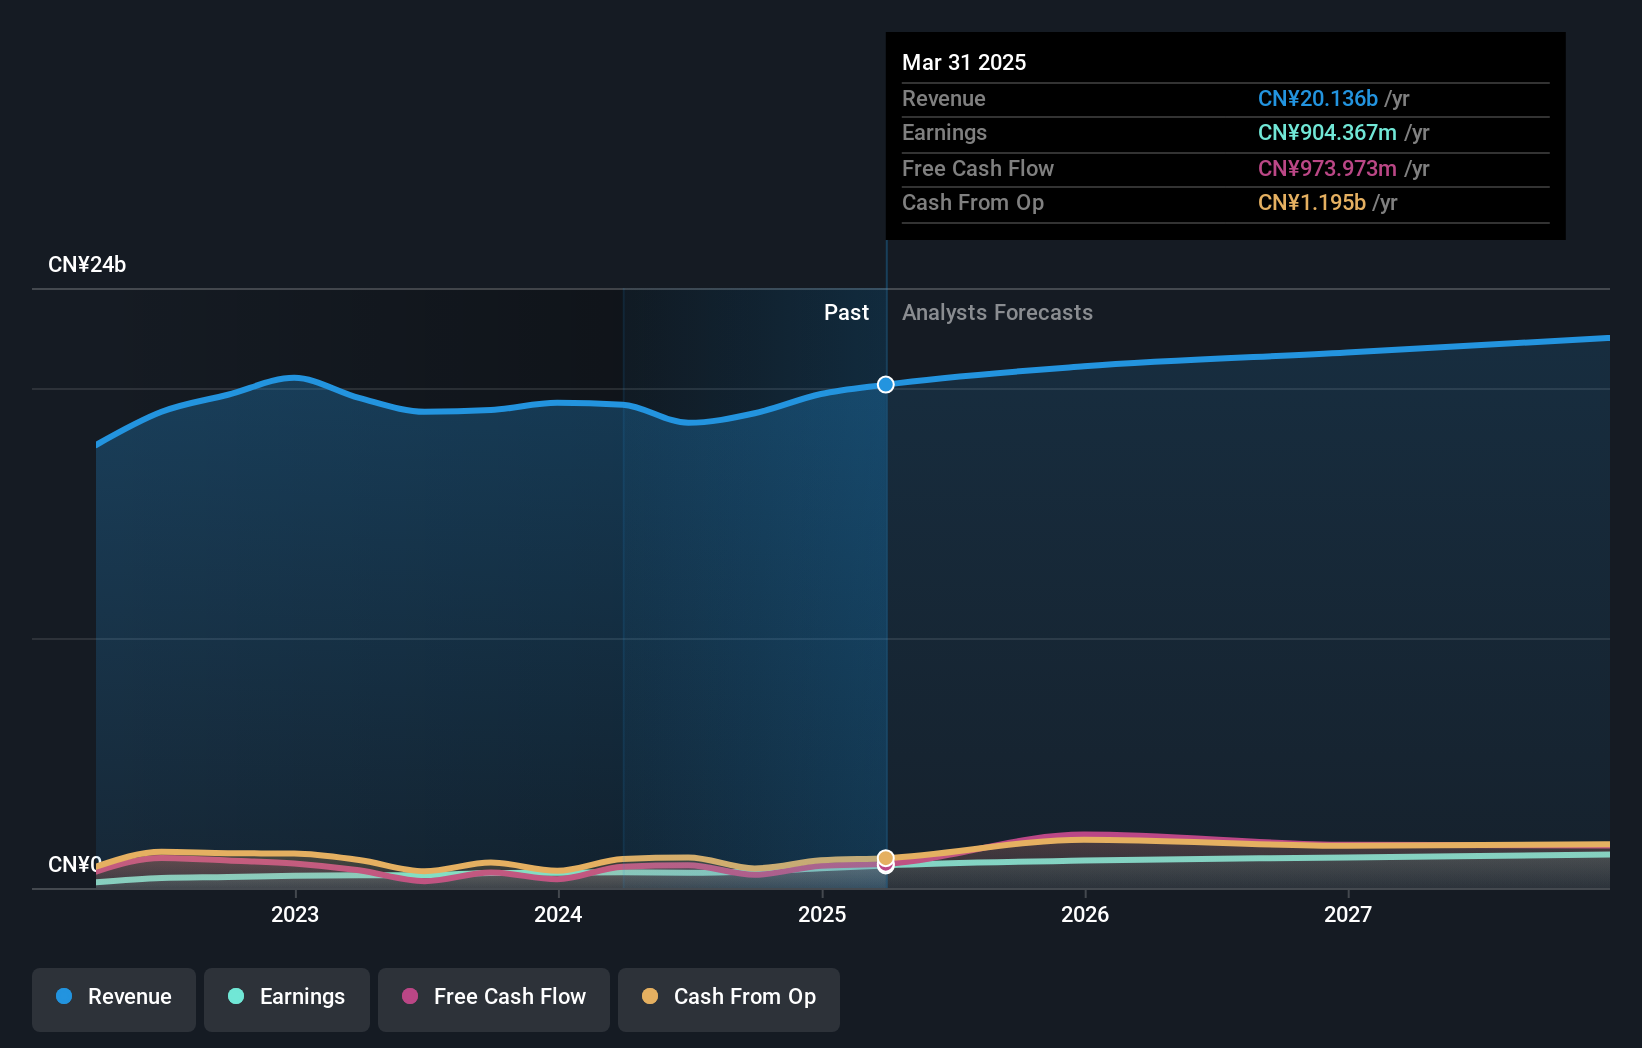
Shengda ResourcesLtd (SZSE:000603)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Shengda Resources Co., Ltd. operates in China through its subsidiaries, focusing on the mining, beneficiation, and sale of precious and non-ferrous metal ores, with a market capitalization of CN¥24.15 billion.
Operations: Shengda Resources generates revenue primarily from the mining, beneficiation, and sale of precious and non-ferrous metal ores. The company's financial performance is influenced by its ability to manage costs associated with these operations. Its market capitalization stands at CN¥24.15 billion.
Shengda Resources, a nimble player in the metals and mining sector, has shown impressive growth with earnings surging 125.7% over the past year, outpacing industry growth of 23.3%. Trading at 50.7% below its estimated fair value, it presents an attractive proposition for value seekers. The company's net debt to equity ratio stands at a satisfactory 29%, reflecting prudent financial management amidst a volatile share price environment over the last three months. Shengda's recent half-year results reveal robust sales of CNY 1.1 billion and net income jumping to CNY 390 million from CNY 70 million previously, highlighting strong operational performance.
- Get an in-depth perspective on Shengda ResourcesLtd's performance by reading our health report here.

Seize The Opportunity
- Navigate through the entire inventory of 118 Asian Undiscovered Gems With Strong Fundamentals here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com