


LTC Properties (LTC) Gains Ground On Momentum, Is It Still Below Fair Value?
LTC Properties (LTC) has drawn fresh attention after its shares closed at $43.08 on 15 September 2026, with recent returns showing double digit gains over the past 3 months and year.
LTC Properties’ recent run has come with a small pause, with the share price slipping 0.87% over the last trading day after a 24.33% year-to-date share price return and a 28.84% total shareholder return over 1 year. This points to momentum that is still building rather than fading.
Scan how LTC Properties stacks up against other real estate investment trusts showing similar momentum by reviewing the hand picked list of solid balance sheet and fundamentals (22 results) today.
LTC Properties has already handed recent buyers strong gains, while the share price now sits near analysts’ targets and an implied intrinsic discount. Is this still an appealing entry, or a moment to wait for cheaper terms?
Most Popular Narrative: 4% Undervalued
Against a last close of $43.08, the most followed narrative puts LTC Properties’ fair value near $45, leaving only a modest gap while tying that price to a specific growth story and risk profile.
The company's ability to recycle capital out of older skilled nursing assets (via portfolio sales and potential loan prepayments) and redeploy proceeds into higher-yielding, modern properties is described as enhancing rent growth potential and operating efficiency, which is cited as supporting higher net margins and long-term NAV growth. Long-term relationships and partnerships with regional operators, together with a focus on retaining experienced management teams for acquired assets, are presented as factors that may reduce operational risk and support more stable rental income, directly affecting earnings stability.
See why 46 investors see LTC Properties as 4% undervalued.
Result: Fair Value of $45 (UNDERVALUED)
Still, the bullish script for LTC Properties can break if acquisition competition squeezes returns or if higher funding costs erode the economics of capital recycling.
Find out about the key risks to this LTC Properties narrative.
Another View on LTC Properties’ Valuation
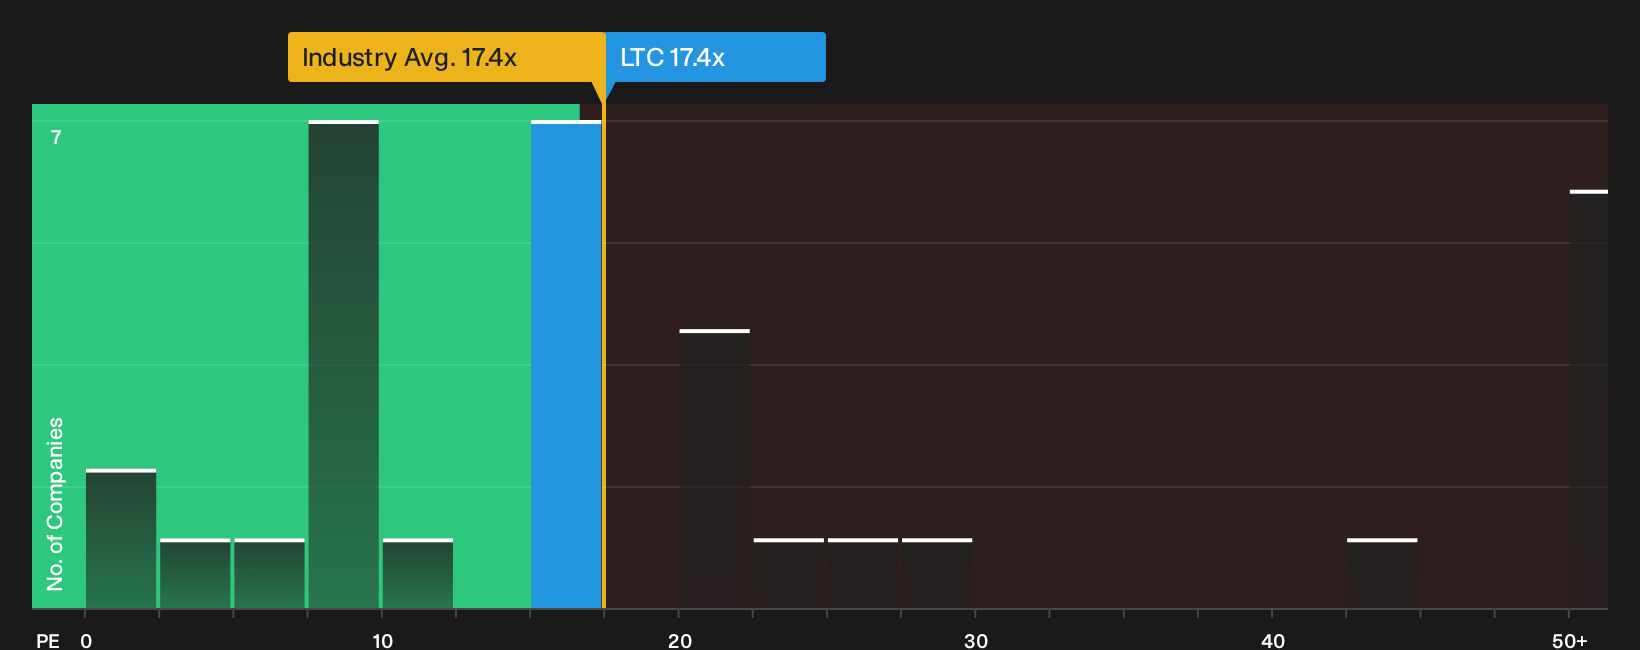
The first narrative says LTC Properties looks about 4% undervalued on a fair value of $45, yet its current P/E of 17.4x tells a different story when lined up against the numbers.
That earnings multiple is slightly higher than the Global Health Care REITs average of 17.1x, while sitting far below peers at 38.1x and an estimated fair ratio of 27.2x. The gap suggests the stock could either be priced cautiously relative to similar businesses or reflecting risks that the simple P/E comparison is not capturing. Which side of that trade-off do you think the market is really paying for?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around LTC Properties is clear, so weigh the upside story against the cautions and review the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond LTC Properties?
Once you have an opinion on LTC Properties, widen your watchlist using fresh ideas surfaced by the Simply Wall St Screener so you are not relying on a single opportunity.
- Target income resilience by reviewing companies with 5%+ yields that still look robust on fundamentals through the 6 dividend fortresses.
- Hunt for mispriced quality by scanning the 16 high quality undiscovered gems that combine solid balance sheets with less crowded investor attention.
- Dial down portfolio risk by filtering for 11 resilient stocks with low risk scores that score well on financial strength and volatility metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com