


Hua Hong Grace Stock In Focus After Hang Seng Index Addition
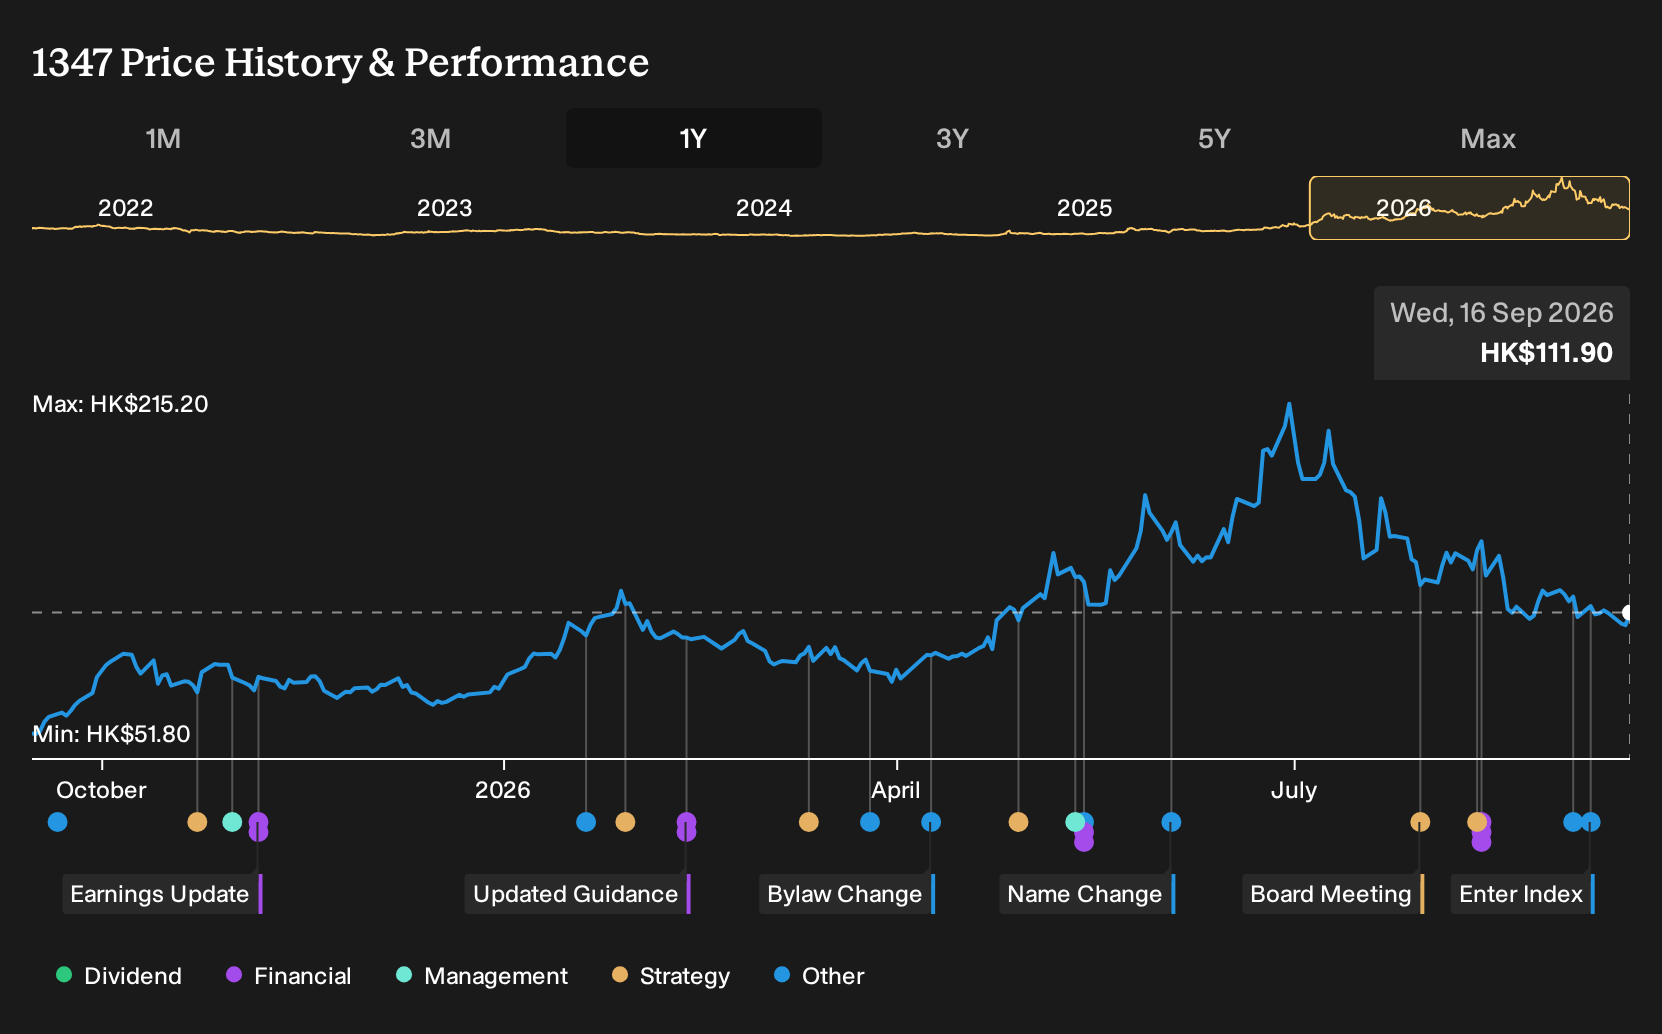
- Hua Hong Grace Semiconductor was added to the Hang Seng Index on 7 September 2026, increasing its relevance within Hong Kong’s benchmark equity universe.
- This index inclusion sharpens attention on how Hua Hong Grace Semiconductor’s capital intensive expansion and mature node focus align with broader semiconductor demand trends.
- We will examine how Hua Hong Grace Semiconductor's index inclusion interacts with its capacity heavy investment narrative and demand risk.
Scan how Hua Hong Grace Semiconductor’s index move compares with peers by reviewing hand picked 60 AI infrastructure stocks tied to the same chip capacity and infrastructure theme.
Hua Hong Grace Semiconductor Investment Narrative Recap
To own Hua Hong Grace Semiconductor, you need to be comfortable with a capital heavy expansion story that leans on mature specialty nodes and strong domestic demand. The short term focus is whether new capacity, including Fab9, fills at healthy utilization and pricing. Hang Seng Index inclusion mainly affects liquidity and visibility, not the actual fab ramp or product mix.
The key operational risk right now is that capacity build and high capex run ahead of demand from AI, EVs and industrial customers, which could pressure margins and free cash flow. Another watchpoint is the heavy China exposure, since any slowdown in local orders or policy support would quickly feed through to earnings volatility.
With no new operational announcements disclosed alongside the index move, the most relevant context is still the ongoing Fab9 build out and the plan for a further fab by 2027. That expansion sits behind analyst expectations for changes in earnings and margins, but it also raises the bar for consistent demand across automotive, industrial and AI related uses.
For you as an investor, the interaction is simple. More index driven flows can deepen the investor base at the same time as Hua Hong Grace Semiconductor ramps capacity that carries high fixed costs and higher depreciation. The main execution test remains filling that extra output at acceptable returns while managing pricing, domestic customer concentration and the risk of overcapacity in mature nodes.
Hua Hong Grace Semiconductor's current analyst narrative points to revenue of $4.3b and earnings of $403.3 million by 2029, assuming revenue expands at 19.5% per year and profit rises from $72.1 million today. This implies earnings would need to increase by about $331.2 million from current levels.
Uncover why Hua Hong Grace Semiconductor's fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative angle on Hua Hong Grace Semiconductor is geopolitical risk. The most cautious analysts worry that tighter tech nationalism could curb access to key equipment and overseas markets. Before this index inclusion, some of them were only penciling in 16.7% annual revenue growth and about $303.9 million in 2029 earnings. That is far below the consensus path and illustrates how sharply expectations can differ. Treat the Hang Seng Index news as one additional data point and compare these differing perspectives before you decide how you feel about the stock.
Explore 4 other Hua Hong Grace Semiconductor fair value estimates, including one that suggests as much as 63% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hua Hong Grace Semiconductor research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hua Hong Grace Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hua Hong Grace Semiconductor's overall financial health at a glance.
Looking for more Hua Hong Grace Semiconductor style ideas?
If you want to put Hua Hong Grace Semiconductor in context and spot other opportunities that fit your risk and return preferences, use the Simply Wall St Screener to scan for stocks with fundamentals that match your playbook.
- For investors who want value with quality on their side, review a 192 high quality undervalued stocks that combine solid cash generation with more modest valuation multiples.
- If resilience matters more than rapid growth, consider a 103 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- When you want to get ahead of the crowd, focus on a 618 high quality undiscovered gems that pair strong financial profiles with lower current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com