


Is Dividend Strength Altering The Investment Case For Wiley Stock?
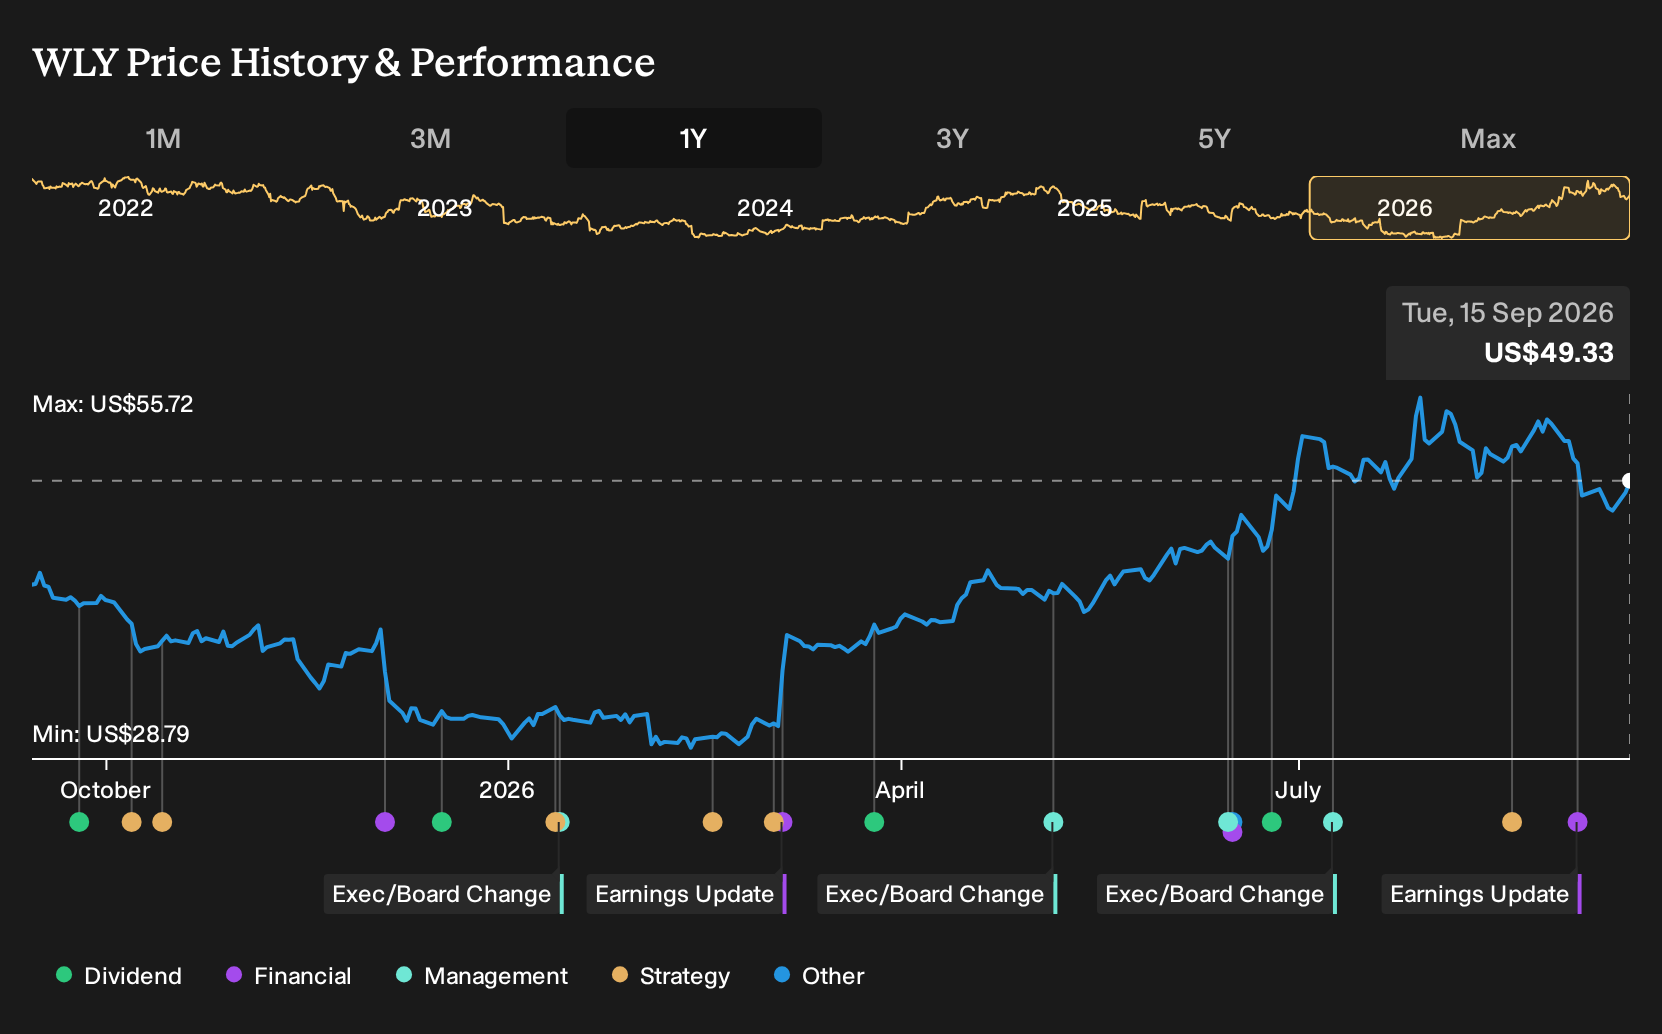
- John Wiley & Sons reported first quarter 2026 sales of US$386.36 million and a net loss of US$11.73 million, while also completing a US$57.63 million share repurchase program that retired 3.09% of its shares.
- Despite weaker quarterly figures, John Wiley & Sons' record of dividend increases and ongoing buybacks keeps income generation and capital return in focus for shareholders.
- We will assess how John Wiley & Sons' income-focused investment narrative aligns with a dividend-heavy profile alongside a quarterly loss.
John Wiley & Sons Investment Narrative Recap
To stay invested in John Wiley & Sons, you need to believe the shift toward Open Access publishing, digital learning platforms and AI licensing can offset pressure on traditional subscriptions and print. The first quarter loss of US$11.73 million, alongside US$386.36 million in sales, highlights how sensitive that transition is to timing and one off items.
The key short term swing factor is execution on higher margin digital and AI contracts while keeping costs in line. The biggest near term risk is that AI content licensing and research funding cycles remain unpredictable, which can create lumpier earnings without necessarily changing the longer term direction of the business.
The completion of the US$57.63 million buyback, which retired 3.09% of shares, sits right next to this earnings update and matters for your thesis. It indicates the share count is lower as the net loss per share from continuing operations moved to US$0.23 for the quarter, so every future dollar of profit or free cash flow is spread over fewer shares.
From an income focused angle, pairing that repurchase program with a dividend track record and a P/E of 12.6x versus an estimated fair P/E of 15.1x presents a combination of cash return and valuation support. The trade off is that debt remains elevated and results still include large one off items, so the potential impact from buybacks depends heavily on consistent execution in Research and Learning in the coming years.
John Wiley & Sons' current consensus narrative points to forecast revenues of US$1.9b and earnings of US$224.2 million by 2029, based on analysts assuming 4.7% yearly revenue growth and an earnings increase of about US$2.6 million from US$221.6 million today.
Uncover how John Wiley & Sons' fair value indicates a 38% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community currently includes 2 fair value views on John Wiley & Sons, ranging from roughly US$68 to just over US$80 per share. That spread reflects how differently private investors weigh the dividend, buybacks and the recent quarterly loss. Consider these alongside AI licensing risk, open access pressure and funding cycles, and compare several viewpoints before deciding how Wiley fits your portfolio.
Explore another John Wiley & Sons fair value estimate, including one that suggests it could be worth just $68.00!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your John Wiley & Sons research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for John Wiley & Sons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate John Wiley & Sons' overall financial health at a glance.
Looking for more investment ideas beyond John Wiley & Sons?
Once you have a handle on John Wiley & Sons and its income story, it can help to widen the lens and compare it with other listed companies that share some of the same traits or offer a very different risk profile.
- If you want income to come with staying power, focus on balance sheet strength first, then see which candidates show up in the list of solid balance sheet and fundamentals (22 results).
- For readers who care most about downside protection, start with businesses that screen well on stability and risk controls by looking through the 11 resilient stocks with low risk scores.
- If the goal is to find potential up-and-comers with solid fundamentals that are not yet widely followed, scan the 16 high quality undiscovered gems for ideas that might deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com