


How New Aura Entertainment Plans Will Impact Norwegian Cruise Line Stock
- Norwegian Cruise Line Holdings has outlined the entertainment slate for future ship Norwegian Aura, including an estate-approved Whitney Houston tribute, illusion shows, live band concepts, and adults-only nightlife, all positioned as exclusive onboard experiences following the 2026 announcement.
- The focus on branded, exclusive entertainment partnerships points to Norwegian Cruise Line Holdings leaning harder into experience-led differentiation that can support onboard spending and help justify premium pricing across a multigenerational guest base.
- We will now look at how Norwegian Cruise Line Holdings' investment narrative could be influenced by exclusive Whitney Houston themed entertainment on Aura.
Scan how Norwegian Cruise Line Holdings fits into the broader travel and experiences theme by reviewing a curated set of 16 high quality undiscovered gems that could be flying under most investors' radar.
Norwegian Cruise Line Holdings Investment Narrative Recap
Norwegian Cruise Line Holdings asks you to believe that experience-led products, private destinations and tech-enabled pricing can keep ships full and spending healthy, while a heavy debt load slowly becomes more manageable. The short-term swing factor still looks like execution on pricing and cost control, not a single show announcement on one ship.
Interest coverage and euro debt maturities in 2026 remain the biggest pressure point. The Whitney Houston program on Norwegian Aura may help onboard yields at the margin, but it does not change the core risk that financing costs and itinerary mix could cap profitability if ticket pricing or onboard revenue softens.
The most relevant update alongside Aura is still the broader catalyst story around higher-value experiences, including Great Stirrup Cay and premium cabins. Aura’s multigenerational entertainment lineup, led by the Whitney Houston tribute, fits that same playbook of giving guests more reasons to spend while on board.
For you as a shareholder, the question is whether Norwegian Cruise Line Holdings can repeat this format across the fleet and keep unit costs in check while doing it. Execution risk stays high given leverage and interest expense. If the rollout of premium experiences stalls or costs creep up, the earnings path analysts outline becomes harder to reach.
Norwegian Cruise Line Holdings is framed around consensus expectations that revenues reach $11.6b and earnings reach $895.5m by 2029, based on analysts’ assumption of 4.5% yearly top line growth and an earnings step up of about $134.7m from $760.8m today. This implies a moderate increase in profitability rather than a transformation.
Discover how Norwegian Cruise Line Holdings' fair value suggests a 45% potential upside to its current price before that discount begins to narrow.
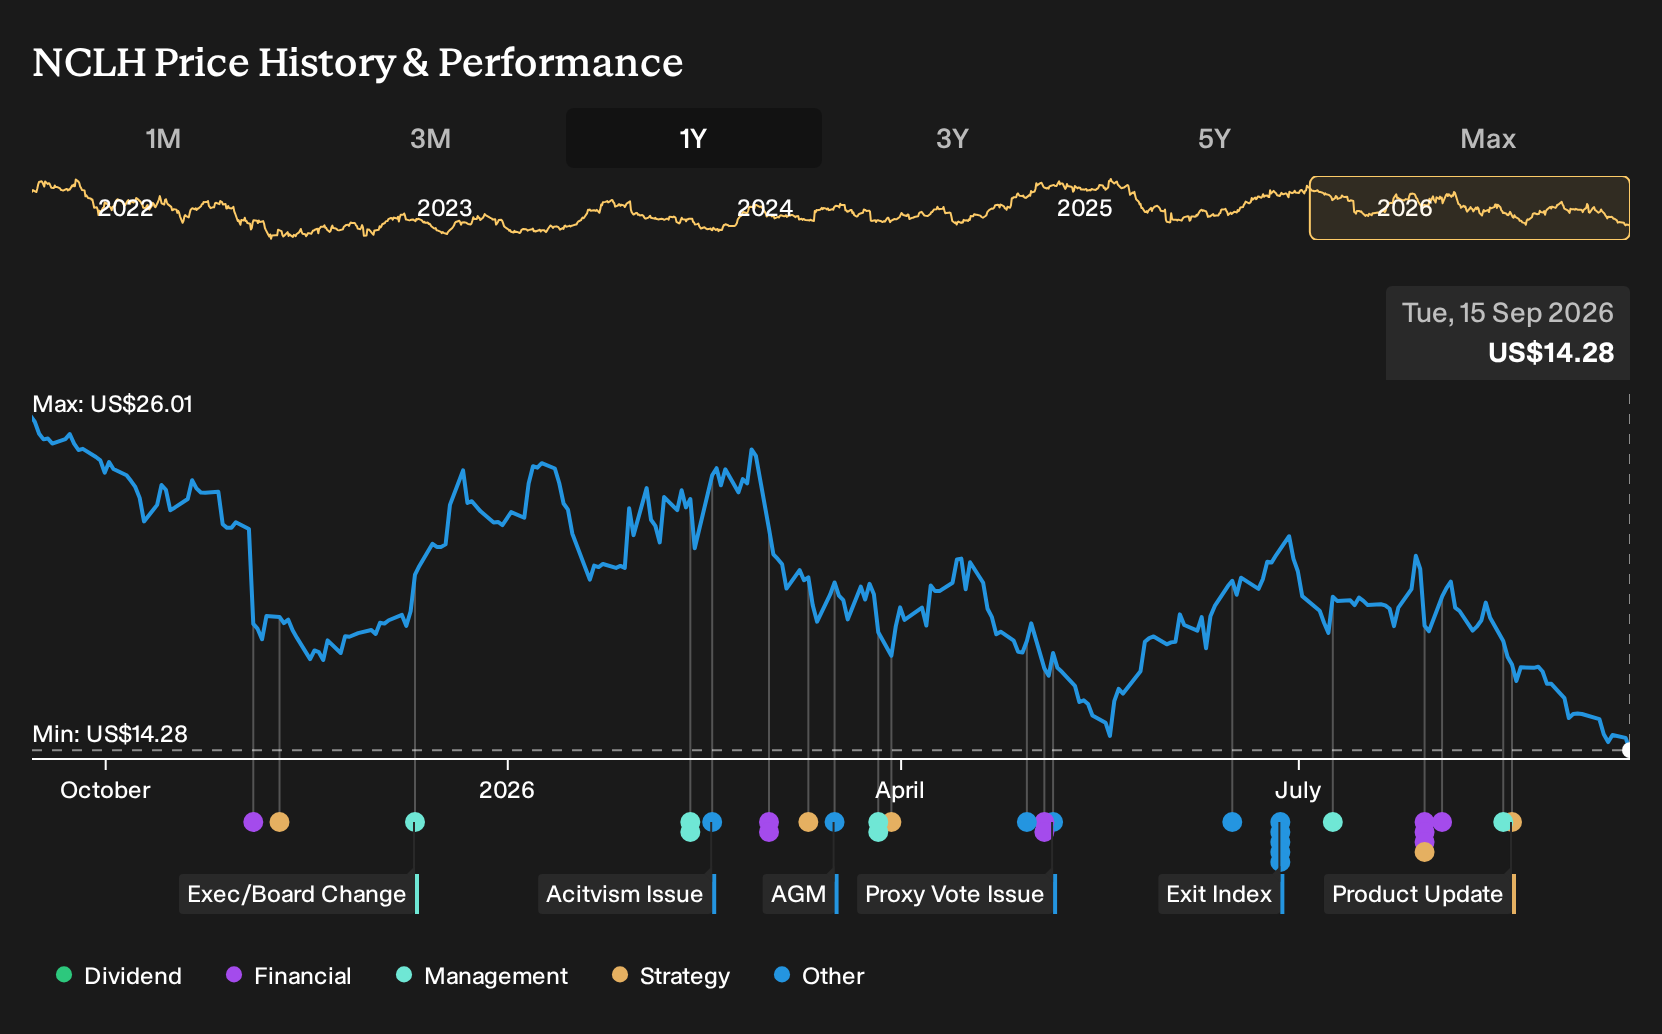
Exploring Other Perspectives
For Norwegian Cruise Line Holdings, a significant additional concern is the prospect of tighter environmental regulation. The most bearish analysts were estimating revenue of about $11.5b and earnings of $793.0m by 2029, well below the $1.3b upside case. At that time, they had not yet seen the Whitney Houston entertainment news that could influence those projections.
Explore 4 other Norwegian Cruise Line Holdings fair value estimates, including one that suggests as much as 70% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Norwegian Cruise Line Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Norwegian Cruise Line Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norwegian Cruise Line Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Norwegian Cruise Line Holdings?
If the Norwegian Cruise Line Holdings story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can surface other businesses that fit very different risk and return profiles.
- If capital preservation matters most to you right now, start with a group of companies that screen as relatively sturdy by reviewing a 11 resilient stocks with low risk scores.
- If you care about financial strength and staying power, check out a list of solid balance sheet and fundamentals (22 results) that can help you focus on businesses with cleaner balance sheets and healthier fundamentals.
- If you are hunting for mispriced opportunities that may not be widely followed, cast the net wider with a 16 high quality undiscovered gems that could add fresh ideas to your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com