


What Do Two Board Exits Mean For Insulet (PODD) Shareholders?
- Insulet (NasdaqGS:PODD) announced that two long-serving directors, including a former Chair, will leave the board for personal reasons.
- One departing director is stepping aside due to health issues, while the other plans to pursue an active political career.
- The board changes, involving two influential figures at the same time, raise fresh questions about future governance and oversight at Insulet.
- The twin resignations of a former Chair and a politically focused director come against broader themes our research has uncovered. Take a look at 3 other big wins we have identified for Insulet.
This kind of boardroom turnover trend is worth watching across medical technology peers as well, especially when weighing potential opportunities in 34 high quality undervalued stocks.
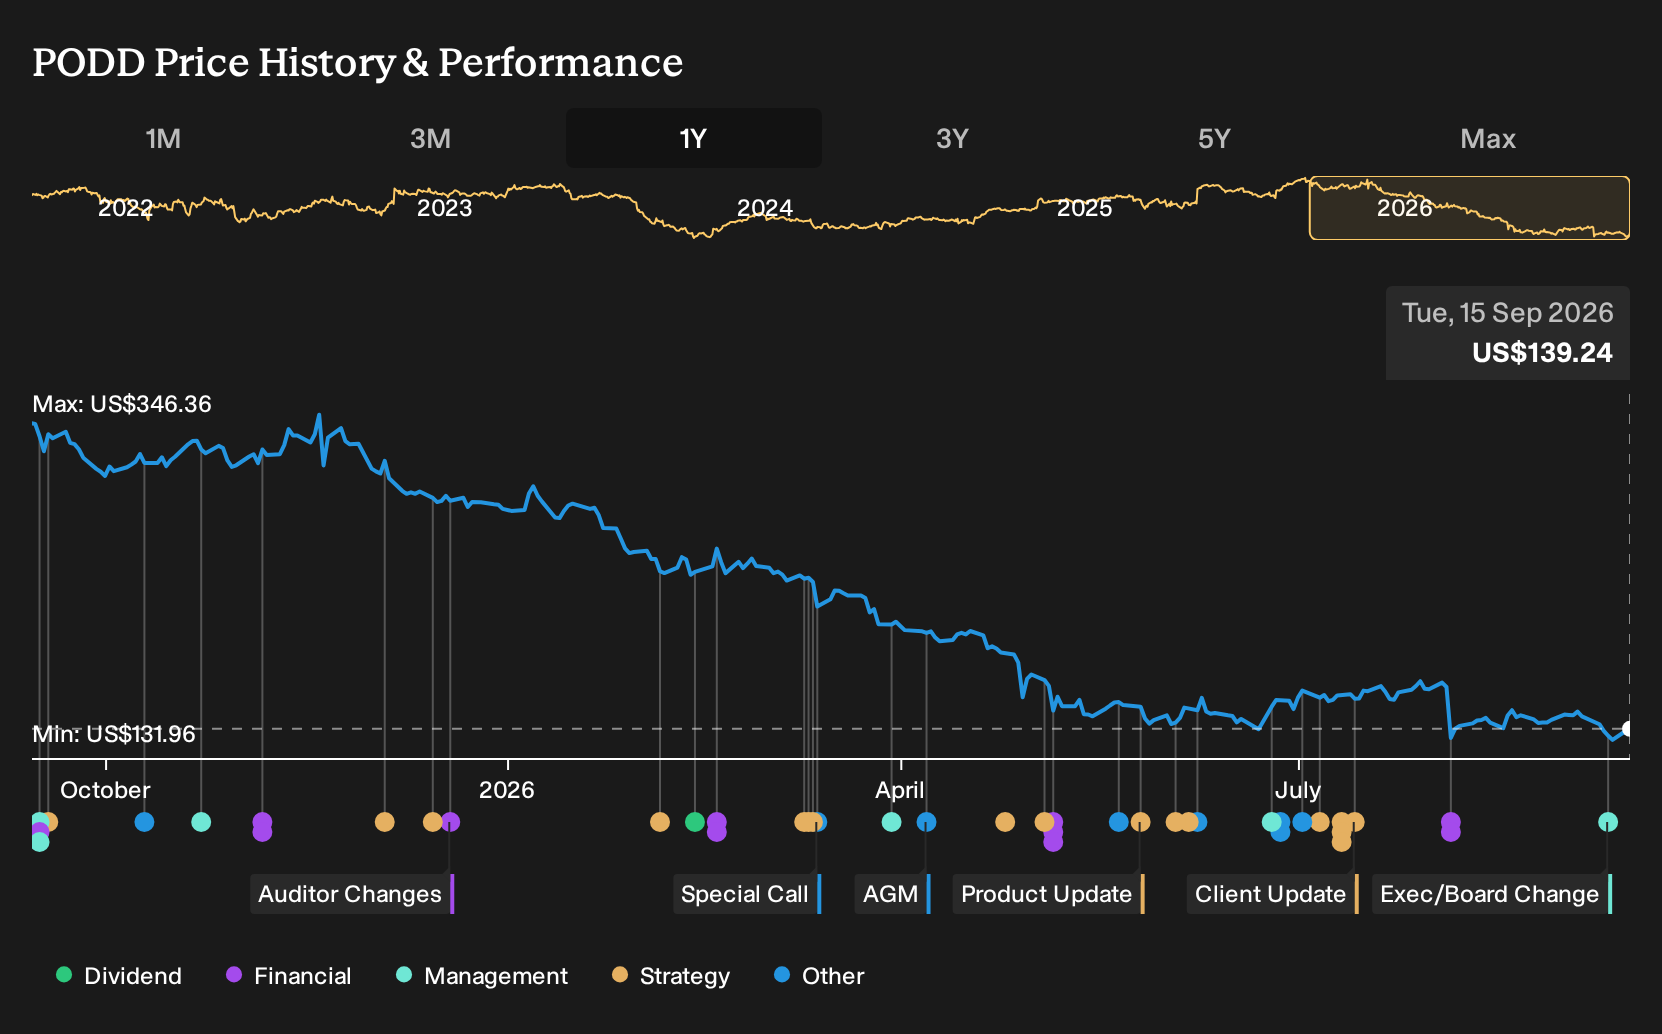
Insulet focuses on insulin delivery systems for people with insulin-dependent diabetes, so boardroom decisions feed directly into how it allocates capital to product development and global market reach. For a US$9.6b medical equipment business, board turnover shapes how that diabetes franchise could be overseen over time.
Do these Insulet exits signal a change in direction or just personal moves?
On the face of it, the board says both Timothy Scannell and Michael Minogue are leaving for personal reasons, not because of disagreements over Insulet’s operations or policies. That points more to a transition in who oversees the diabetes franchise rather than an announced shift in the Omnipod strategy or capital allocation priorities.
Does this change the Insulet Narrative on growth and risk?
The current Narrative leans heavily on expanding Omnipod 5 in type 2 diabetes and new geographies while managing the risk of reliance on one core platform. Losing a former Chair and a director with public-sector ambitions at once raises questions about how consistently the board will monitor execution on type 2 retention, manufacturing quality and international expansion that the Narrative flags as key catalysts and risks.
See how these catalysts shape Insulet's path to a $172 fair value.
What should investors watch next to see if this board news really matters?
Focus on who Insulet appoints to fill these seats and how quickly that happens. The backgrounds of incoming directors in diabetes devices, manufacturing controls or reimbursement, plus any governance updates in the next proxy statement, will indicate whether this reshuffle strengthens oversight of Omnipod growth and recall related execution.
One big Insulet question this article has not answered yet
Board changes are only part of the picture. The real puzzle is what Insulet might be worth if you focus purely on the cash the business is expected to generate, and then compare that with where the shares trade today. Find out exactly what Insulet is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com