


Cameco (TSX:CCO) Returns To The Spotlight, Is It Still 29% Undervalued?
Television attention put Cameco (TSX:CCO) back in focus after Jim Cramer highlighted the uranium producer on Mad Money and framed the business as a key nuclear power supplier with long-term delivery contracts.
Cameco has seen some heat come out of the trade recently, with the share price down 2.11% over the last session, 9.78% over the past week and 14.94% over the past three months, even though the 1-year total shareholder return sits at 15.31% and the 5-year total shareholder return is up more than 3.7 times.
Scan beyond Cameco and see how other nuclear energy infrastructure plays are shaping up with our curated list of 91 nuclear energy infrastructure stocks for this theme.
Bulls see Cameco’s pullback as a reset in a nuclear fuel heavyweight with contracts locked in for years. Bears see a crowded trade cooling off. Which case fits the current valuation setup?
Most Popular Narrative: 29% Undervalued
Cameco's most followed valuation narrative puts fair value at CA$178.28 per share against a last close of CA$126.99, so the story hinges on whether long-term uranium demand and contracts can bridge that gap.
Cameco stands to benefit from a global wave of new nuclear construction, driven by heightened government policy support, net-zero emission mandates, and growing energy security concerns. These factors are viewed as likely to accelerate demand for uranium and nuclear fuel, directly supporting higher long-term revenues.
Momentum in utility contracting is building, but current volumes are subdued. As uncovered utility uranium needs through 2045 accumulate, the eventual surge in term contracting is expected to drive material price and volume upside, improving both Cameco's revenue growth and pricing power (with likely gains to net margins).
See why 148 investors see Cameco as 29% undervalued.
Result: Fair Value of CA$178.28 (UNDERVALUED)
Still, Cameco’s story can break if new nuclear projects keep slipping, or if operational issues at assets like McArthur River and Inkai hit deliveries and costs.
Find out about the key risks to this Cameco narrative.
Another View: Cameco looks expensive on sales multiples
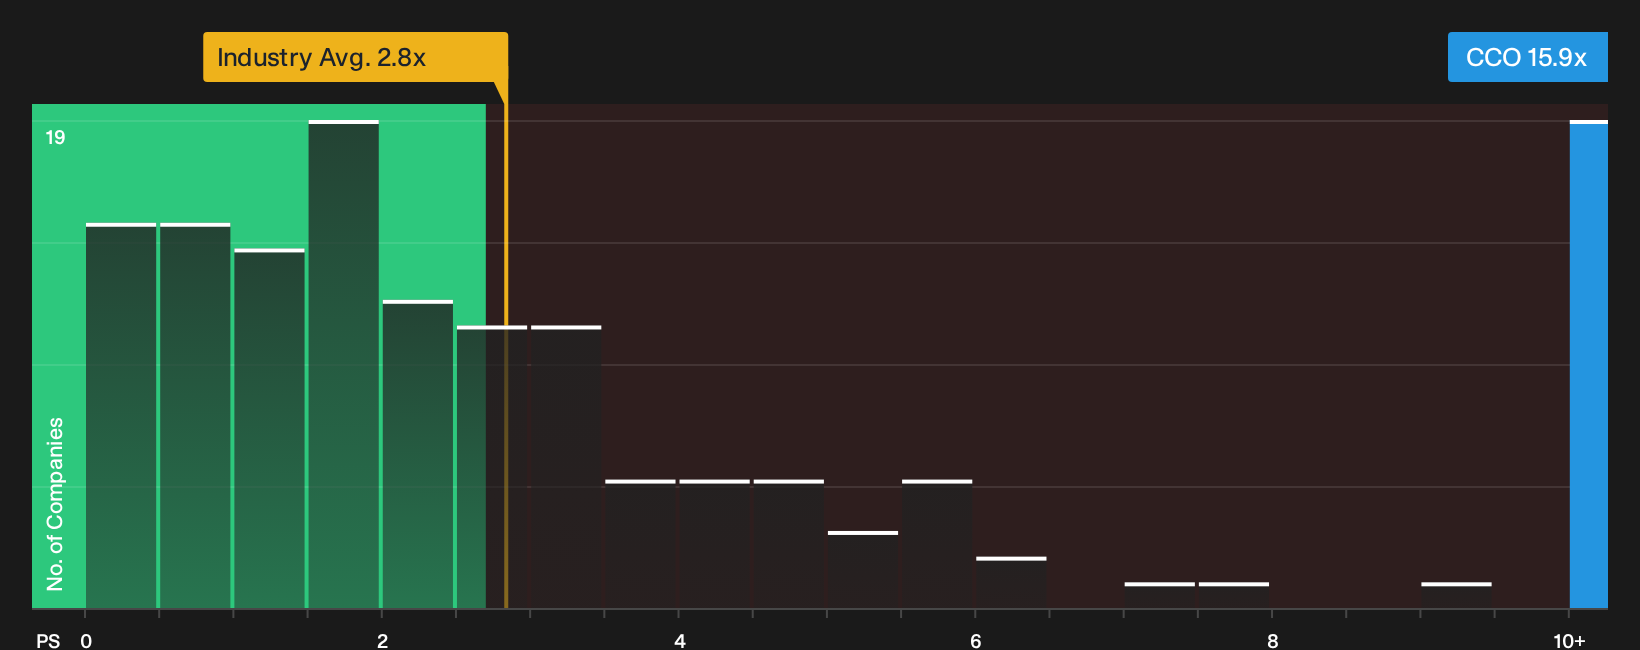
Cameco screens differently when you swap the narrative fair value for a simple P/S check. The stock trades on 15.9x sales versus 2.8x for the Canadian Oil and Gas industry, 10x for peers, and a fair ratio of 2.3x. This points to meaningful valuation risk if sentiment cools.
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Cameco after all that. If you want a firm view, move quickly, stress test the bullish and bearish cases yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Cameco?
If Cameco has you thinking harder about where to put fresh capital, do not stop here. The next opportunity you care about might already be on someone else’s radar.
- Target potentially resilient compounding by scanning companies that score well on balance sheet strength and fundamentals through our list of solid balance sheet and fundamentals (7 results).
- Hunt for quality at a reasonable price by checking a curated 3 high quality undervalued stocks that filters for strong cash flows and supportive fundamentals.
- Zero in on under-the-radar prospects with a 9 high quality undiscovered gems that highlights stocks many investors are still overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com