


How Investors May Respond To Ulta Beauty (ULTA) Analyst Upgrade
- Ulta Beauty recently presented at Barclays' 19th Annual Global Consumer Staples Conference in Boston, where President and CEO Kecia L. Steelman and CFO Christopher J. DelOrefice outlined how the retailer is handling category pressures and consumer shifts.
- Management discussions with Wells Fargo highlighted operational resilience in a tougher beauty retail backdrop, drawing attention to how Ulta Beauty is managing costs, assortment choices and demand trends relative to broader industry challenges.
- This article examines how Ulta Beauty's investment narrative is influenced by management's operational resilience message highlighted in the Wells Fargo discussions.
Ulta Beauty Investment Narrative Recap
To own Ulta Beauty, you need to believe the retailer can keep drawing shoppers into stores while growing digital channels, and do that without letting costs run ahead of sales. The Wells Fargo conversations and Barclays appearance point to a focus on assortment discipline and expense control, which supports that thesis but does not radically change it.
The near term catalyst is whether Ulta Beauty can defend margins as wage, rent and benefit costs stay elevated and Target shop in shop revenue nears its planned end. The biggest risk is that store heavy economics feel tighter if e commerce gains share faster than Ulta can adjust its cost base.
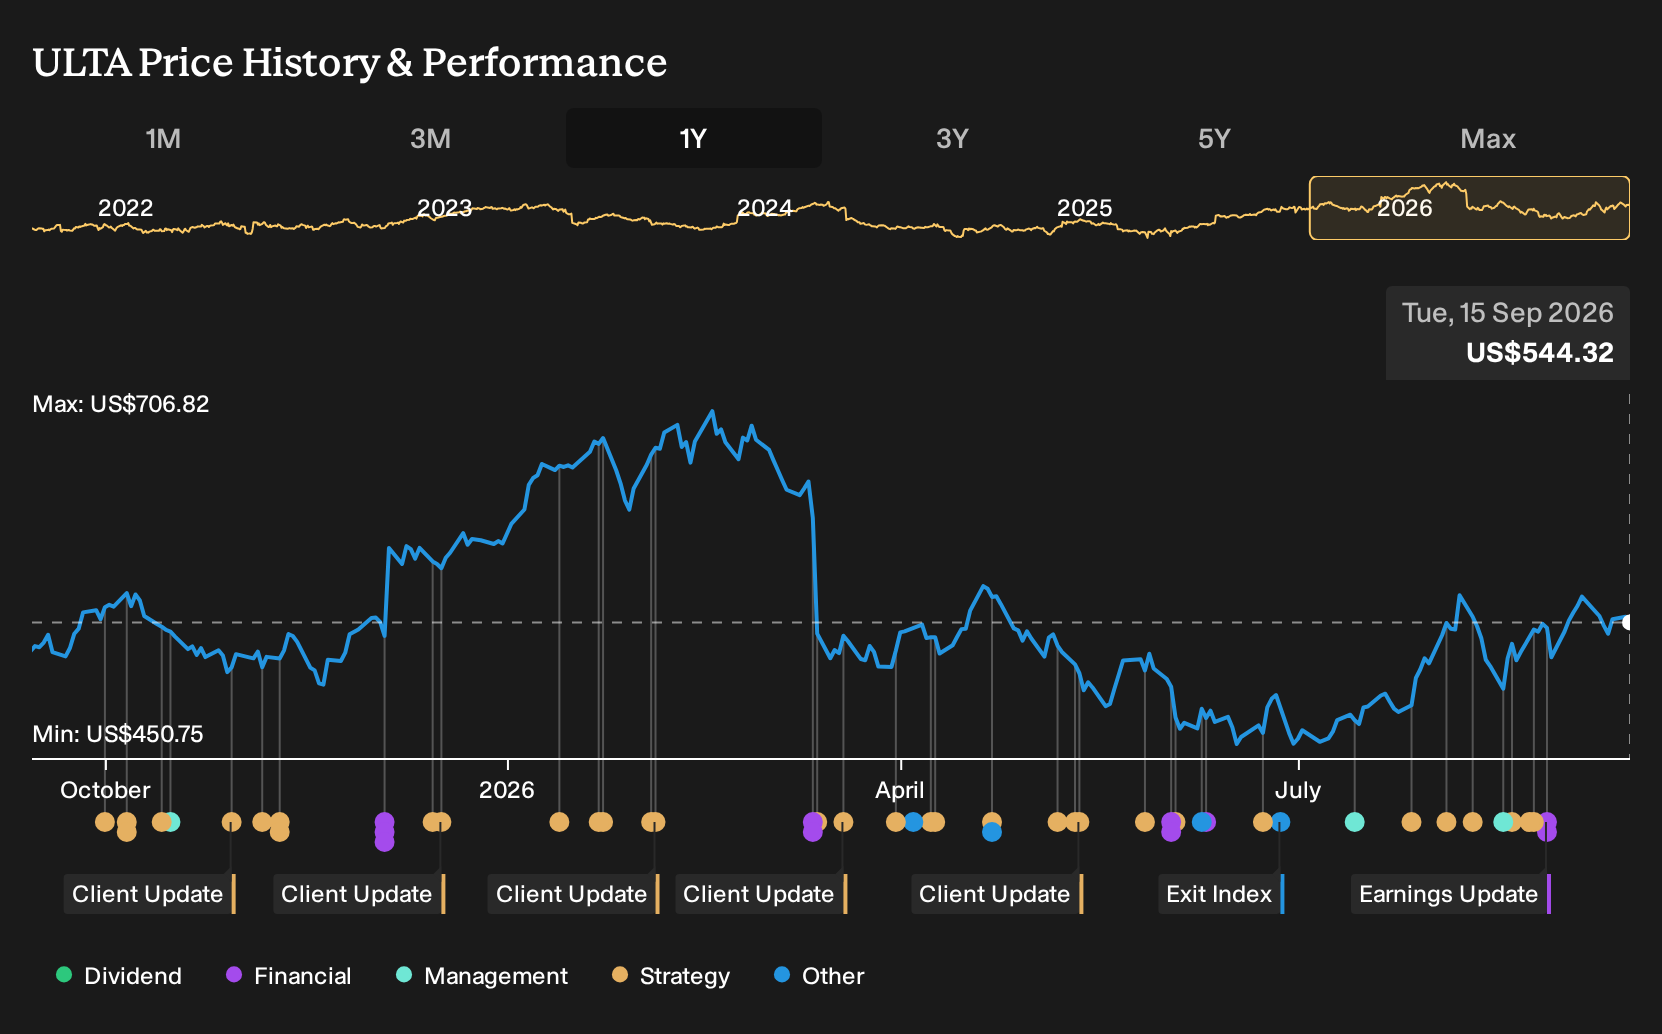
The Wells Fargo upgrade to Equal Weight after meeting with Ulta Beauty management is the announcement that lines up most directly with this story. That shift reflects a reassessment of how the retailer is handling current beauty category pressures, especially as net profit margins have already moved from 10.3% to 9.3%.
For you, the relevance is about execution. If loyalty engagement, wellness expansion and assortment refreshes can keep traffic healthy, the key watchpoint becomes whether those initiatives offset wage inflation, higher store level expenses and the future loss of Target partnership profits without eroding earnings quality.
Ulta Beauty's narrative projects US$14.9b revenue and US$1.4b earnings by 2029. This implies 5.4% yearly revenue growth and an earnings increase of about US$200m from current earnings of US$1.2b.
Uncover why Ulta Beauty's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts much more weight on e commerce competition. In that storyline, the lowest analysts were penciling in about 4.2% yearly revenue growth and US$1.3b earnings by 2029, before this Ulta Beauty conference update. That is a cooler setup than consensus, and it may shift again once this latest message is fully digested.
Explore 6 other Ulta Beauty fair value estimates, including one that suggests as much as 28% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ulta Beauty research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Ulta Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ulta Beauty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ulta Beauty?
Once you have a handle on Ulta Beauty, it can help to widen the lens and compare it with other businesses that share similar qualities like resilient cash flows, stronger balance sheets or different risk profiles. The Simply Wall St Screener lets you do that quickly by filtering for financial traits that matter to you rather than chasing headlines.
- For investors who prioritize quality at a reasonable entry point, start with a curated set of 34 high quality undervalued stocks that pair healthier fundamentals with more modest expectations baked into the price.
- If capital preservation and steadier performance matter more than excitement, narrow your search to a 11 resilient stocks with low risk scores that filter for cleaner balance sheets and fewer red flags in the financials.
- Those hunting for under-the-radar opportunities can scan a 16 high quality undiscovered gems where strong fundamentals have not yet attracted broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com