


How Earnings Beat Will Impact Azenta Stock Investors
- Azenta reported a strong Q2 in the past, with revenue coming in 8% above analyst expectations and earnings per share also ahead of forecasts, supported by demand for its biological sample management and genomic services.
- The combination of outperformance in both top line and EPS highlights how Azenta’s role in biologics and precision medicine is aligning with demand across drug development services.
- We will now look at how Azenta's better-than-expected Q2 revenue performance could reshape the broader investment narrative around the business.
Scan how Azenta's Q2 beat fits into a broader move in drug development services by reviewing our hand-picked list of solid balance sheet and fundamentals (22 results).
Azenta Investment Narrative Recap
To hold Azenta, investors need to buy into a long runway for outsourced sample management and multiomics services as personalized medicine and genetic research expand. The recent Q2 beat supports that view in the near term by showing that demand is present for its biobanking and genomic offerings. The key short term catalyst remains execution on these recurring services and automation solutions rather than a single one off quarter.
The biggest near term risk still appears operational. Pharma and biotech customers are dealing with budget resets and internal reshuffles, which can delay higher margin equipment and certain sequencing projects. Q2 strength does not fully remove the possibility of uneven orders or pressure in areas where Gene Synthesis and Sanger Sequencing are already softer.
There are no fresh company announcements directly tied to this Q2 release, which makes the operational print itself the clearest update to work with. That puts the focus on whether Azenta converts current demand in next generation sequencing and sample storage into steadier contract wins and better utilization across its installed base.
For catalysts, one important angle is how past investments in automation, cost structure and sales coverage interact with these results. If recent spending on R&D, sales capacity and biorepository infrastructure results in smoother order flow and more long term service agreements, that would matter more than the single quarter beat. Investors can monitor how consistently that dynamic appears in future reports.
Azenta's current analyst narrative points to revenues of $692.7 million and earnings of $29.5 million by 2029, based on assumed yearly top line growth of 4.1% and an earnings shift from a loss of $112.1 million today to positive profits. This implies an earnings increase of about $141.6 million over that period.
Uncover how Azenta's fair value indicates a 7% potential upside to its current price that could close more quickly than many investors expect.
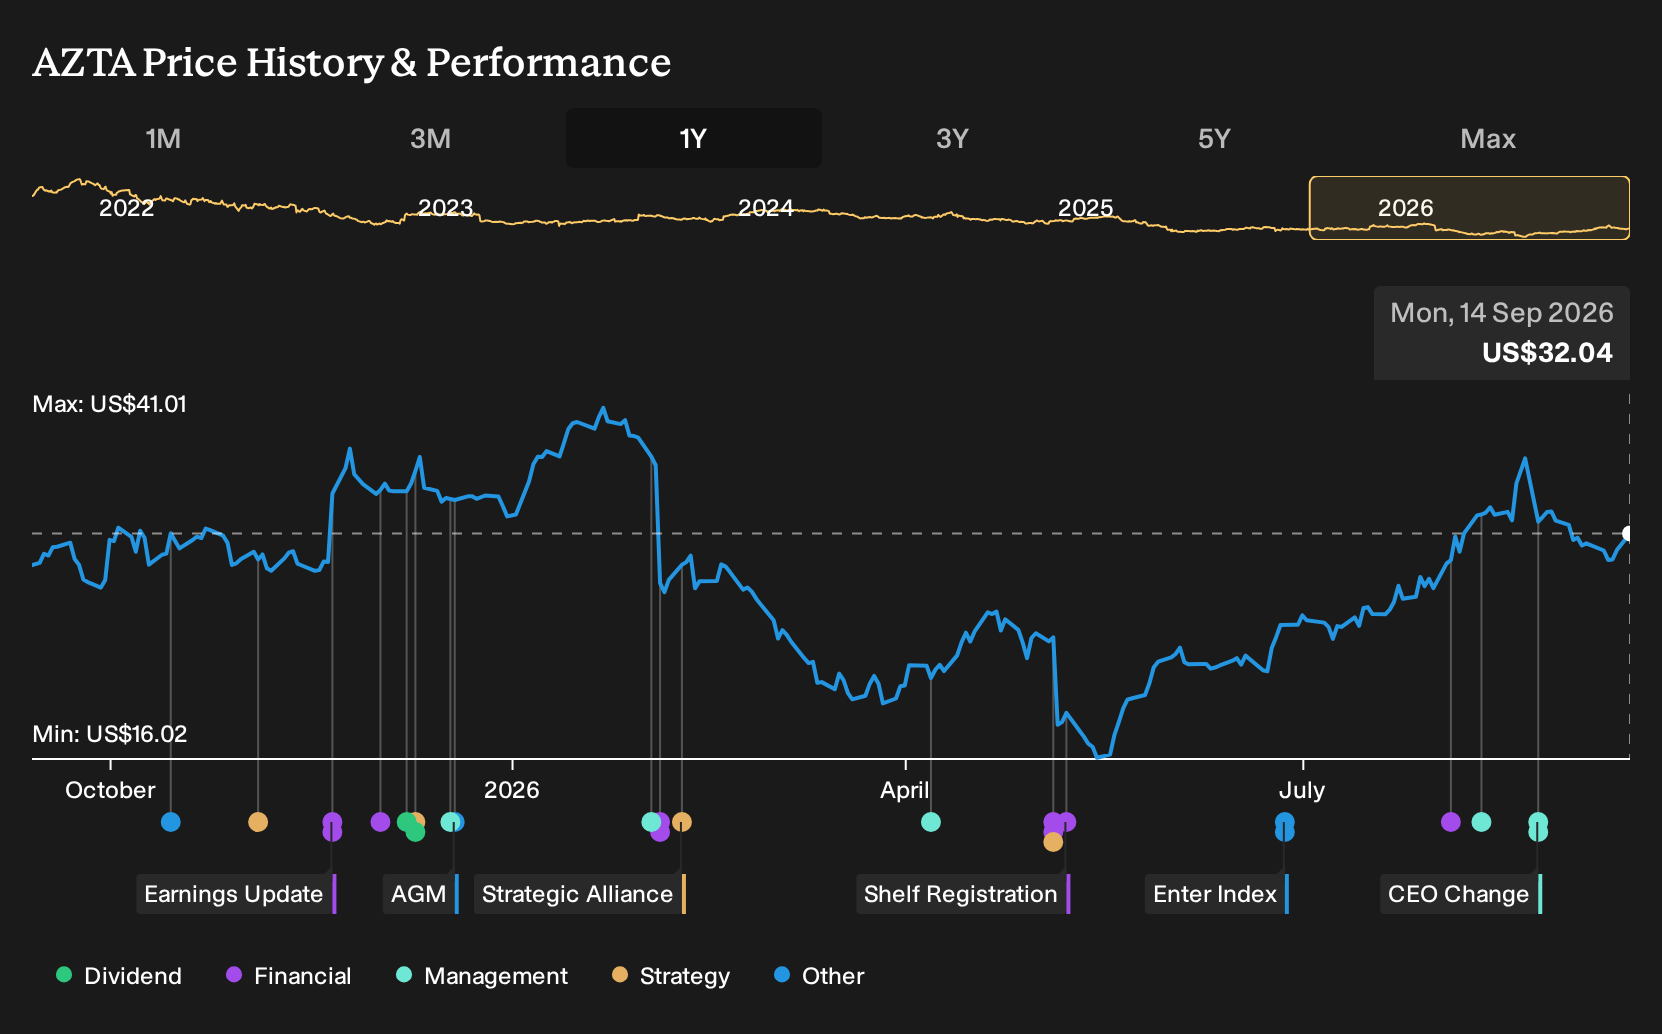
Exploring Other Perspectives
For Azenta, the more cautious analysts focus on margin pressure as the key risk, even with this Q2 beat in hand. Before the news, the bearish group was modeling about US$696.1 million of revenue and only US$24.6 million of earnings by 2029. That is meaningfully below the most optimistic US$32.7 million view. You can use this spread to stress test your own expectations and decide which camp feels closer to how you see the business evolving once Q2 is fully baked into forecasts.
Explore another Azenta fair value estimate, including one that suggests as much as 32% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Azenta research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Azenta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Azenta's overall financial health at a glance.
Looking For More Investment Ideas Beyond Azenta?
If Azenta has sharpened your thinking about what to look for in a business, use that framework across the wider market with the Simply Wall St screener. You can filter for balance sheet strength, income potential, or mispriced quality and quickly build a watchlist that matches your own risk and return preferences.
- If capital preservation sits high on your list, start with a 11 resilient stocks with low risk scores that already screen well on resilience and downside protection.
- If value is your focus, look through a 34 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them.
- If you like backing underappreciated stories, scan a 16 high quality undiscovered gems that pair quality metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com