


How Investors Are Reacting To DocuSign (DOCU) Raised Guidance
- DocuSign reported second quarter sales of US$875.75 million and net income of US$77.72 million, raised full year revenue guidance, and continued to invest in AI powered Intelligent Agreement Management partnerships and integrations across platforms and clients.
- The rollout of DocuSign's Model Context Protocol Server and real world IAM deployments, alongside a completed multi year buyback of 40,171,002 shares, point to a business focused on AI centric product usage and disciplined capital allocation.
- We will now look at how DocuSign's stronger guidance and AI driven IAM expansion could reshape the existing investment narrative.
Scan how DocuSign's AI driven agreement push compares with other platforms by reviewing our hand picked list of 59 AI infrastructure stocks.
DocuSign Investment Narrative Recap
To own DocuSign, you effectively need to believe that AI powered Intelligent Agreement Management can offset a maturing eSignature market and keep usage expanding across enterprises, partners, and new verticals. The latest quarter showed higher revenue and net income, raised full year guidance, and a completed multi year buyback, which together keep the near term focus on execution rather than a reset of the story.
The key short term swing factor remains clear evidence that IAM adoption can scale without pressuring margins that are already facing hosting and compensation headwinds. The biggest risk still sits in competitive and pricing pressure as rivals bring AI agents into contract workflows, which could cap upside from DocuSign’s expanded ecosystem if customers see offerings as interchangeable.
The MCP Server rollout appears to be the news that matters most for that thesis. Opening DocuSign’s agreement intelligence to agents inside Claude, ChatGPT, Gemini, Copilot, Slack, Salesforce, and others means contract creation, analysis, and approvals can sit inside existing workflows instead of a separate app. This matters in particular for usage frequency and stickiness.
The same announcement also highlights operational and execution risks. Scaling MCP to global, multi region, multilingual deployments with admin controls is complex, and any reliability, security, or integration issues could slow enterprise adoption and give competitors room to argue that their AI stacks are safer or easier. For investors watching catalysts, real usage data from MCP and IAM integrations will likely matter more than short term guidance tweaks.
DocuSign's current analyst script points to revenues of US$4.0b and earnings of US$482.3 million by 2029, based on a projected 7.5% yearly revenue growth rate and an earnings increase of about US$173.2 million from US$309.1 million today.
Uncover why DocuSign's fair value indicates a 16% potential downside to its current price, which leaves little room for error.
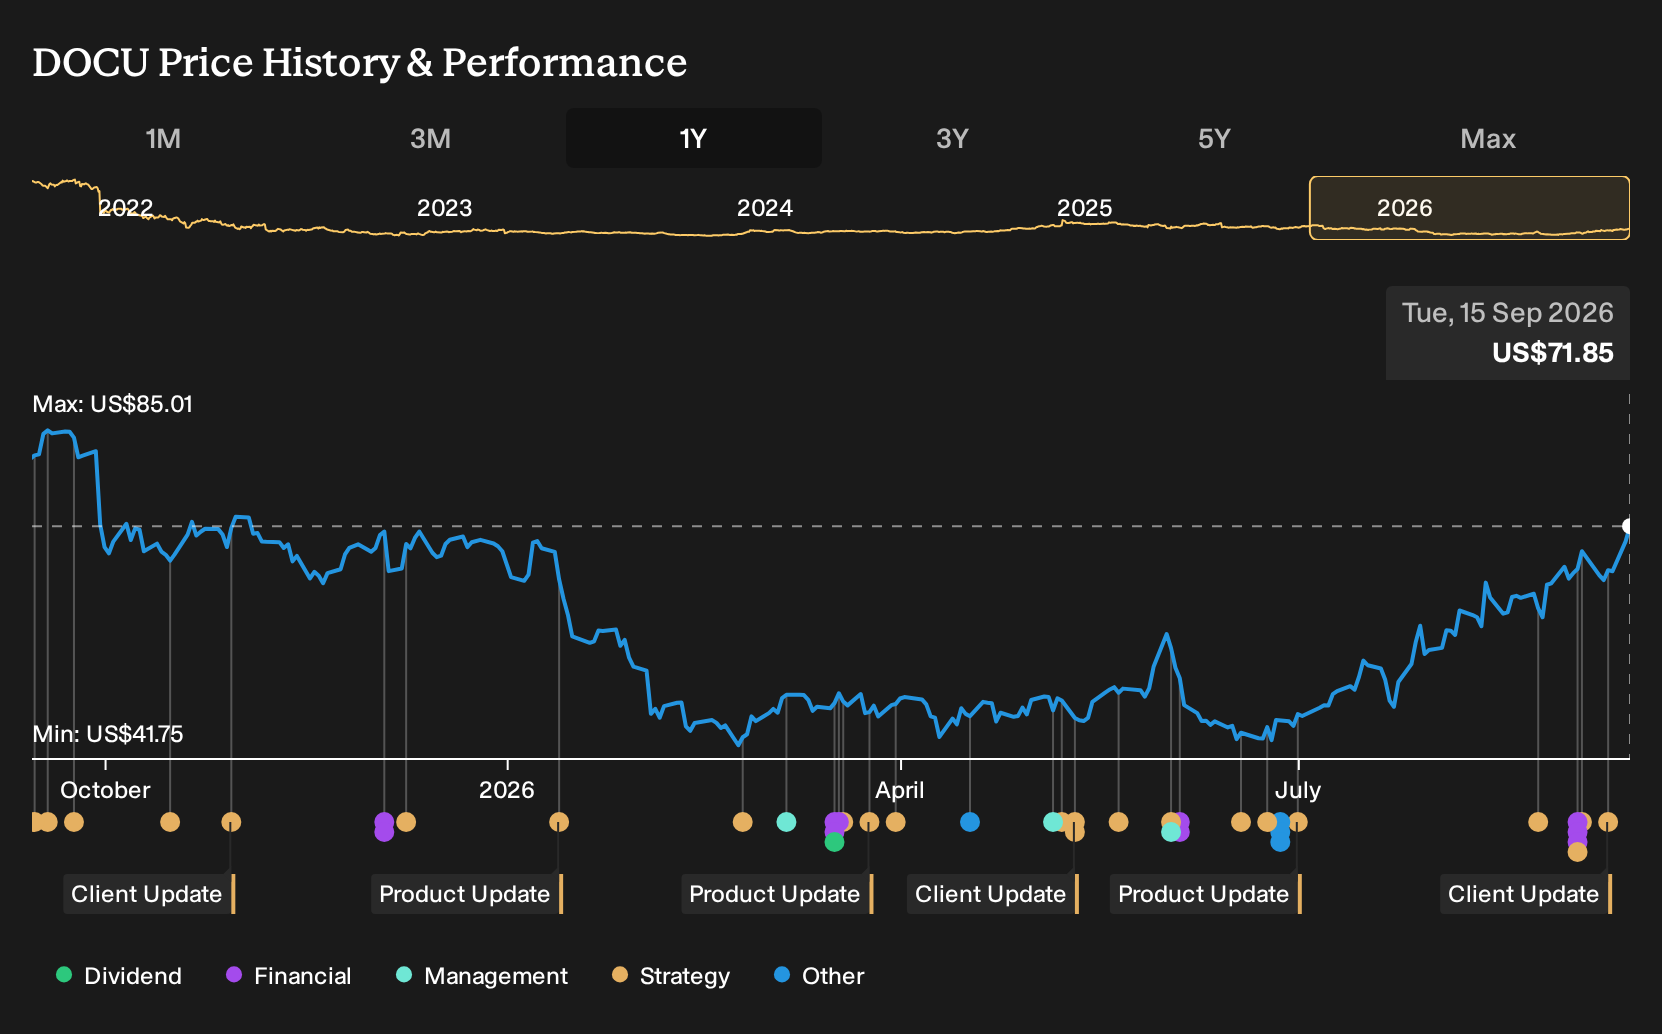
Exploring Other Perspectives
One bullish twist on DocuSign focuses on IAM turning into premium pricing power rather than just usage growth. Those optimistic analysts were already penciling in revenue of US$4.3b and earnings of US$675.9 million by 2029 before this Underrated Golf partnership and MCP rollout, which might push that upbeat story even further if adoption broadens.
Explore 7 other DocuSign fair value estimates, including one that suggests as much as 120% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your DocuSign research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DocuSign. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DocuSign's overall financial health at a glance.
Looking For More Ideas Beyond DocuSign?
If DocuSign has sharpened your thinking about AI, cash flows, and risk, you can broaden that lens across the wider market using the Simply Wall St Screener. You can filter for balance sheet strength, potential mispricing, or dependable income and quickly spot opportunities that fit your own approach.
- If resilience matters most to you, focus on businesses with steadier profiles using a set of 11 resilient stocks with low risk scores that may help cushion tougher periods.
- For investors who care about quality and valuation together, scan a 34 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them.
- Or, if you want to back sturdier financial footing, start with a list of solid balance sheet and fundamentals (22 results) that filters for companies with healthier leverage and liquidity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com