


Will Lower Earnings Forecast Change Riot Platforms Stock Narrative
- Riot Platforms recently faced a weaker earnings outlook, with analysts projecting earnings per share of a loss of US$0.33 for the upcoming quarter compared with the same period last year.
- This downward shift in projected profitability signals pressure on Riot Platforms' core Bitcoin mining economics and cost structure, with analyst rankings reflecting that concern.
- We will now look at how Riot Platforms' long term investment narrative compares with this weaker near term earnings picture.
Broaden your watchlist beyond Riot Platforms by scanning our hand picked 18 cryptocurrency and blockchain stocks, which captures the same Bitcoin and blockchain theme that is driving sentiment around this stock.
Riot Platforms Investment Narrative Recap
For Riot Platforms, the core belief is that large scale Bitcoin mining and data center infrastructure can one day justify the current investment in power and hardware. As a shareholder, you are effectively tying your capital to Bitcoin price sensitivity, mining efficiency and the ability to fill data center capacity with paying tenants over time.
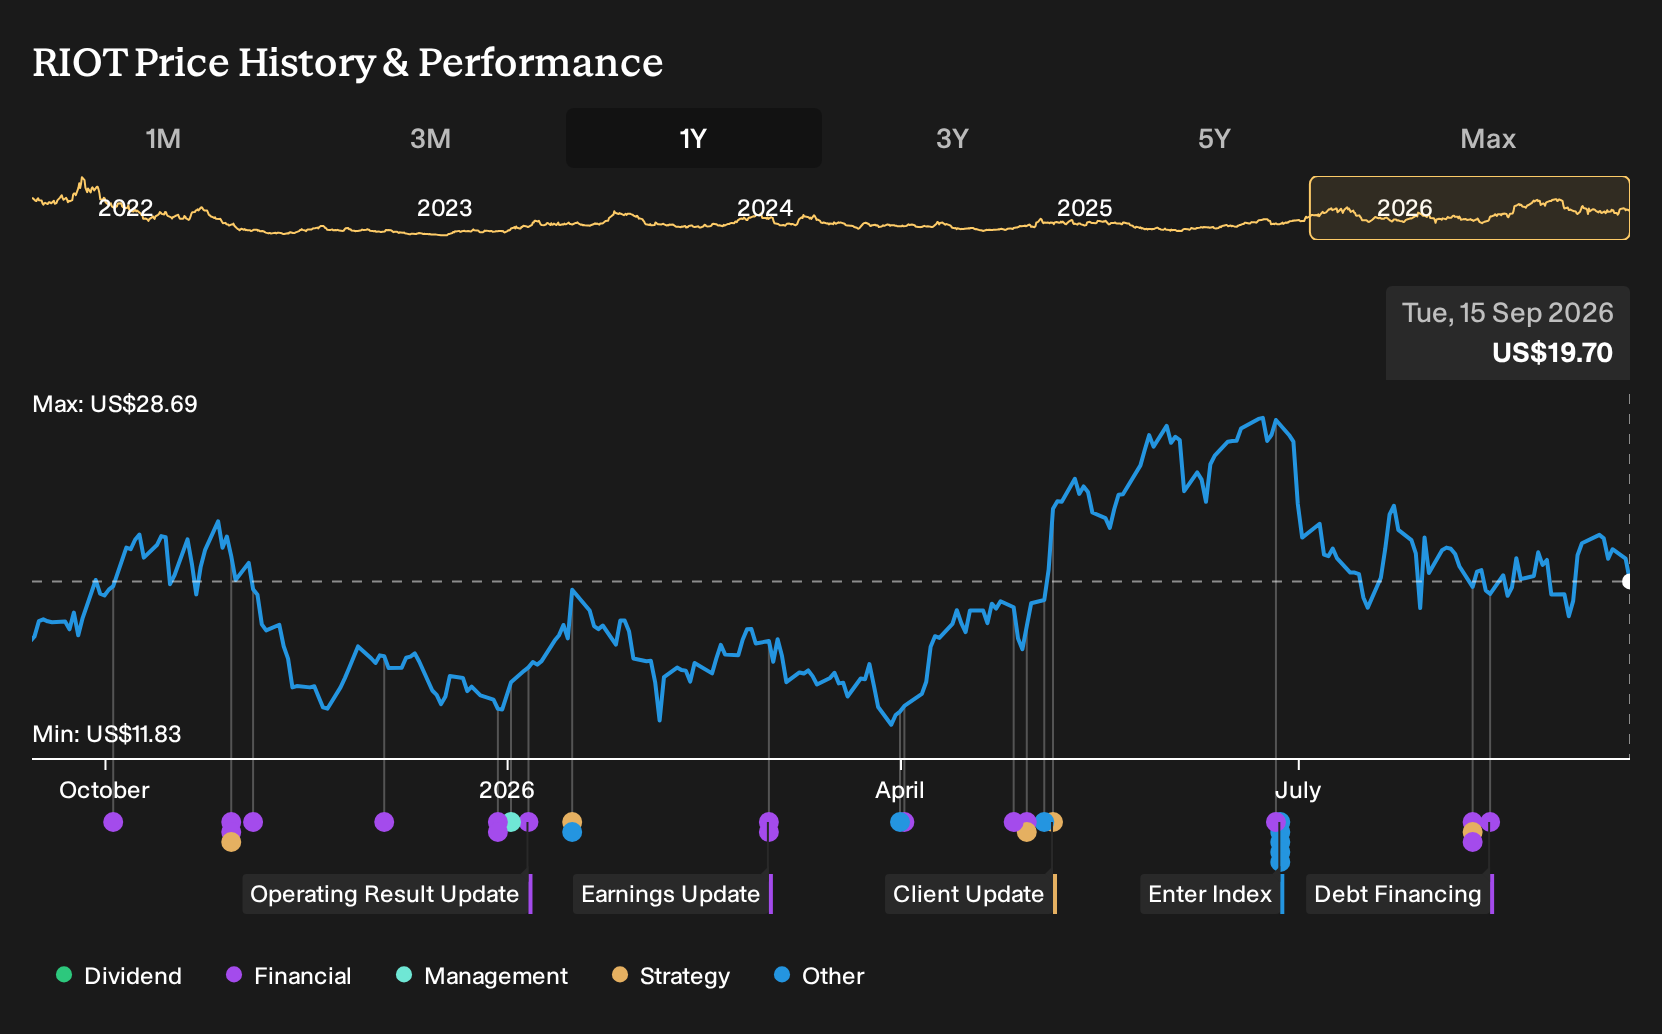
The projected loss of US$0.33 per share and recent share price pullback highlight that the near term earnings hit is already visible. This weak quarter mainly stresses Riot Platforms’ exposure to Bitcoin economics and capital intensity, while the biggest risk remains underutilised power and data center capacity if demand or tenant sign ups disappoint.
The clearest short term reference point for this latest earnings outlook is the update that earnings per share are expected to be a loss of US$0.33 for the upcoming quarter. That figure directly links to the recent share price decline of 2.42%, since it underlines pressure on Riot Platforms’ mining profitability and cost base.
For you as an investor, that projected loss feeds into the same operational questions that were already on the table: Can Riot Platforms ramp efficient mining and data center usage fast enough to support its heavy infrastructure spend, and can it manage cash runway and capital needs without putting excessive strain on existing shareholders if conditions stay tough?
Riot Platforms' narrative projects US$1.8 billion in revenue and US$209.9 million in earnings by 2029. This projection assumes 38.5% yearly revenue growth and an increase in earnings of about US$1.5 billion from the current earnings figure, which is a loss of US$1.3 billion.
Uncover why Riot Platforms' fair value indicates a 64% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Riot Platforms puts execution risk at the data center pivot front and center. The most pessimistic analysts were pencilling in revenue of about US$952.7 million and earnings of roughly US$109.0 million by 2029, far below consensus. That group already leaned cautious before this earnings update, so their narrative may shift even further.
Explore 3 other Riot Platforms fair value estimates, including one that suggests it could be worth just $22.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Riot Platforms research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Riot Platforms. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Riot Platforms' overall financial health at a glance.
Looking For More Investment Ideas Beyond Riot Platforms?
If the Riot Platforms story has you thinking about position sizing and portfolio balance, it can help to line it up against other opportunities with very different risk and income profiles.
- For investors who want income to play a bigger role in total return, scan a set of higher yielding opportunities through 6 dividend fortresses to see which ones match your payout preferences.
- If capital protection ranks higher on your list, stress test your portfolio against a group of steadier businesses by reviewing the 11 resilient stocks with low risk scores that clear tighter risk filters.
- Those hunting for future leaders that are not yet widely followed can broaden their opportunity set by checking a curated 16 high quality undiscovered gems that already show stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com