


Should Earnings Beat Require Action From Samsara (IOT) Investors?
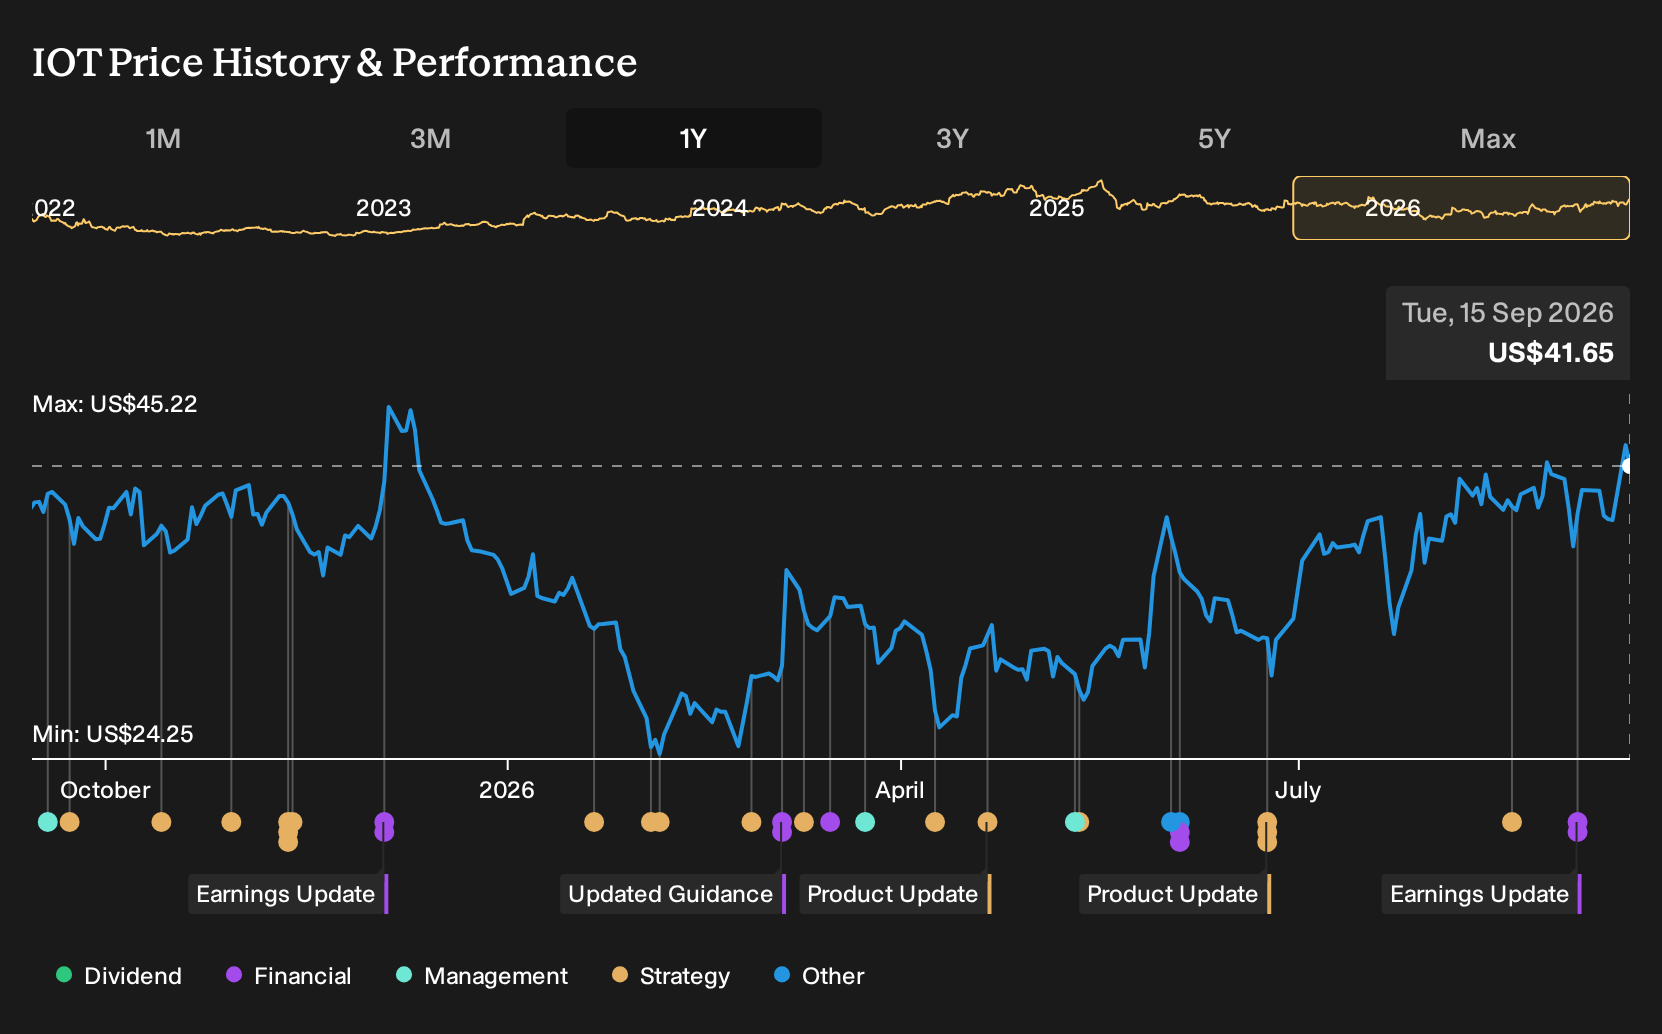
- Samsara reported second quarter 2026 sales of US$508.44 million and net income of US$16.24 million, turning prior year losses into earnings, and issued guidance targeting GAAP profitability with projected fiscal 2027 revenue of about US$2.043 billion to US$2.047 billion.
- The shift from losses to earnings, along with revenue guidance framed around continued GAAP profitability, indicates that Samsara's connected operations model is beginning to scale in a way that could reshape how investors view its balance between growth spending and cash generation.
- It remains to be seen how Samsara's new guidance for GAAP profitability may influence the existing investment narrative around recurring revenue expansion.
Samsara Investment Narrative Recap
To be comfortable owning Samsara, you need to believe its connected operations platform can keep converting physical world data into durable subscription economics and steady profitability. The recent Q2 results, with US$508.44 million in sales and US$16.24 million in net income, support that thesis but do not remove execution risk around larger enterprise deals and international rollout.
The most important near term catalyst is Samsara proving it can stay GAAP profitable while targeting fiscal 2027 revenue of about US$2.043 billion to US$2.047 billion. The biggest current risk is that long, often multi year sales cycles and slower adopters in sectors like construction and the public sector soften that trajectory or make revenue lumpier than investors expect.
The guidance issued alongside Q2, which points to GAAP profitable diluted EPS for both the third quarter and the full 2027 fiscal year, is the key announcement to focus on. It puts earnings quality in the spotlight, especially given the prior impact of one off items and the shift from earlier losses to current profitability.
For you as a shareholder, the catalyst is straightforward. Management has set a clear revenue range for fiscal 2027 and tied it to ongoing GAAP profitability. Execution against that bar, while ramping AI driven products and expanding abroad, will likely shape how much confidence investors place in Samsara's recurring revenue story versus concerns about valuation, insider selling and complex enterprise sales cycles.
Samsara's analyst narrative points to revenue of US$3.0b and earnings of US$304.4 million by 2029, built on forecast yearly top line expansion of 19.7% and an earnings increase of about 5.3x from US$57.5 million today.
Discover how Samsara's fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One big alternate catalyst for Samsara focuses on AI driven workflows. The most optimistic analysts were already penciling in revenue of about US$3.1b and earnings near US$464.9 million by 2029, assuming faster adoption and higher margins. Those projections pre date this earnings beat and the Goldman Sachs conference, so you may see those narratives shift meaningfully.
Explore 7 other Samsara fair value estimates, including one that suggests as much as 56% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Samsara research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Samsara. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Samsara's overall financial health at a glance.
Looking For More Ideas Beyond Samsara?
If Samsara has sharpened your thinking about recurring revenue and profitability, it can be useful to compare it with other businesses that fit different risk and balance sheet profiles using the Simply Wall St Screener.
- For investors who put stability and financial resilience first, a 11 resilient stocks with low risk scores can be a practical way to surface candidates with more measured risk scores.
- If capital strength and cleaner balance sheets matter most to you, start with a list of solid balance sheet and fundamentals (22 results) that focuses on companies with stronger fundamentals backing their operations.
- When you want to widen the radar to less crowded opportunities, use a 16 high quality undiscovered gems that highlights quality businesses the market may not be paying much attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com