


Is Innodata (INOD) Priced For Perfection After Its Massive Run?
Innodata has delivered a very large share price gain over the past three years, yet recent weakness leaves a straightforward question for investors. Is the current US$54.37 price still aligned with what the business is earning today and what those earnings might reasonably support over time?
- Over the past three years, Innodata has returned a very large multiple on the share price, which puts extra pressure on its earnings to justify where the stock now trades.
- The appointment of Admiral Michael S. Rogers to the board signals a deeper push into AI and cybersecurity work with Federal clients, which can influence how investors think about the durability and potential growth of Innodata's profit base.
- The analysts covering Innodata have run their own numbers. See what analysts think Innodata's shares could be worth.
The issue now is whether Innodata's current earnings and what investors infer about their future path make the recent share price and its swings look sensible.
If you want to stress test the same earnings question you are asking of Innodata against a wider AI focused universe, take a look at 32 AI small caps.
Has Innodata Run Too Far on Earnings?
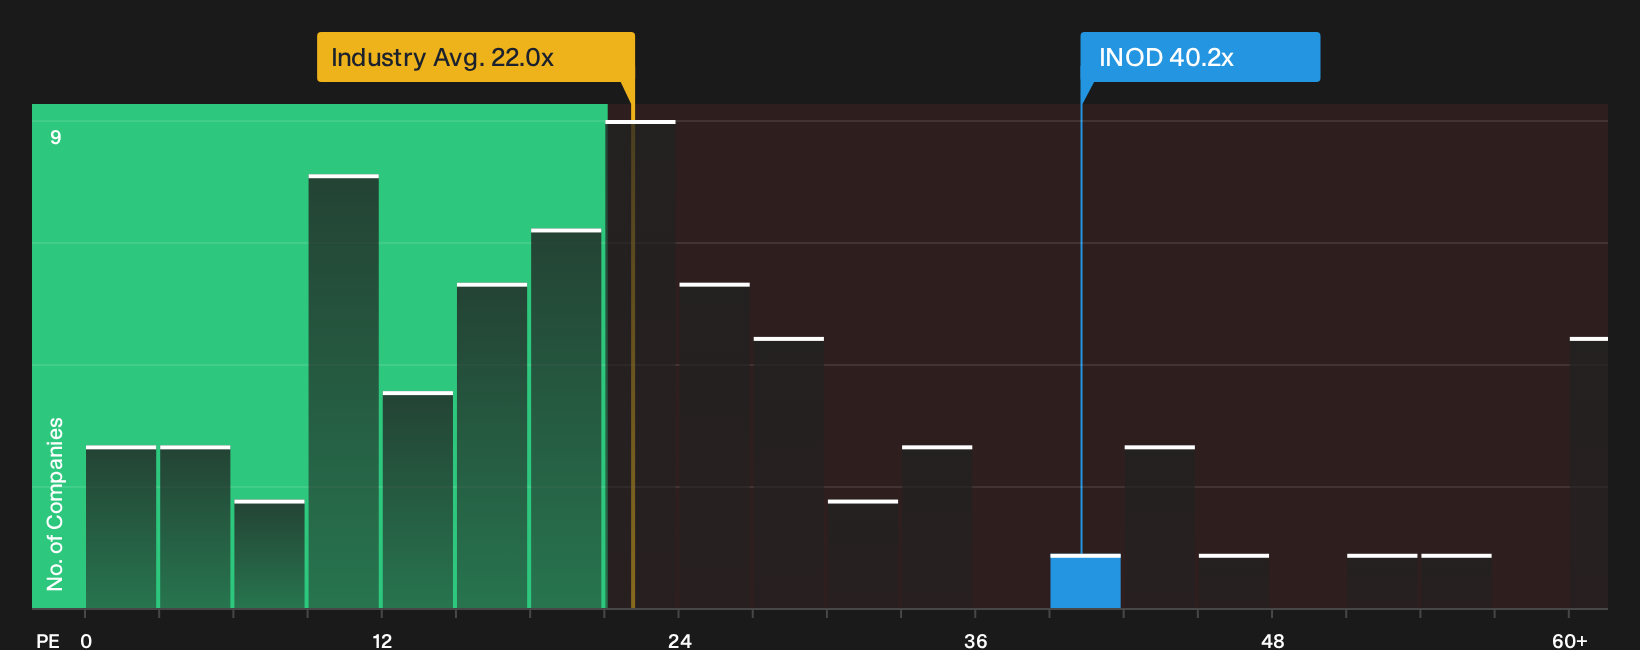
For a business like Innodata that investors watch closely on earnings quality, the P/E ratio is a useful yardstick. The stock currently trades on a P/E of about 40.2x, which is materially higher than the Professional Services industry average of roughly 22.0x and above the peer group on about 19.9x. That puts a clear premium on the shares compared with many other listed service providers.
The tailored fair-value multiple implied by the model sits below this level, so the present 40.2x P/E screens as overvalued on that framework. Admiral Rogers joining the board may help investors frame a bigger long term AI and cybersecurity opportunity. However, the valuation already assumes stronger economics than those implied by the fair multiple and sector benchmarks. Anyone considering Innodata needs to judge whether the earnings profile and contract pipeline are robust enough to support this premium. Explore the numbers behind Innodata's P/E valuation.
The Innodata Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Innodata pick up where the valuation puzzle leaves off by spelling out which combinations of growth, margins and earnings would need to hold for the stock to look materially cheaper or richer than today’s price on the screen. Each narrative ties a fair value to a particular view of Innodata's potential catalysts and key risks, so you can track over time which version of events seems closest to reality on the Community page.
One of the top community narratives on Innodata: 56% undervalued
"Expanding demand for advanced AI solutions and closer integration with clients positions Innodata for premium pricing, stable revenue, and improved margins..."
Discover why this Narrative puts Innodata at 56% undervalued.
One more Innodata angle worth checking before you move on
The people setting Innodata’s priorities and the way they are rewarded can either reinforce the earnings story or pull it in a different direction. That is a separate thread worth pulling. See who runs Innodata and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com