


Does Earnings Beat Change The Bull Case For Centene (CNC)?
- Centene recently reported quarterly results with earnings per share of $2.51 versus a consensus estimate of $0.89, and revenue above expectations by 12.73%. The company also presented at the Deutsche Bank 2026 Healthcare Summit in New York on 16 September 2026.
- The combination of stronger than forecast earnings, revenue outperformance, and a growth profile supported by favorable value metrics points to execution that is currently running ahead of previously modeled cost, demand, and pricing assumptions in Centene's core health plan operations.
- We will now assess how Centene's substantial earnings beat could reshape its investment narrative around Medicaid, Medicare Advantage, and commercial growth.
Scan how Centene's move and earnings surprise compare with other health insurers showing strong momentum and value traits through our hand-picked 11 resilient stocks with low risk scores
Centene Investment Narrative Recap
To own Centene, you need to believe the core Medicaid, Medicare, and Commercial platforms can steadily improve economics as rates, acuity, and operating efficiency line up more cleanly. The recent earnings surprise points to operations that are currently tracking better than earlier cost and utilization concerns implied, especially around medical expense volatility.
The key short term catalyst is whether Medicaid margin recovery and Marketplace retention hold up as contracts reset and rate discussions progress. The biggest near term risk remains policy and pricing friction, including Medicaid rate adequacy and potential pressure on Marketplace tax credits. These factors could quickly tighten margins despite the current operational momentum.
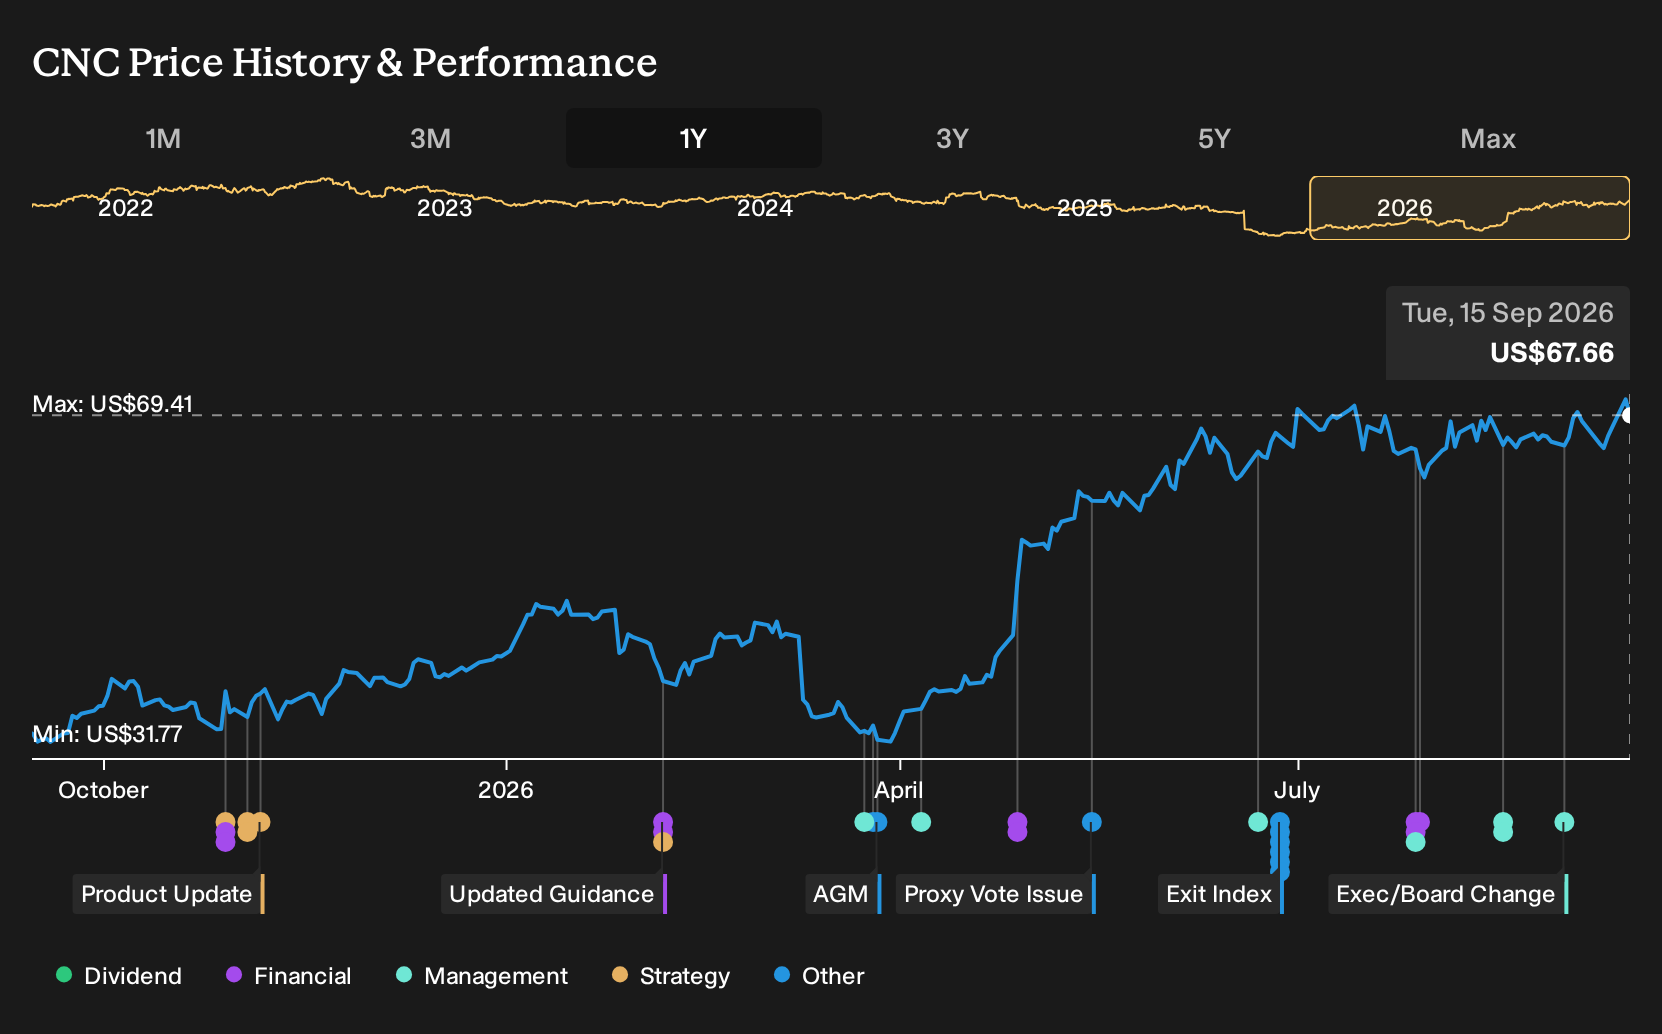
The recent 52 week high and strong year to date share performance sit on top of that single earnings print and Centene’s record of beating expectations in prior quarters. That move makes the operating trajectory and capital discipline much more important. Any stumble on medical cost trends or pricing could have a sharper impact on sentiment at these levels.
The Zacks Rank commentary, while only one external signal, aligns with the idea that execution in Medicaid, Medicare Advantage, and Commercial is the core story to watch rather than short term price moves alone. For you as an investor, the focus stays on whether those segments can support the expected margin recovery while policy risk and specialty drug costs remain active pressure points.
Centene's latest analyst setup points to revenue of $205.6b and earnings of $3.2b by 2029, based on expected yearly revenue growth of 4.5% and an earnings change of $8.3b, from a loss of $5.1b today to the projected profit base.
Uncover why Centene's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One optimistic twist focuses on Medicaid rate resets. Before this earnings surprise and the Deutsche Bank summit appearance, the most bullish analysts were modeling faster recovery, with revenue reaching about US$213.9b and earnings of roughly US$4.4b by 2029. That is far above the consensus US$205.6b and US$3.2b, and it shows how widely views on Centene can differ. Use this quarter as a prompt to compare those narratives and decide which version of the story you find more convincing.
Explore 5 other Centene fair value estimates, including one that indicates up to 178% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Centene research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Centene. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centene's overall financial health at a glance.
Looking for more Centene style investment ideas?
If Centene's setup has sharpened your interest in quality at the right price, it can help to widen the lens and scan other businesses that share similar financial traits using the Simply Wall St Screener.
- For investors who care most about valuation support and solid fundamentals, review the 34 high quality undervalued stocks that line up strong balance sheets with attractive pricing.
- If capital preservation sits high on your priority list, filter for companies that show resilient financial profiles using the 11 resilient stocks with low risk scores.
- Those searching for income ideas can focus on payout strength and durability by screening for 6 dividend fortresses that combine higher yields with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com