


Curtiss Wright (CW) Could Be 28% Below Fair Value After Embedded Systems Outlook
Curtiss-Wright (CW) is back on investor radar after fresh coverage highlighted its role in ruggedized embedded systems, a segment tied closely to defense, aerospace, and industrial automation demand.
Curtiss-Wright’s share price has pulled back sharply, with a 30-day share price return of down 19.5% and a 90-day move of down 27.6%, even as recent dividend affirmation and investor conference appearances keep the story in focus.
That short-term slide contrasts with a 1-year total shareholder return of 9.9% and a very large 5-year total shareholder return of about 3.8x. This signals that long-term holders have still seen substantial value creation despite fading near-term momentum.
Look beyond Curtiss-Wright and focus on defense and industrial companies with comparable embedded systems exposure using our curated list of 38 power grid technology and infrastructure stocks
Bulls see a quality defense electronics player on sale after a sharp pullback. Bears see a premium multiple at risk. Which side does Curtiss-Wright’s current valuation actually support next?
Most Popular Narrative: 28% Undervalued
Curtiss-Wright’s most followed valuation view anchors on a fair value of $786.29 against a last close of $562.85, which leaves a sizable modeled gap that the recent share price slide has only widened.
Record backlog growth (+12% YTD to $3.8B), strong book-to-bill ratios (1.2x in A&D), and a healthy order pipeline in both defense and nuclear align with management's confidence in posting 9 to 10% sales growth, 16 to 19% EPS growth, and over 100 bps of margin expansion in 2025, signaling undervaluation if current pricing underappreciates this forward visibility and operational leverage.
See why 14 investors see Curtiss-Wright as 28% undervalued.
Result: Fair Value of $786.29 (UNDERVALUED)
Still, that bullish Curtiss-Wright script frays quickly if large defense or nuclear contracts are delayed, or if customers pivot harder toward software-heavy solutions.
Find out about the key risks to this Curtiss-Wright narrative.
Another View: Curtiss-Wright Through A Cash Flow Lens
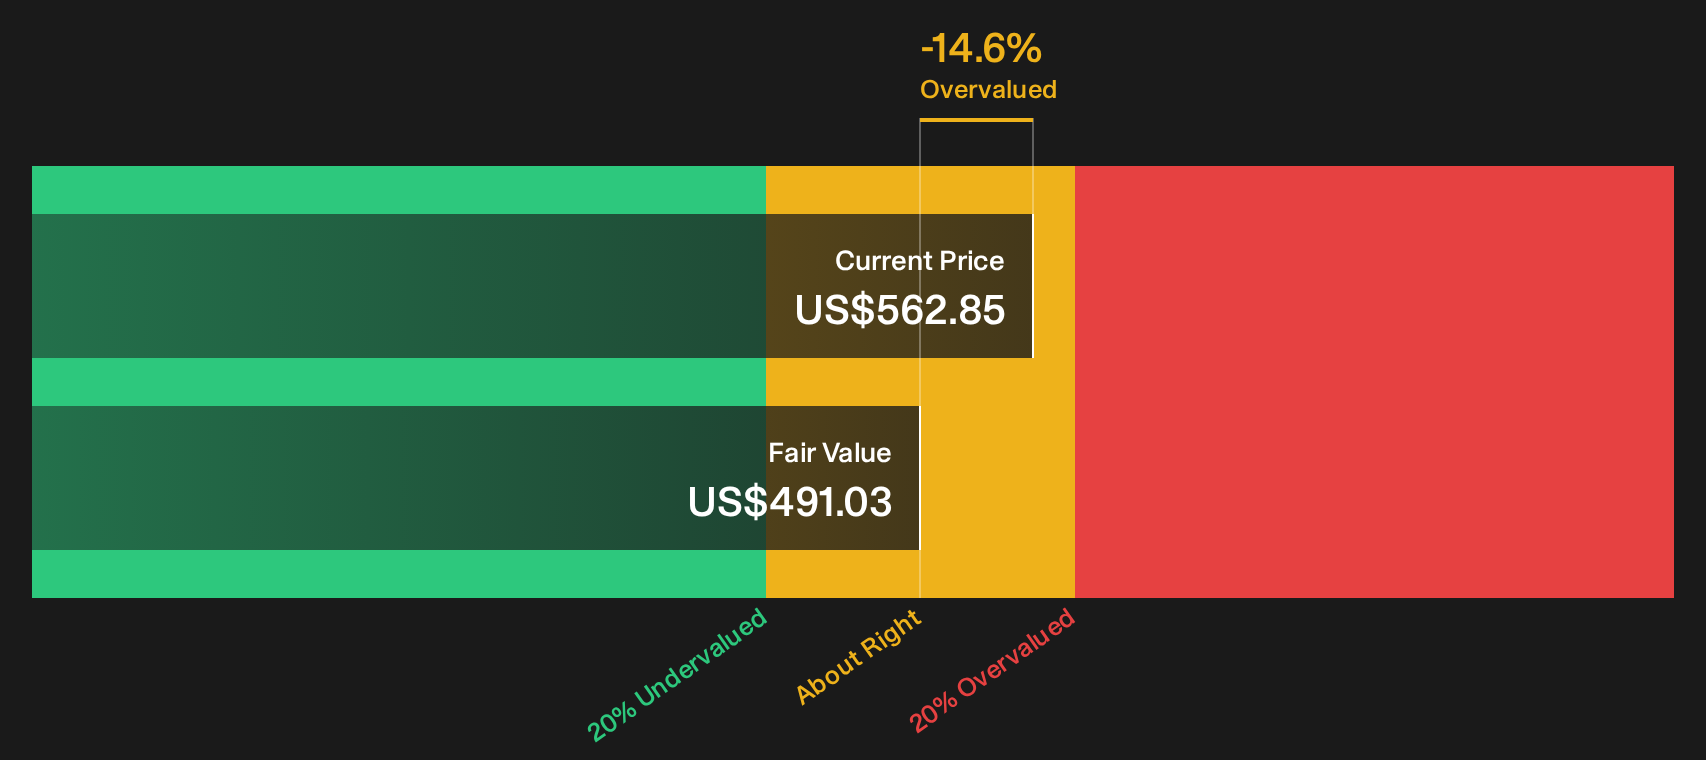
The analyst target suggests Curtiss-Wright is materially undervalued, yet the SWS DCF model points the other way. On a cash flow basis, the shares trade around $562.85 compared with an estimated future cash flow value of $491.03, which implies investors are already paying a premium for expected growth and quality.
That gap between price and cash flow value can signal less room for error if growth or margins fall short, even when the narrative around defense and nuclear remains strong. The key question is which yardstick you trust more when the story and the spreadsheet disagree.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Curtiss-Wright for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment split on Curtiss-Wright’s recent slide and valuation gap, move quickly, check the underlying numbers yourself, and pressure test the upside using 3 key rewards.
Looking for more investment ideas beyond Curtiss-Wright?
If Curtiss-Wright has sharpened your interest in high quality industrial and defense exposure, broaden your watchlist now and avoid missing other compelling setups across the market.
- Spot potential value early and review the 16 high quality undiscovered gems that pair strong fundamentals with less crowded ownership.
- Strengthen your downside protection and check the 11 resilient stocks with low risk scores that score well on resilience and balance sheet quality.
- Build a watchlist of financially robust businesses and scan the list of solid balance sheet and fundamentals (22 results) that combine dependable finances with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com