


NVR Stock: Is NVR Underperforming the Consumer Cyclical Sector?
With a market cap of $16.7 billion, NVR, Inc. (NVR) is a leading company operating through two primary business segments: homebuilding and mortgage banking. Its homebuilding segment constructs and sells homes under the Ryan Homes, NVHomes, and Heartland Homes brands.
Companies valued at $10 billion or more are generally considered “large-cap” stocks, and NVR fits this criterion perfectly. The company serves customers across 37 metropolitan areas in 16 states and Washington, D.C.
Shares of the Reston, Virginia-based company have fallen 25.8% from its 52-week high of $8,429.99. The stock has decreased 1.2% over the past three months, a less pronounced decline than the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 6.2% dip over the same time frame.
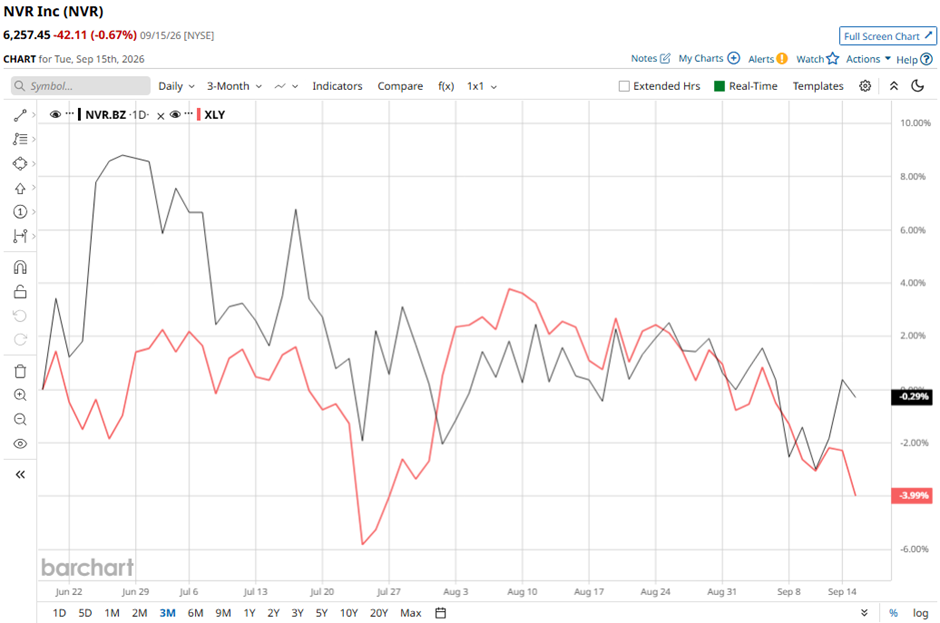
NVR stock is down 14.2% on a YTD basis, a steeper decline than XLY’s 6.9% drop. In the longer term, shares of the homebuilder have fallen 24.4% over the past 52 weeks, compared to XLY’s 8.2% decline over the same time frame.
Despite a few fluctuations, the stock has been trading below its 50-day and 200-day moving averages since last year.
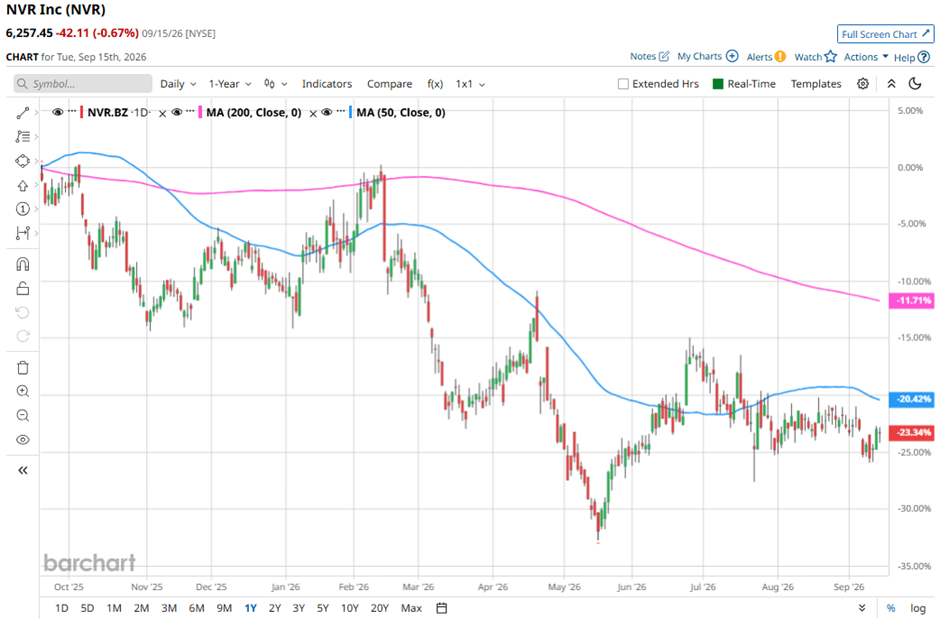
NVR shares fell 3.1% on Jul. 23 due to weaker-than-expected Q2 2026 EPS of $83.96 and Homebuilding revenue of $2.28 billion fell 10.5% year-over-year. Results were pressured by 8% fewer settlements, a 3% decline in average settlement price to $450,700, and Homebuilding gross margin compression to 19.2%, reflecting higher lot costs, affordability challenges and $21.7 million of land-deposit impairments. Although net new orders rose 9% to 5,885 units and backlog increased 9% to 10,998 units, the 5% decline in new-order ASP to $437,100 and weaker mortgage activity reinforced concerns.
In comparison, rival D.R. Horton, Inc. (DHI) has shown a smaller decline than NVR stock. DHI stock has decreased 2.6% on a YTD basis and 18.3% over the past 52 weeks.
Despite the stock’s underperformance over the past year, analysts remain moderately optimistic on NVR. The stock has a consensus rating of “Moderate Buy” from the eight analysts in coverage, and the mean price target of $6,912.71 is a premium of 10.5% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.