


How Investors Are Reacting To StandardAero (SARO) Winnipeg Engine Service Expansion
- StandardAero recently opened a 70,000 sq. ft. expansion at its Winnipeg facility, adding full MRO capability for CF34 and CFM56 engines that support regional, business and military aircraft across North America and globally.
- The enlarged Winnipeg footprint, supported by 1,500 skilled workers across eight local sites, deepens StandardAero’s exposure to high-volume engine platforms that underpin recurring maintenance demand from airlines, business aviation operators and defense customers.
- We will look at how StandardAero's investment narrative is influenced by the expanded Winnipeg MRO capacity for CF34 and CFM56 engines.
Scan other aerospace and defense service specialists that are building recurring maintenance demand by checking the curated 11 resilient stocks with low risk scores, which highlights companies sharing traits with StandardAero's expanded CF34 and CFM56 engine support footprint.
StandardAero Investment Narrative Recap
To own StandardAero, you need to believe in a long runway of recurring engine maintenance on platforms like CF34, CFM56 and LEAP, plus continued execution on Component Repair Services. The Winnipeg expansion directly supports that thesis by adding capacity where fleets are already flying today, rather than betting on unproven programs.
The key near term swing factor is whether zero margin LEAP and CFM56 DFW work transitions smoothly toward profitability while parts supply constraints ease. The new Winnipeg capacity does not remove those pressures. It mainly raises execution risk if supply bottlenecks or labor productivity issues slow the ramp across the broader network.
The Winnipeg build out is most relevant to the existing catalyst around expanding high value CF34 and CFM56 programs. That 70,000 sq. ft. addition gives StandardAero more room to process regional jet, business jet and single aisle work tied to Embraer, MHIRJ, Boeing 737 NG, A320ceo and related military variants.
For investors, the question is whether this extra footprint helps StandardAero convert its large installed base into steadier earnings while managing debt that is not well covered by operating cash flow. Execution on this and the DFW and Augusta facilities will influence how reported margins, cash generation and perceived risk develop from here.
StandardAero's narrative projects US$7.3b revenue and US$549.2m earnings by 2028. This assumes 7.4% yearly revenue growth and an earnings increase of about US$364.5m from current earnings of US$184.7m.
Uncover why StandardAero's fair value indicates a 53% potential upside to its current price, which could narrow quickly.
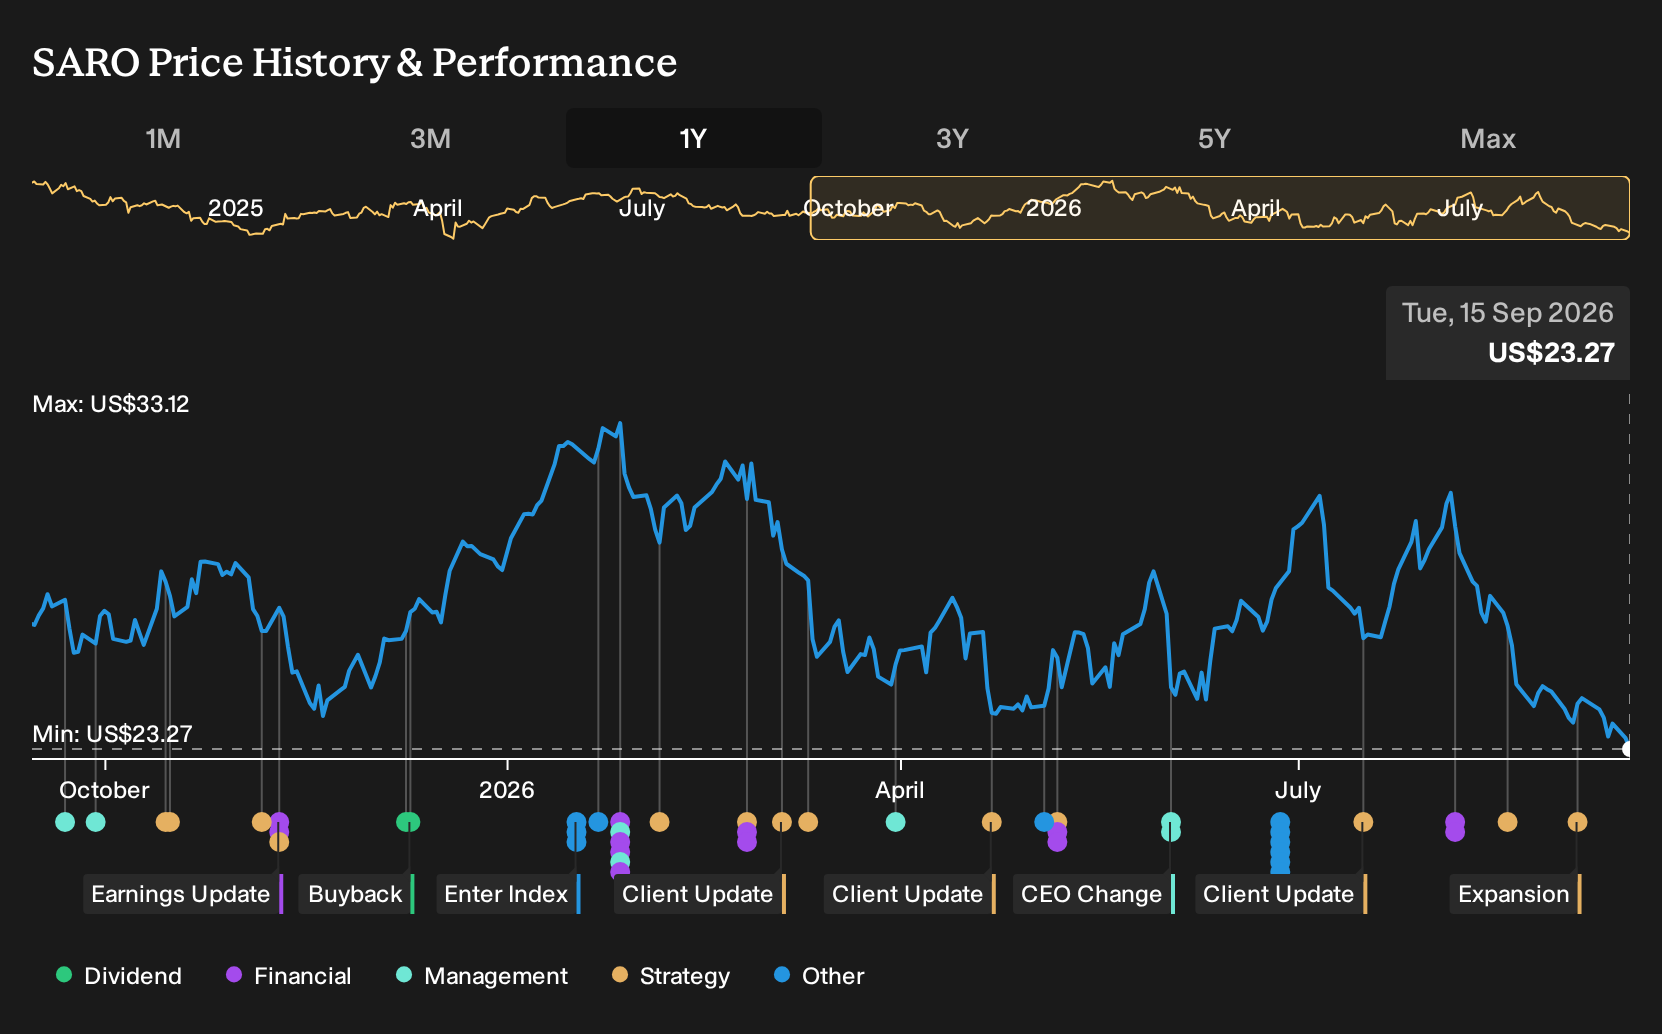
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster in a tight US$33.7 to about US$38.6 band, so retail opinions already differ before factoring in StandardAero’s new Winnipeg capacity. You need to weigh that spread against risks around parts shortages and zero margin LEAP and CFM56 work that could influence future cash generation.
Explore 3 other StandardAero fair value estimates, including one that suggests it could be worth just $33.70!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your StandardAero research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for StandardAero. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StandardAero's overall financial health at a glance.
Looking For More Investment Ideas Beyond StandardAero?
If you want to stress test your view on StandardAero, compare it with other businesses that share similar financial traits using the Simply Wall St Screener. It helps you see where this stock fits within a broader opportunity set instead of viewing it in isolation.
- For investors who want income to feel more predictable, review a curated group of higher yielding candidates through 6 dividend fortresses.
- If resilience and balance sheet strength matter most to you, line up potential holdings using the list of solid balance sheet and fundamentals (22 results).
- To widen your watchlist with overlooked opportunities, scan the 16 high quality undiscovered gems that combine strong fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com