


Will New COO Appointment Change JLL Stock Narrative
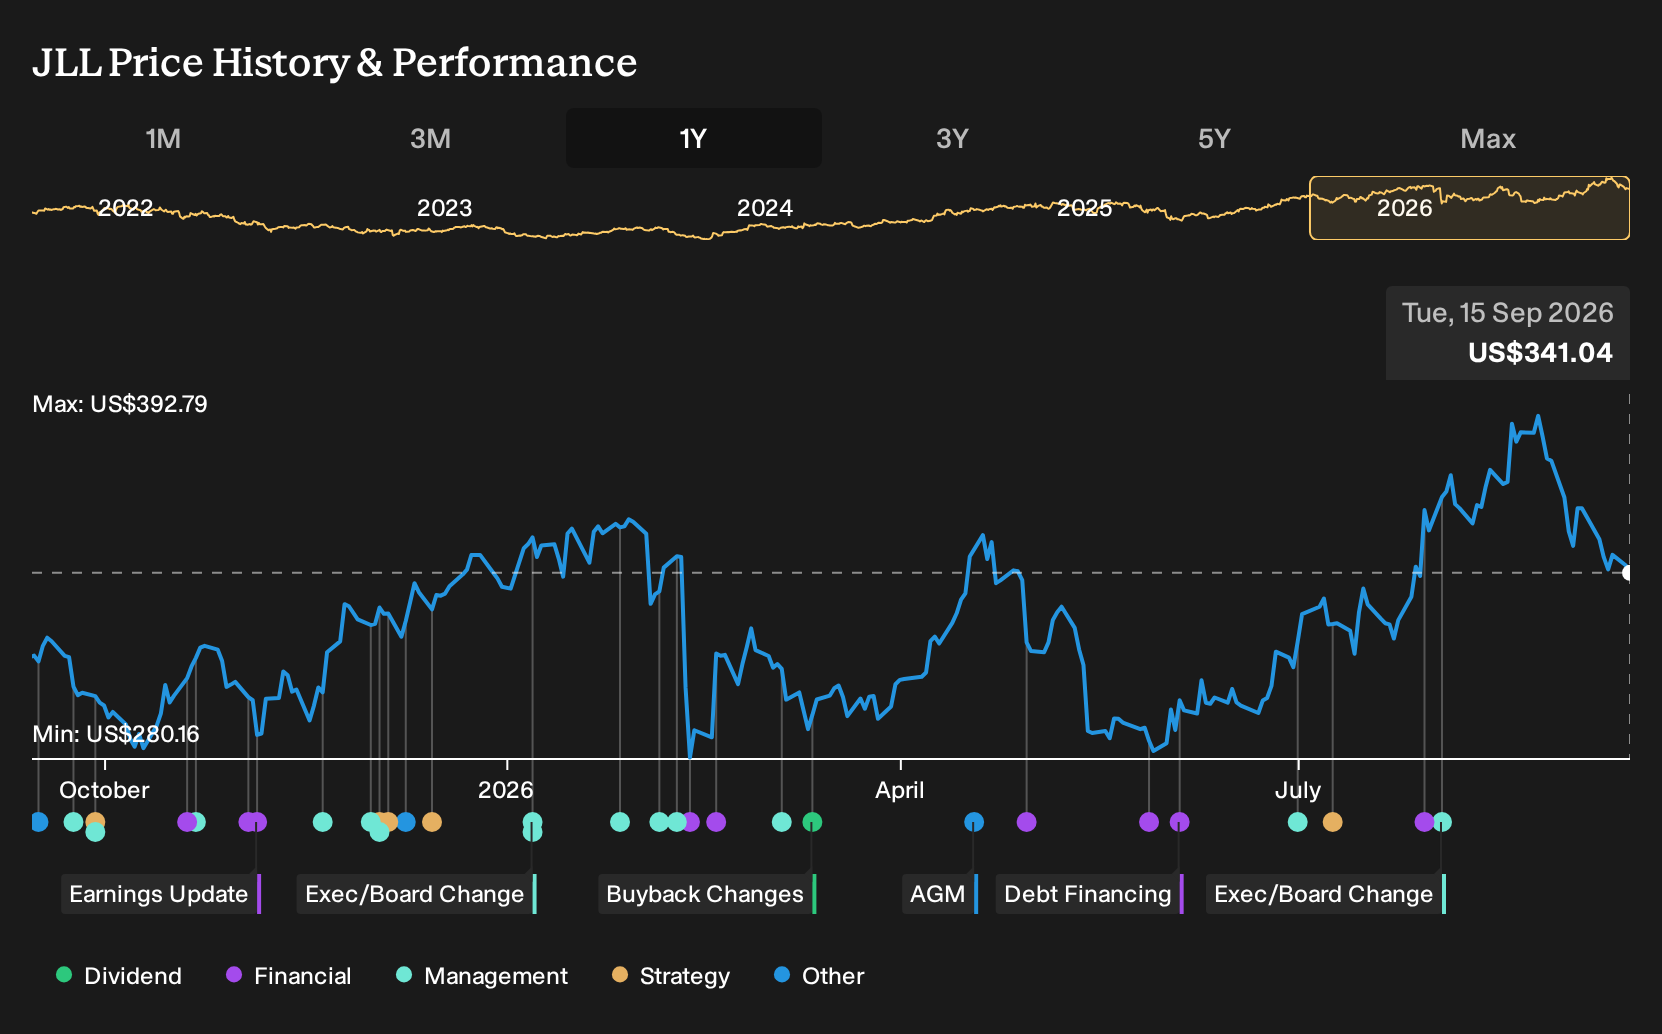
- Jones Lang LaSalle appointed Paul Morgan as Chief Operating Officer on 16 September 2026, adding him to the Global Executive Board and tasking him with leading a unified global operations function aligned to the Accelerate 2030 plan.
- The move concentrates JLL's operational expertise under one leader, which could meaningfully affect cost discipline, service consistency and how technology supports recurring fee businesses over time.
- We will now look at how JLL's investment narrative could shift as Paul Morgan takes charge of the new global operations platform.
Scan how JLL's new COO-led platform focus compares with other real estate operators by reviewing our hand-picked list of solid balance sheet and fundamentals (22 results) that is poised for disciplined execution and scalable operations.
Jones Lang LaSalle Investment Narrative Recap
For Jones Lang LaSalle, the key belief is that recurring workplace and project services, backed by a unified global platform, can offset more volatile leasing and capital markets cycles. The near term swing factor still sits in transaction volumes. The new COO structure looks important, but the operational change is gradual, so it may not immediately shift that sensitivity.
The biggest risk remains softer activity in office leasing and capital markets, especially in mature markets like the US and Europe, together with contract churn in property management. Paul Morgan's remit tightens execution around profitability, tech and scale. That can support margins if transaction-driven revenue weakens or contract mix takes time to reset.
The Global Real Estate Transparency Index is the clearest adjacent data point to consider alongside this COO move. JLL is documenting that two thirds of markets it tracks have become more transparent, helped by digitization and reforms in regions such as India, Vietnam, APAC and MENA. More transparent markets tend to attract more institutional capital and more complex mandates.
JLL is effectively signaling that it sees growing opportunity where transparency and data quality are improving, while it builds a single operations platform under Morgan to serve that flow. If transaction markets stay uneven, nearer term interest centers on whether this structure tightens cost discipline and supports recurring fee lines, while the transparency trend gradually widens the opportunity set.
Jones Lang LaSalle's current analyst narrative points to revenues of $32.4b and earnings of $1.3b by 2029, anchored on 6.6% yearly revenue growth and an earnings increase of about $404.2m from $895.8m today.
Uncover how Jones Lang LaSalle's fair value indicates a 12% potential upside to its current price before investors fully close that discount gap.
Exploring Other Perspectives
Some of the most optimistic analysts frame JLL's technology and data platform as the real swing factor. They were already modeling about $36.2b of revenue and $1.5b of earnings by 2029, compared with the broader view at $32.4b and $1.3b. You can weigh that tech-driven upside against Paul Morgan's new COO remit and decide which storyline feels more convincing, knowing both forecasts were set before this appointment and could shift as investors digest the change.
Explore 2 other Jones Lang LaSalle fair value estimates, including one that suggests up to 86% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Jones Lang LaSalle research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Jones Lang LaSalle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Jones Lang LaSalle's overall financial information at a glance.
Looking for more Jones Lang LaSalle style ideas?
If the Jones Lang LaSalle story has you thinking about quality, resilience and execution, it can help to widen the net and see how other businesses stack up on similar traits using the Simply Wall St Screener.
- For investors who want value with quality baked in, scan a curated group of companies trading below what their fundamentals suggest through 34 high quality undervalued stocks.
- If consistency and balance sheet strength matter most to you, filter for businesses with robust finances and durable profiles using the 11 resilient stocks with low risk scores.
- When you are hunting for under-the-radar opportunities with solid fundamentals, cast a wider net across our 16 high quality undiscovered gems to spot potential candidates before they gain broader attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com