


Backlog Slide Could Reshape The Case For Meritage Homes Stock (MTH)
- Meritage Homes has been flagged for pressure on its fundamentals, with an average 27.6% backlog drop over two years alongside weaker earnings per share and returns on capital.
- The combination of shrinking backlogs and lower returns suggests Meritage Homes may be experiencing sharper competitive pressure in key U.S. homebuilding markets.
- This article will examine how Meritage Homes' investment narrative is being tested by the sharp backlog decline that now affects future revenue visibility.
Scan beyond Meritage Homes and compare how other financially resilient builders are handling similar pressure points with the curated list of solid balance sheet and fundamentals (22 results).
Meritage Homes Investment Narrative Recap
To own Meritage Homes, you need to be comfortable with a builder that focuses on entry level buyers, operates with relatively short sales-to-close cycles, and now faces a 27.6% average backlog drop over two years. That weaker order book, combined with lower recent earnings per share and returns on capital, tightens the margin for error.
The key near-term swing factor is how effectively Meritage Homes balances incentives and pricing against demand from more rate-sensitive buyers. The biggest risk is that pressure on affordability keeps incentives elevated, which could prolong margin compression while backlog stays thin and makes quarterly revenue more volatile.
Recent commentary around Meritage Homes has focused on backlog and returns, but the same data also highlights management relying on efficiency and a relatively lean cost structure. A forward P/E of 11.5x suggests investors are already treating the stock as exposed to cyclical and competitive pressure, rather than assigning it a premium for growth.
With no new company-specific announcements flagged since the backlog concerns emerged, the most relevant reference point is still the existing narrative on community expansion, shorter build times of about 110 days, and a focus on move-in-ready homes. These operational levers are central to any potential upside case, because they can help offset pricing pressure if volumes remain choppy.
Meritage Homes' narrative projects US$6.4b revenue and US$453.0m earnings by 2029. This assumes 4.3% yearly revenue growth and about a US$67.5m earnings increase from US$385.5m today.
Uncover how Meritage Homes' fair value indicates a 22% potential upside to its current price before the market closes that gap.
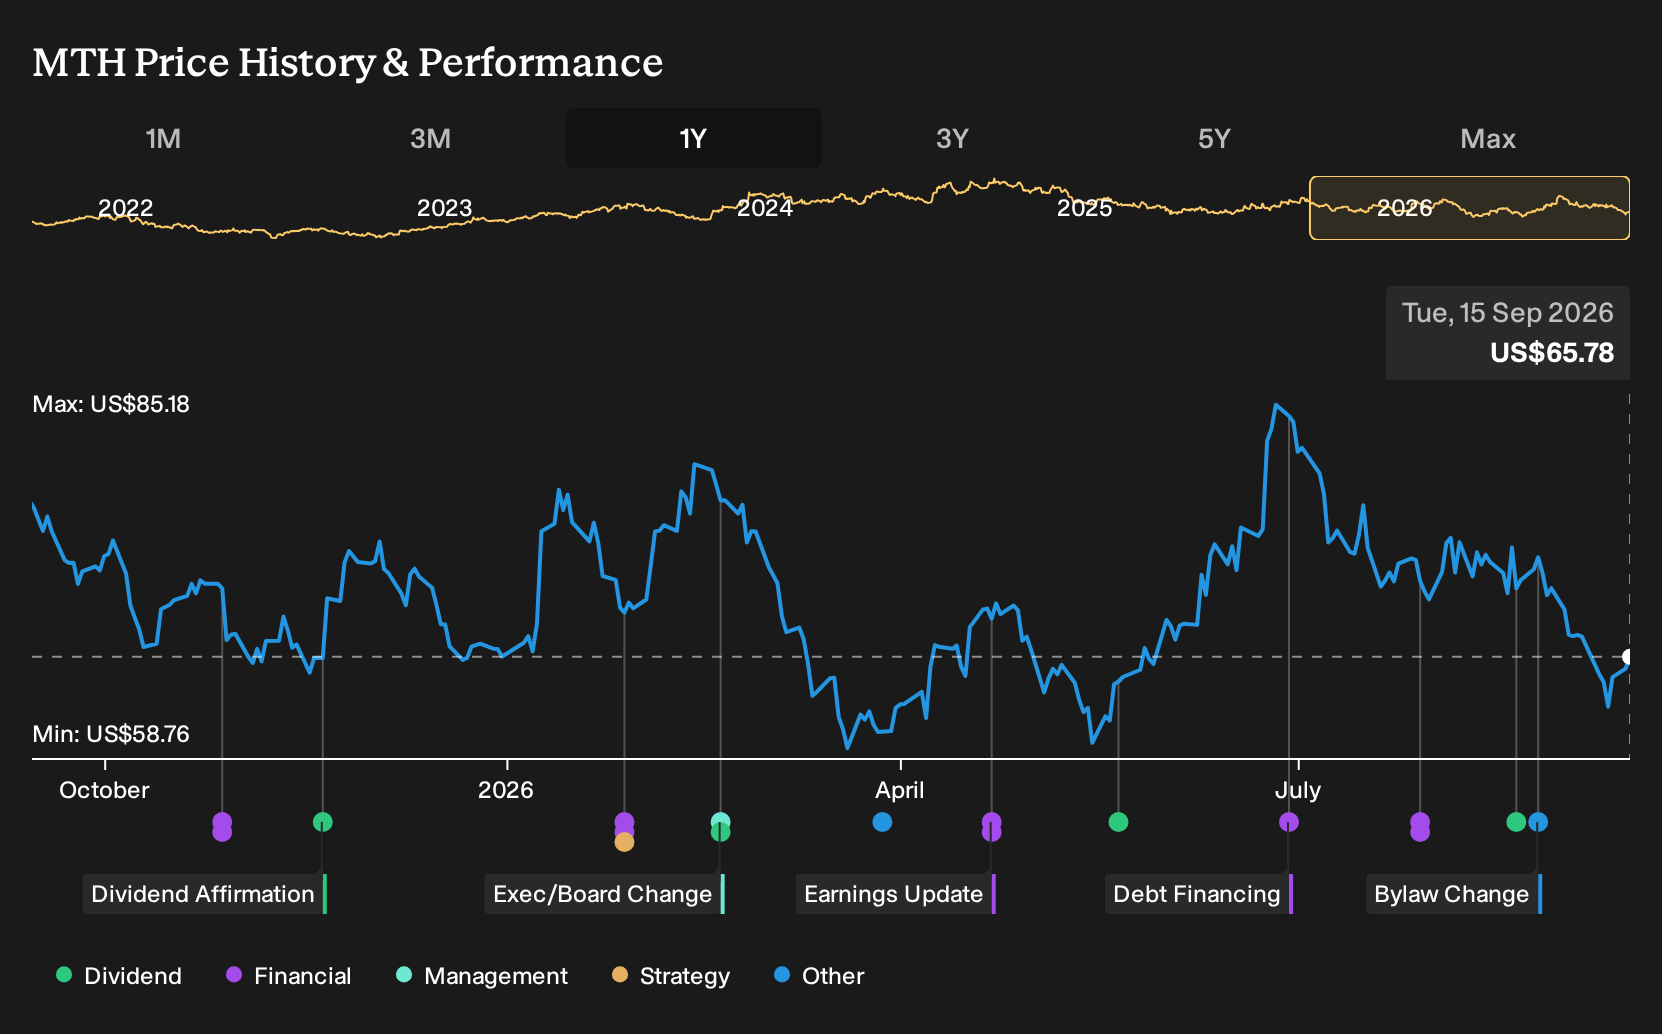
Exploring Other Perspectives
One alternate angle on Meritage Homes leans hard into the affordability risk. The most pessimistic analysts already expected only about US$6.2b of revenue and US$471.5m of earnings by 2029, on a lower 10.4x P/E. Those views were set before this backlog shock, so you should expect opinions to potentially shift and compare several scenarios yourself.
Explore 3 other Meritage Homes fair value estimates, including one that suggests it could be worth just $72.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Meritage Homes research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Meritage Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meritage Homes' overall financial health at a glance.
Looking for more Meritage Homes style investment ideas?
If the Meritage Homes story has you thinking about where else strong fundamentals and clear narratives might intersect, broaden your watchlist with a few focused stock screens that keep the homework manageable and the filters tight.
- For investors who like quality on sale, start with a curated set of companies that combine robust balance sheets with valuations that screen as attractive through the 34 high quality undervalued stocks.
- If income is your priority, concentrate on businesses that pair higher yields with an emphasis on durability using the 6 dividend fortresses.
- For a focus on resilience, filter for businesses with stronger financial foundations and lower overall risk scores by scanning the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com