


Shift4 Payments (FOUR) Faces Fresh Sector Doubts, Is The Discount Enough?
Shift4 Payments (FOUR) drew fresh attention after a sector report questioned its competitiveness and growth potential compared with other payment technology providers, a critique that coincided with a single-day share price decline of 5.7%.
For context, Shift4 Payments shares are now at US$42.35. The 90-day share price return is up 8.12% even after a one-day drop of 6.55%, while the year-to-date share price return is down 32.43% and the 1-year total shareholder return has fallen 50.94%. This points to fading momentum and a market that is rethinking both the growth potential and the risk around the story.
Compare how the Shift4 Payments story stacks up against other payment processors by scanning a curated set of 34 high quality undervalued stocks that the market may be mispricing right now.
After the sharp reset in Shift4 Payments at US$42.35, the real debate is whether this pullback leaves meaningful upside on the table or if the best of the story already sits in the rear-view mirror, and that question largely comes down to valuation.
Most Popular Narrative: 23% Undervalued
At a last close of $42.35 versus a narrative fair value of $55.30, the current Shift4 Payments price reflects a sizable discount. This discount depends on whether the expansion and integration story unfolds as outlined.
The cross-sell opportunity across the combined customer bases of newly acquired companies (for example, bringing Shift4's payment products into Global Blue's luxury retail clients, or introducing Global Blue's DCC product to Shift4 hotels and restaurants) creates a substantial embedded pipeline for incremental revenue and sustained organic growth over multiple years.
See why 68 investors see Shift4 Payments as 23% undervalued.
Result: Fair Value of $55.30 (UNDERVALUED)
Still, the bullish Shift4 Payments narrative runs into real friction if integration of recent acquisitions stalls or higher debt costs continue to squeeze future earnings power.
Find out about the key risks to this Shift4 Payments narrative.
Another View On Shift4 Payments Valuation
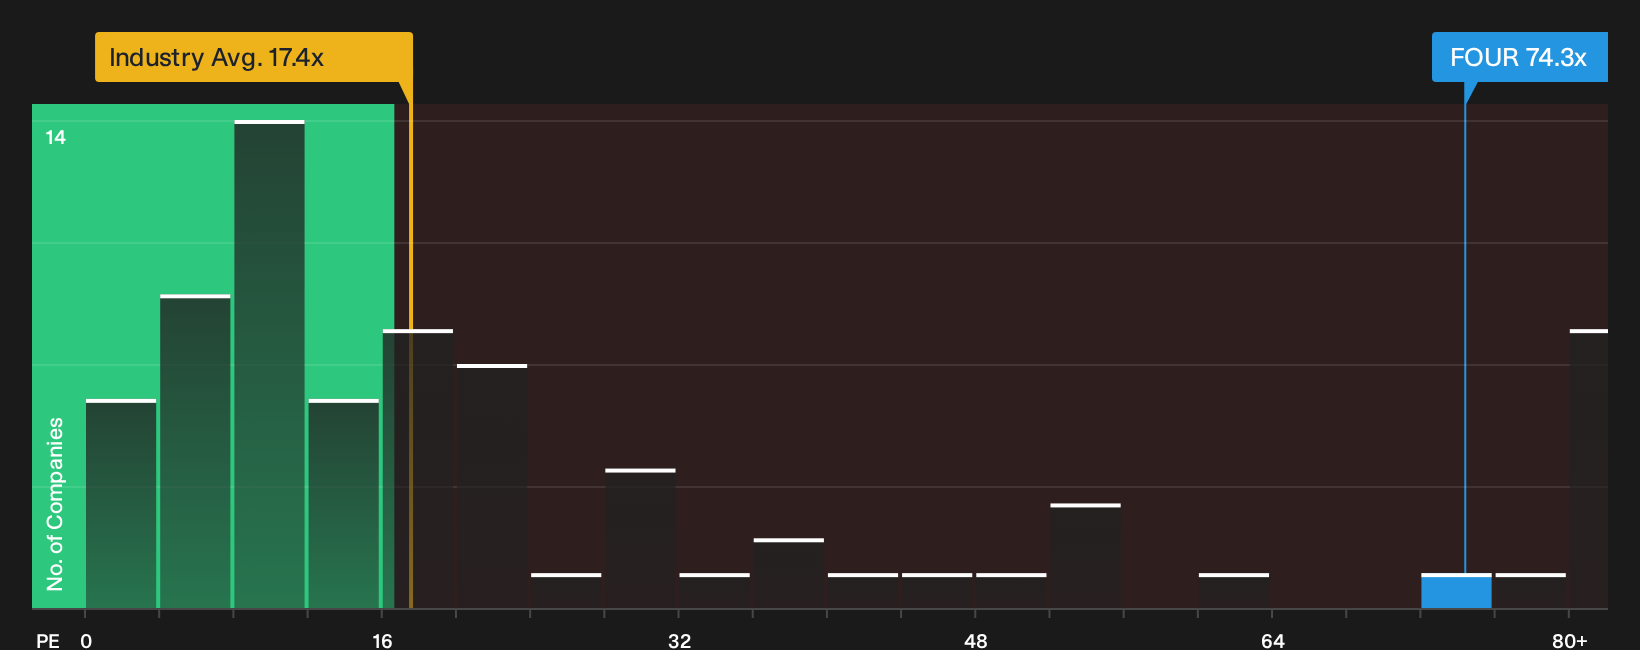
The narrative fair value for Shift4 Payments points to upside, but the P/E snapshot tells a different story. The stock trades on a P/E of 74.3x, while the fair ratio sits at 37.5x, the US Diversified Financial industry is at 17.4x, and peers average 38.2x. That is a steep premium in every direction. The question is whether you think future earnings can comfortably close that gap before the multiple moves.
For a closer look at how this richer P/E profile compares with the underlying fundamentals, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Shift4 Payments can be confusing. Check the underlying data promptly and weigh both sides of the story through the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Shift4 Payments?
You do not need to stop at Shift4 Payments. Put fresh ideas on your radar quickly by running a few focused screens that surface very different types of opportunities.
- Target resilient potential compounders by scanning a 11 resilient stocks with low risk scores with financial profiles that aim to keep surprises to a minimum.
- Hunt for mispriced quality by working through a 16 high quality undiscovered gems that many investors may not be watching closely yet.
- Focus on balance sheet strength by reviewing a list of solid balance sheet and fundamentals (22 results) that can help you avoid fragile businesses when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com