


How Growth Plans Will Impact PayPal Stock Investors
- PayPal Holdings has outlined plans to use its free cash flow for targeted acquisitions that fit its growth roadmap, while also prioritizing integration discipline, financial returns, and alignment with its broader business strategy.
- The company is presenting agentic payments, digital identity, and PYUSD as long-horizon growth levers that complement its core payments platform, while it manages slower user additions and tougher online checkout competition.
- We will now look at how PayPal Holdings' refreshed growth focus and M&A plans could reshape the existing investment narrative.
Scan how PayPal Holdings' M&A push fits into a broader payments and fintech reset by comparing it with 16 high quality undiscovered gems that could be building similar growth stories away from the spotlight.
PayPal Holdings Investment Narrative Recap
To own PayPal Holdings, you need to believe its shift from pure payments to a broader commerce and smart wallet platform can offset slower user growth and heavier checkout competition. The immediate swing factor is execution on higher margin volumes such as value added services and branded experiences, while keeping earnings quality intact.
The biggest near term risk still comes from pressure on transaction growth if consumer spending weakens or competitors win more checkout share, especially in key markets such as the UK. The fresh M&A push looks incremental rather than transformative in the short run, so it does not materially change those core drivers yet.
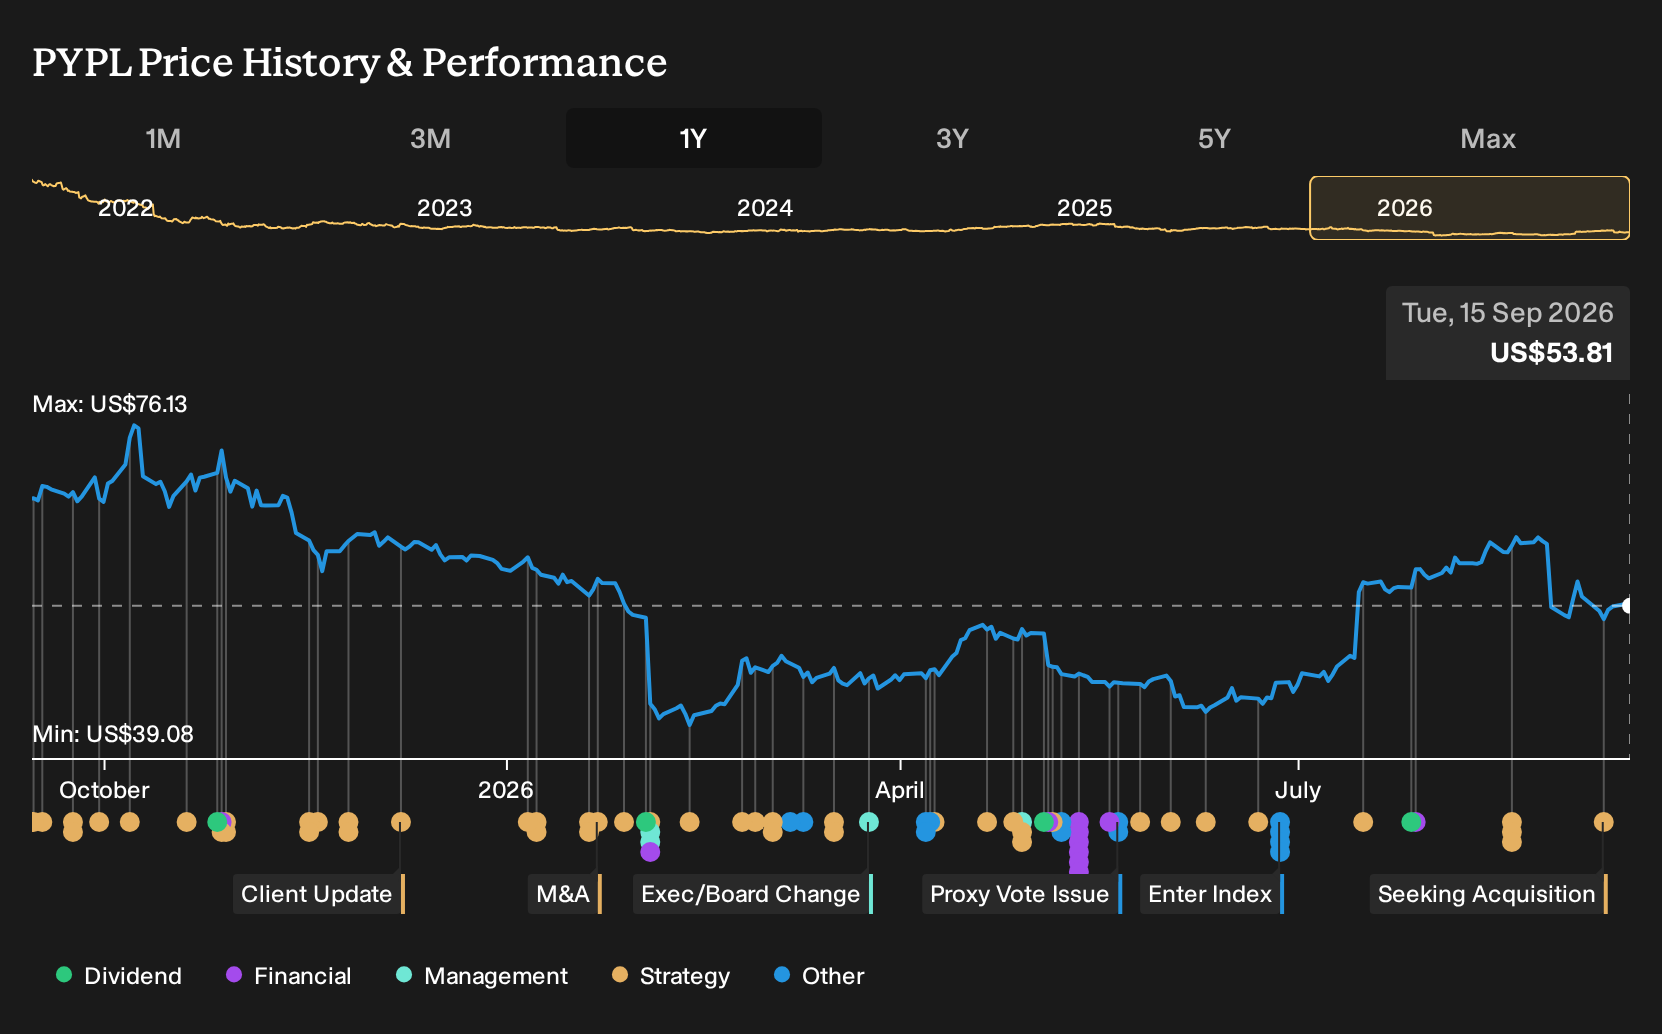
The clearest linked announcement is management flagging plans to use PayPal Holdings free cash flow for acquisitions tied directly to its growth roadmap. That matters operationally because the group is already shifting away from less profitable Braintree volume and leaning into services such as BNPL, fraud tools, and omnichannel offerings to support margins.
If deals arrive from the next quarter, integration discipline becomes a real test. You want to see any acquired assets reinforce things that already work, such as the commerce platform vision, PYUSD, or agentic payments, without distracting management from sharpening branded checkout and controlling regulatory and macro risks around cross border payments.
Analysts project that PayPal Holdings could reach approximately US$39.1b in revenue and US$4.7b in earnings by 2029, which corresponds to around 4.7% yearly revenue growth and an earnings decline of roughly US$0.2b from current earnings of about US$4.9b.
Uncover why PayPal Holdings' fair value indicates a 10% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate view treats PayPal Holdings M&A push as a risk rather than a growth lever. The most pessimistic analysts were already working off slower revenue growth of about 2.3% a year and earnings of roughly US$4.2b by 2029. You can see how new deal activity might force those assumptions to be revisited in very different ways, so it helps to compare several narratives side by side before deciding what feels reasonable to you.
Explore 30 other PayPal Holdings fair value estimates, including one that suggests it could be worth just $57.07.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PayPal Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PayPal Holdings' overall financial health at a glance.
Looking for more investment ideas beyond PayPal Holdings?
If the PayPal Holdings story has sharpened your thinking, you can apply the same lens to a wider watchlist by using the Simply Wall St Screener to spot other companies that fit the kind of profile you want to research next.
- If you care most about resilient balance sheets and robust fundamentals, start with this curated list of solid balance sheet and fundamentals (22 results) that keeps financial strength front and center in your search process.
- For readers who want potential value opportunities, use the 34 high quality undervalued stocks to focus on businesses where quality metrics and price are pulling in different directions.
- If capital preservation is your first filter, begin with the 11 resilient stocks with low risk scores and narrow in on companies that score well on Simply Wall St's risk checks before you spend more time on deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com