


How Investors Are Reacting To SolarEdge (SEDG) AI Data Center Progress
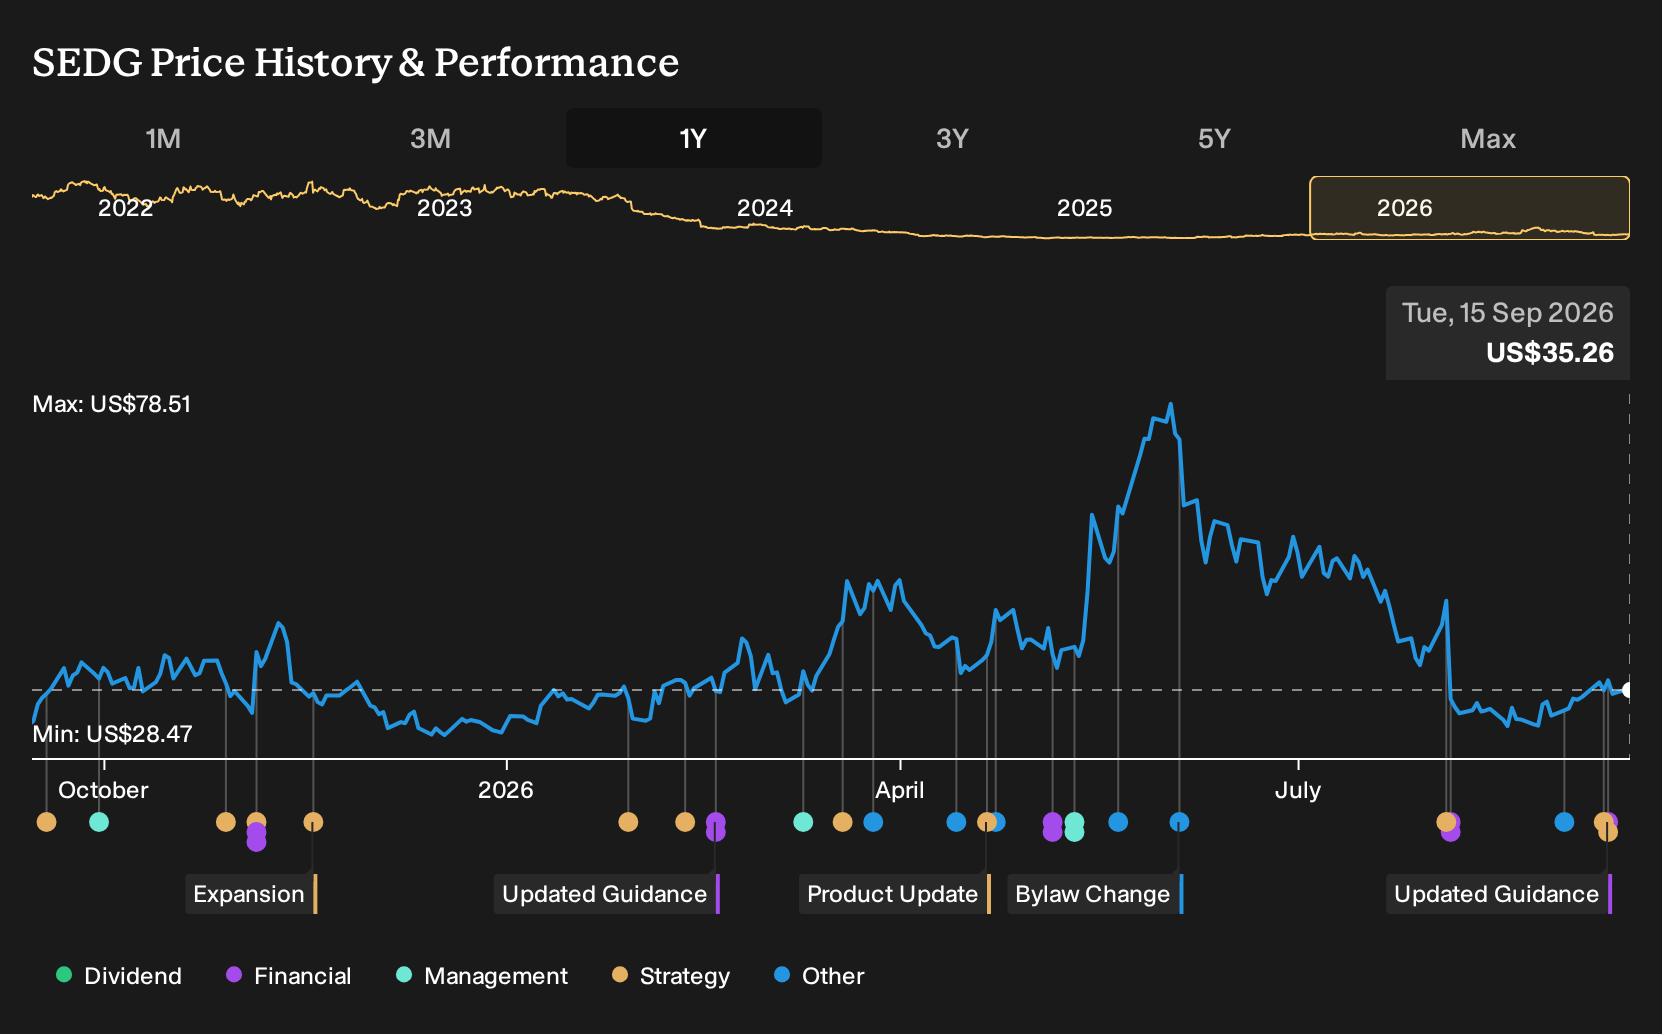
- SolarEdge Technologies reiterated its third quarter 2026 revenue guidance at US$310 million to US$340 million and reported progress on its 800 VDC AI data center powertrain, including a live medium voltage conversion stage and a detailed protection and grounding framework.
- The firm is extending its DC power electronics expertise into AI data centers through joint work with NVIDIA on 800 VDC safety standards and a deeper Infineon partnership on solid-state circuit breakers, signaling a push toward a full grid to rack DC platform.
- We will now look at how SolarEdge Technologies' investment narrative could be reshaped by its push into 800 VDC AI data center infrastructure.
SolarEdge Technologies Investment Narrative Recap
To own SolarEdge Technologies, you need to believe the core solar and storage operations can move from losses toward more stable profitability while the new data center effort gets through its build out phase. Management reiterating third quarter 2026 revenue guidance of US$310 million to US$340 million keeps near term expectations in place rather than resetting them.
The key short term catalyst remains evidence that demand and pricing in core solar channels are healthy enough to support margin repair and better cash generation. The biggest risk is that the new AI data center platform absorbs capital and focus without timely commercial traction, which would prolong the period of weak earnings.
The most relevant update for that thesis is the announcement that SolarEdge Technologies now has its medium voltage to 800 VDC conversion stage running under load and has published an 800 VDC protection and grounding framework with NVIDIA. That shows the AI powertrain is moving from concept into technical validation.
For you as an investor, a potential catalyst is whether this 800 VDC platform can eventually create a second leg of revenue alongside solar while using the firm’s long standing DC protection functions. Execution risk is real, since these AI data center products are still under development and not generally available, so adoption timing and certification progress remain key watchpoints.
SolarEdge Technologies' current revenue outlook reflects analyst assumptions that annual sales will expand at 8.7% for the next few years, reaching about US$1.7b of revenue and US$83.9 million of earnings by 2029, compared with a loss of US$270.3 million in earnings today. This implies an earnings swing of roughly US$354 million over that period.
Uncover why SolarEdge Technologies' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One contrasting angle focuses on the potential upside from SolarEdge Technologies becoming more of a full-stack energy and software platform. The most bullish analysts were already penciling in US$2.2b of revenue and US$214.0 million of earnings by 2029 before this 800 VDC news. Opinions diverge sharply, so consider several viewpoints and decide which story fits your expectations as fresh AI data center updates roll in.
Explore 3 other SolarEdge Technologies fair value estimates, including one that suggests as much as 103% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your instincts.
- A great starting point for your SolarEdge Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SolarEdge Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SolarEdge Technologies' overall financial health at a glance.
Looking for more SolarEdge Technologies style ideas?
If the SolarEdge Technologies story has sharpened your thinking about where power, AI and balance sheet strength intersect, it can help to line it up against other opportunities using the Simply Wall St Screener.
- If you prefer companies with strong finances and fewer balance sheet surprises over time, then scan a curated list of solid balance sheet and fundamentals (22 results).
- If you want potential value on your side, compare SolarEdge Technologies with a 34 high quality undervalued stocks that pair quality fundamentals with appealing valuations.
- For readers who care most about stability and income, focus your research on a set of 6 dividend fortresses that may offer more predictable cash returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com