


Element Solutions (ESI) Stock May Trade At A Premium To Earnings
Element Solutions has had a choppy few weeks, yet the longer track record still shows a strong run, which naturally raises the question of whether the current share price lines up with what its earnings can support. For anyone watching Element Solutions stock after a pullback, the issue is whether that earnings profile is enough to justify where the market now values the business.
- Over the past 3 years the stock has returned 68.4%, which places more focus on whether the earnings power of the business can support a higher valuation than in the past.
- The company depends on earning power from its specialty materials portfolio, so the durability of margins and the conversion of profit into cash can play a big role in how investors judge today’s valuation.
- Your read on Element Solutions is one view; the desks covering it have another. See what analysts think Element Solutions's shares could be worth.
The stock's next move may depend on whether Element Solutions' current earnings are strong and reliable enough to justify the price investors are paying today.
If you are weighing Element Solutions against similar earnings driven ideas, it can help to compare it with companies surfaced by the 34 high quality undervalued stocks
Does Element Solutions Look Pricey on Earnings?
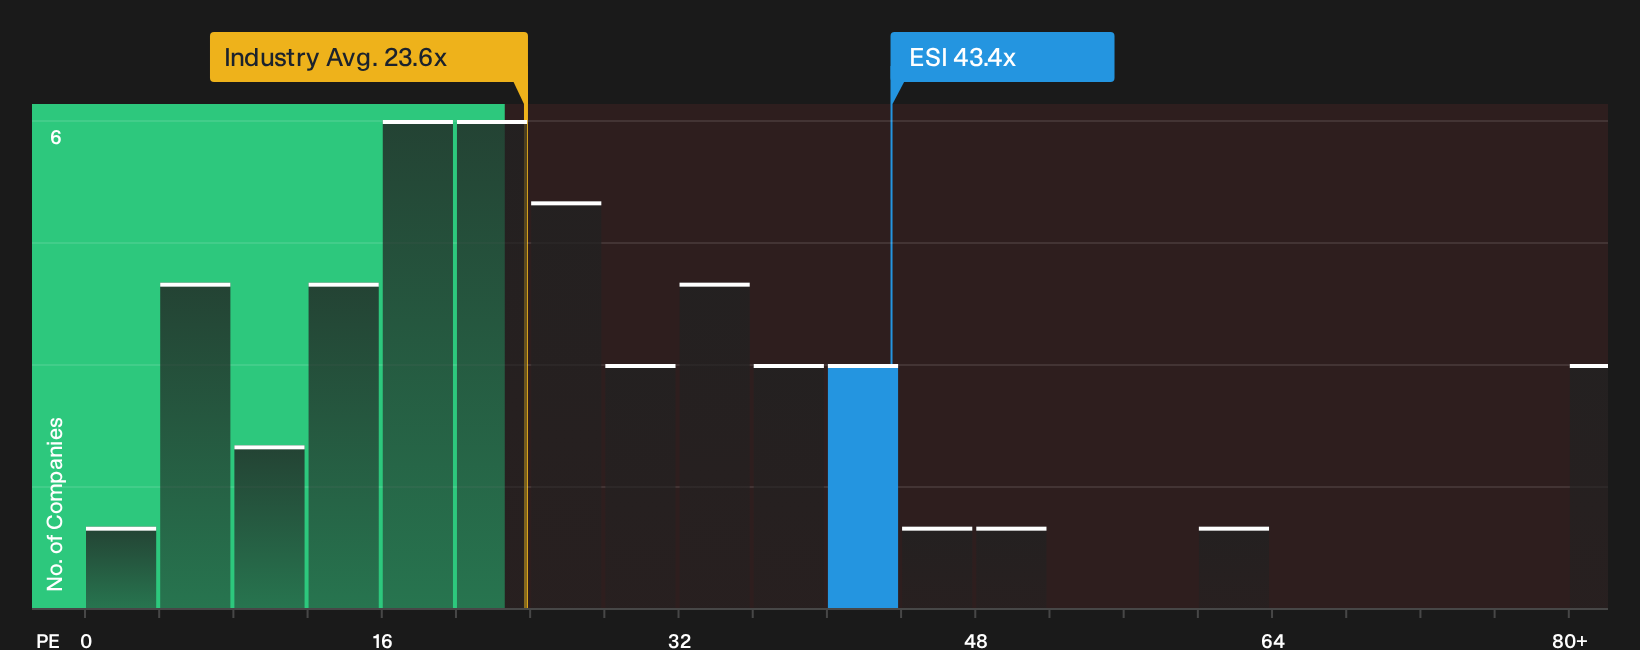
The P/E ratio fits Element Solutions because earnings are a central lens for how investors tend to judge specialty chemicals businesses. Right now the stock trades on about 43.4x earnings, which is well above the Chemicals sector average of roughly 23.6x and also higher than the peer group around 24.9x. That kind of mark up indicates the market is placing a rich price on each dollar of current profit.
A tailored fair P/E for Element Solutions, based on its growth profile, margins, size and risk, sits below the current 43.4x level. As a result, the shares screen as overvalued on this framework rather than cheap. For anyone weighing the stock, the key question is whether Element Solutions can sustain an earnings record that convinces the market this premium is worth paying over time. Explore the numbers behind Element Solutions's P/E valuation.
The Element Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Element Solutions valuation puzzle leaves off by spelling out what kind of growth, margin profile and earnings path would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Rather than relying on a single P/E or model output, each Narrative lays out the specific assumptions behind its view of fair value so you can track those against future results as they come through.
One of the top community narratives on Element Solutions: 33% undervalued
"Solstice Advanced Materials, a spin-off from Honeywell, agreed to acquire Element Solutions in a cash and stock deal valued at about US$14.5b including assumed net debt..."
Discover why this Narrative puts Element Solutions at 33% undervalued.
One more Element Solutions check that belongs beside the current price tag
Market comparisons tell you what investors pay for Element Solutions today. Broker models sketch out where they think this business could be a few years from now, which gives you a different yardstick for the current tag. Explore where analysts expect Element Solutions to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com