


Is Long Term AI Leases Altering The Investment Case For Applied Digital Stock (APLD)?
- Applied Digital recently reported strong revenue growth, signed multiple long-term AI data center leases with investment-grade hyperscalers, and kept major projects on schedule and within budget while continuing to use debt to fund expansion.
- The business is adding sizeable, multi-year contracted lease value in AI hosting, yet still operates with negative margins and heavy capital expenditure demands. This keeps funding choices and balance sheet strength at the center of the story.
- We will now examine how Applied Digital's heavy, debt-funded buildout for long-term AI hyperscaler contracts shapes the broader investment narrative.
Applied Digital Investment Narrative Recap
To own Applied Digital, you need to believe the long-lived AI data center leases eventually outweigh the current pressure from losses, heavy debt use and capital spending. The near term story still hinges on executing these campuses on time and on budget while filling capacity under existing contracts rather than chasing incremental, unproven bets.
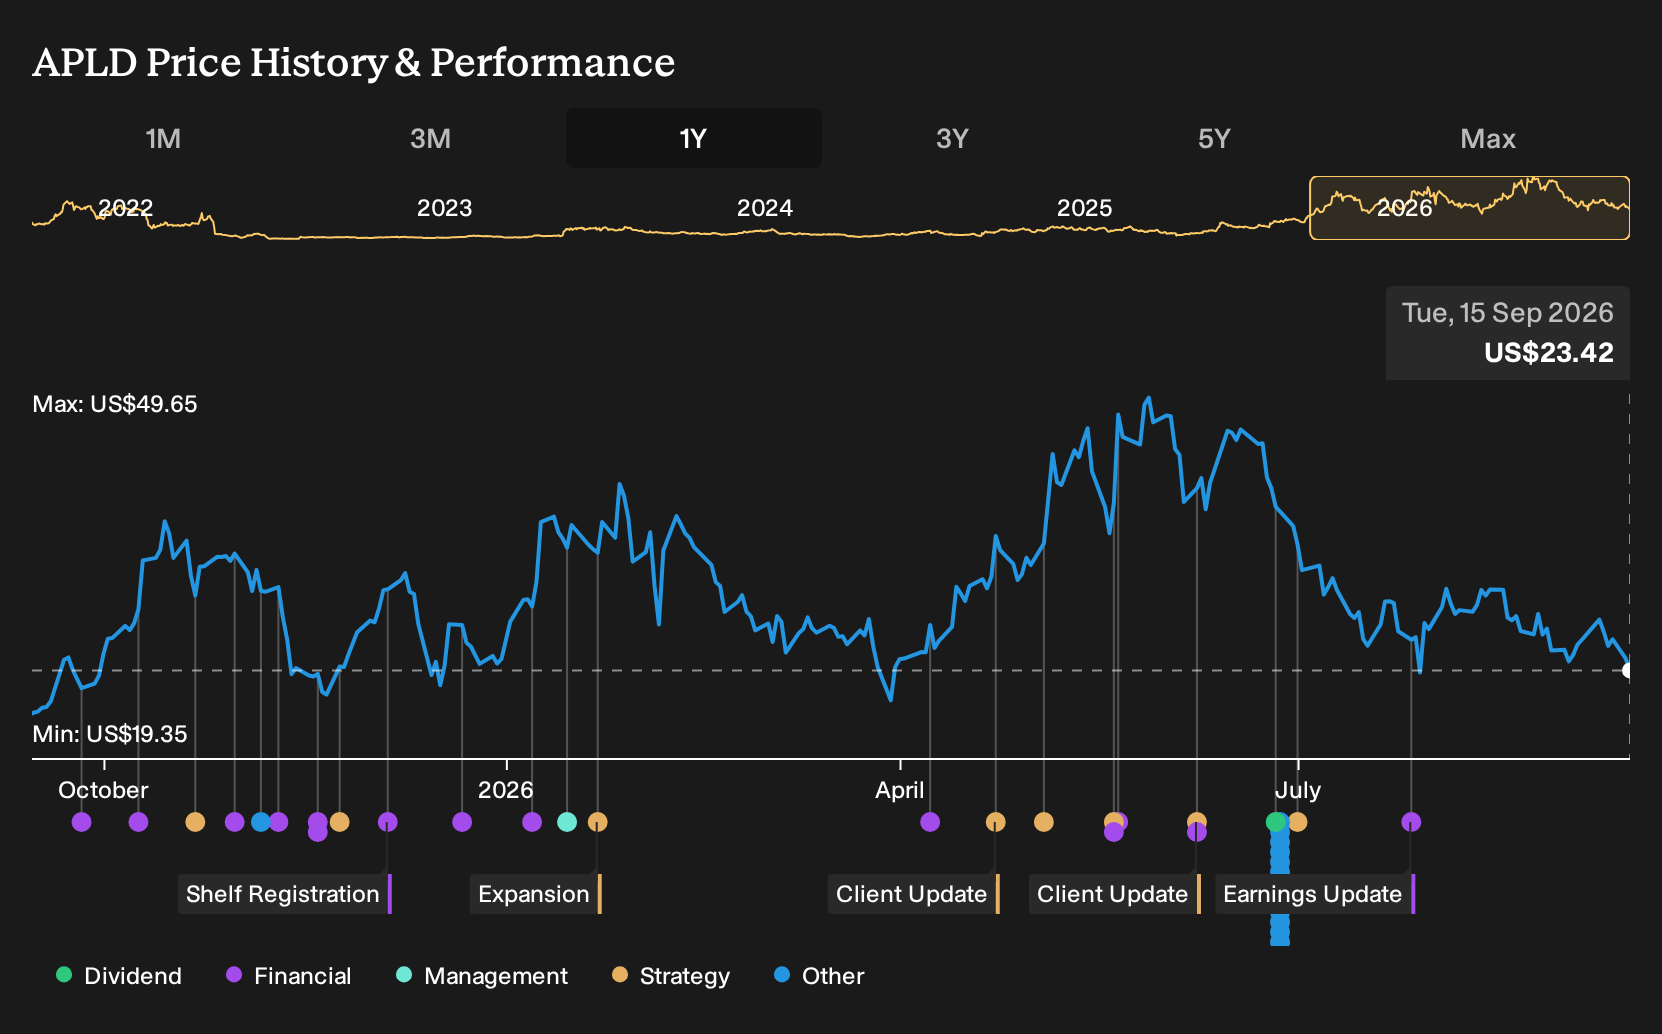
The recent pullback in Applied Digital despite beating expectations keeps the main near term catalyst intact. Investors are still watching for sustained improvement in margins and cash generation from these AI hosting contracts. Balance sheet risk remains the key concern, since expansion is funded largely with higher risk borrowing and the firm has limited cash runway.
The 15 year lease with an investment grade hyperscaler for 200 MW at Polaris Forge 2 is the announcement that really matters here. It reinforces that Applied Digital is not just building on speculation. There is contracted demand tied to specific campuses and delivery schedules that run well into the next decade.
That deal, together with the private senior secured notes due 2031, sharpens the trade off you are weighing as a shareholder. Long duration, sizable revenue commitments support the AI hosting thesis. At the same time, higher leverage, customer concentration and execution risk on projects targeting 2027 and 2028 keep financing terms, cost discipline and utilization the critical catalysts to track.
Applied Digital's current loss of US$119.8 million is set against analyst expectations for earnings of US$117.0 million by 2029. This implies an earnings swing of about US$237 million, while revenue assumptions point to 96.1% yearly top line growth and a forecast of US$2.4b in sales in the same year.
Uncover how Applied Digital's fair value indicates a 213% potential upside to its current price, which could narrow quickly if sentiment turns.
Exploring Other Perspectives
For a very different angle, focus on the most bullish catalyst. Some analysts see Applied Digital’s long-term AI leases turning into much stronger earnings, with revenue forecasts of about US$3.1b and profit of roughly US$1.8b by 2029. That view is far more optimistic than consensus. It also predates this latest AI data center news, so opinions may change as fresh information is incorporated into new models.
Explore 8 other Applied Digital fair value estimates, including one that suggests as much as 353% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Digital's overall financial health at a glance.
Looking For More Ideas Beyond Applied Digital?
If you want to cross check the Applied Digital story against other opportunities, it helps to scan a wider field of companies with different risk and return profiles. The Simply Wall St Screener can surface a range of stocks that match what you care about most, from income resilience to balance sheet strength.
- If stability matters to you, review a 11 resilient stocks with low risk scores that score well on resilience and may help anchor a more volatile portfolio.
- For investors focused on income, look through a curated group of 6 dividend fortresses that combine higher yields with an emphasis on durability.
- If you want to widen the search beyond well known tickers, browse a 16 high quality undiscovered gems that pair stronger fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com