


Medpace Holdings (MEDP) Could Be 16% Overvalued Ahead Of Earnings
Medpace Holdings (MEDP) is back in focus as traders look ahead to an earnings release. Analysts expect the report to show double digit EPS and revenue growth compared with the same quarter last year.
Recent trading reflects that optimism, with Medpace Holdings posting a 4.21% 1-day share price return and a 35.75% 90-day share price return. Its 1-year total shareholder return of 26.43% and 5-year total shareholder return of 235.47% point to momentum that long-term holders have already experienced.
Scan other potential earnings momentum stories alongside Medpace Holdings with a curated list of 16 high quality undiscovered gems that are already putting solid fundamentals to work.
Medpace Holdings has already sprinted higher into this earnings release, which leaves you with a practical fork in the road: lean into the current strength, or wait and see if the valuation offers a better entry after the numbers?
Most Popular Narrative: 16% Overvalued
Medpace Holdings last closed at $620.48, while the most followed narrative fair value sits at $536. According to prajeeshprathap, the gap reflects a business with strong economics but a valuation that already bakes in a lot of optimism.
The balanced conclusion is less promotional than "dominates a profitable niche." Medpace has built a strong position in a difficult-to-replicate part of the CRO market, but its revenue is not locked in, its customers can be financially fragile, and founder control brings related-party governance considerations. At around 35 times management’s 2026 earnings guidance, the business quality is evident; the margin of safety in the share price is less obvious.
See why 5 investors see Medpace Holdings as 16% overvalued.
Result: Fair Value of $536 (OVERVALUED)
Still, Medpace Holdings faces real pressure points if biotech funding tightens or small clients cancel or delay trials. These factors could weaken backlog and stress its premium P/E.
Find out about the key risks to this Medpace Holdings narrative.
Another View on Medpace Holdings Valuation
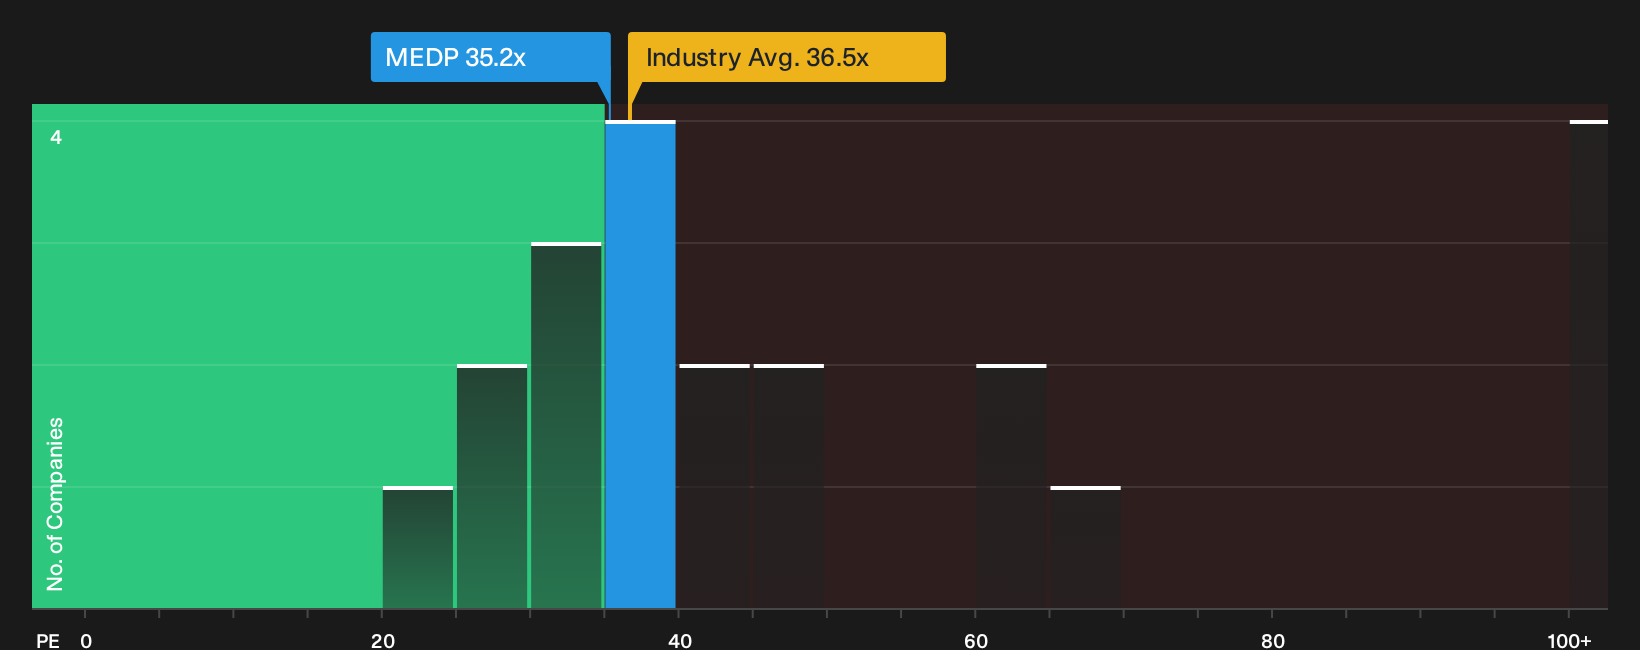
The fair value narrative pegs Medpace Holdings at $536, which points to a stretched price at $620.48. A second lens tells a different story. On a P/E of 35.2x, the stock is described as good value against the global life sciences average of 36.5x and a peer group around 50.8x, yet expensive versus a fair ratio of 22.2x that the market could eventually lean toward. That mix of relative support and fair ratio gap raises a simple question for you as an investor: Is the comfort of trading below peers worth the risk that sentiment shifts closer to that lower fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Medpace Holdings story today. If you want to move fast and build your own stance, start with the 3 key rewards and 1 important warning sign.
Looking for more Medpace Holdings style ideas?
Do not stop with Medpace Holdings. Use the screener to surface fresh candidates now so you are not chasing the next move after it happens.
- Target potential mispricings early by checking the 34 high quality undervalued stocks that line up strong fundamentals with what could be more modest expectations.
- Build a sturdier core to your portfolio by focusing on companies in the list of solid balance sheet and fundamentals (22 results) that pair financial strength with dependable business models.
- Dial down portfolio stress by scanning the 11 resilient stocks with low risk scores that score well on stability and lower downside risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com