


Has Yelp (YELP) Fallen Too Far Below Fair Value On Earnings?
Yelp has had a rough few years in the market, and the slump raises a simple question for investors who still follow the stock. Is the current share price properly reflecting what the business earns today and what those earnings could support over time?
- Over the past 3 years the share price has fallen 50.8%. This puts the focus firmly on whether the earnings profile now lines up with a much lower market value.
- The rollout of OpenAI's GPT-Live-1 into Yelp Host and Hatch may support expectations for higher quality revenue from restaurants and service businesses, which can influence how durable its earnings power looks.
- The analysts covering Yelp have run their own numbers. See what analysts think Yelp's shares could be worth.
The issue now is whether Yelp's current earnings are strong and reliable enough to justify where the stock trades today.
If you want to test the same earnings question you are asking of Yelp across a wider set of companies using AI in different ways, take a look at 76 profitable AI stocks that aren't just burning cash.
Does Yelp Look Undervalued on Earnings?
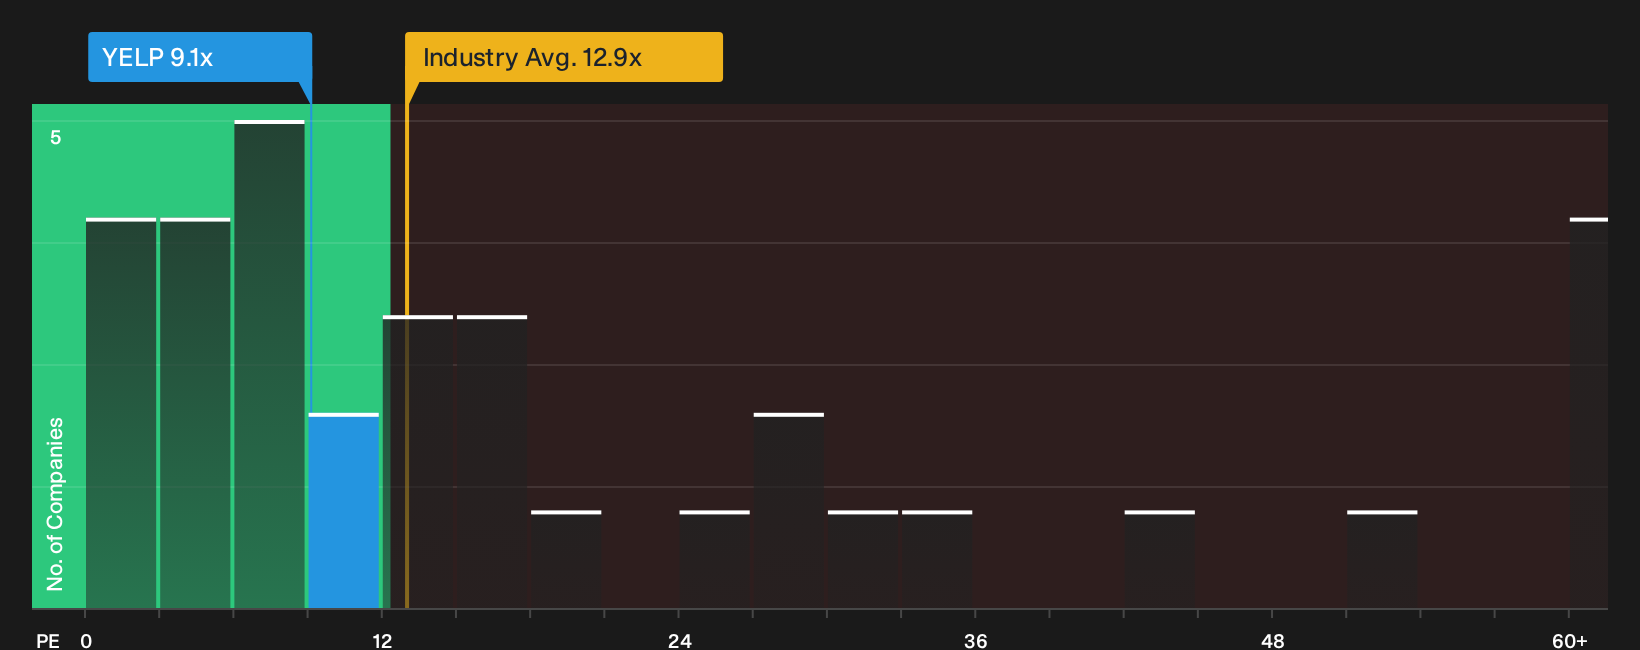
P/E suits Yelp because the business is already profitable and revenues are relatively steady for a mid-cap internet platform. On this yardstick, the stock trades on a P/E of about 9.1x, which is slightly lower than the Interactive Media and Services sector average of roughly 12.9x and a touch under direct peers at around 9.6x.
Because the P/E that would typically fit Yelp based on its financial profile and risk appears higher than where the shares trade now, this framework points to the stock as undervalued on earnings. The recent rollout of GPT-Live-1 into Yelp Host and Hatch adds another angle, because even with that AI push attracting attention, the current P/E still reflects a discount versus what the model suggests as a more normal earnings multiple for the company. Explore the numbers behind Yelp's P/E valuation.
The Yelp Narrative: What Would Justify Today's Price?
Yelp's Simply Wall St Narratives pick up where the P/E puzzle leaves off. They spell out which paths for future growth, profitability and earnings would need to play out for the shares to be worth meaningfully more or less than today’s price, and they turn a single valuation output into a set of assumptions you can follow over time on the Community page.
Bullish and bearish community views on Yelp sit on opposite sides of the valuation line, with each camp focused on a different AI outcome.
Bull case: 20% undervalued
"Strong momentum in AI search API usage and data licensing revenue demonstrates Yelp's growing value as a data partner for emerging AI-powered search players, with a $10 million annual run-rate already achieved and significant upside potential for diversifying and expanding revenue streams..."
Discover why this Narrative puts Yelp at 20% undervalued.
Bear case: 11% overvalued
"The accelerating integration of generative AI and voice assistants is likely to fundamentally shift how consumers search for local businesses and services, reducing reliance on text-based review platforms like Yelp and diminishing user engagement over the long term..."
Explore why this Narrative puts Yelp at 11% overvalued.
For Yelp, the sticker price is only half the story
Before you decide how to treat Yelp in your portfolio, it helps to look at who is actually steering the ship and how their pay packets line up with your interests. See who runs Yelp and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com