


Shake Shack (SHAK) Could Be 27% Below Fair Value On Growth Narrative
Shake Shack (SHAK) has come under scrutiny after a steep share price decline over the past six months. This now sits alongside thin operating margins and limited free cash flow to reinvest in the business.
Recent trading has been rough. The share price has dropped 30.19% year to date and the 1-year total shareholder return is down 41.15%, which suggests sentiment toward Shake Shack has cooled as investors reassess its growth prospects and risk profile.
Seize the chance to compare Shake Shack with other consumer stocks under pressure by scanning our curated list of 16 high quality undiscovered gems.After a slide of this size, some investors lean in and others wait on the sidelines. Does Shake Shack now offer a reasonable entry, or does the math still argue for patience as valuation comes into focus next?
Most Popular Narrative: 27% Undervalued
Shake Shack is trading at $58.27 against a widely followed fair value estimate of $79.70, so the prevailing narrative sees meaningful upside if its execution on growth and margins holds together under closer scrutiny.
The company's strategic focus on urban expansion and accelerated domestic and international store openings, especially in untapped markets and through new formats such as drive-thru and licensed partnerships (e.g., casinos, Panama), directly taps into growing urbanization and demand for experiential fast-casual dining, supporting long-term, system-wide revenue growth. Enhanced digital capabilities (including app-focused promotions and omni-channel marketing platforms) and the adoption of smarter operational tools (e.g., labor scheduling, digital kiosks, kitchen prototyping) are improving efficiency, guest experience, and speed of service, which is already translating into higher restaurant-level margins and is expected to further support net margins over time.
See why 15 investors see Shake Shack as 27% undervalued.
Result: Fair Value of $79.70 (UNDERVALUED)
Still, if beef and other input costs stay elevated, or if traffic softens again without heavy promotions, the upbeat Shake Shack narrative could quickly unravel.
Find out about the key risks to this Shake Shack narrative.
Another View On Shake Shack's Valuation
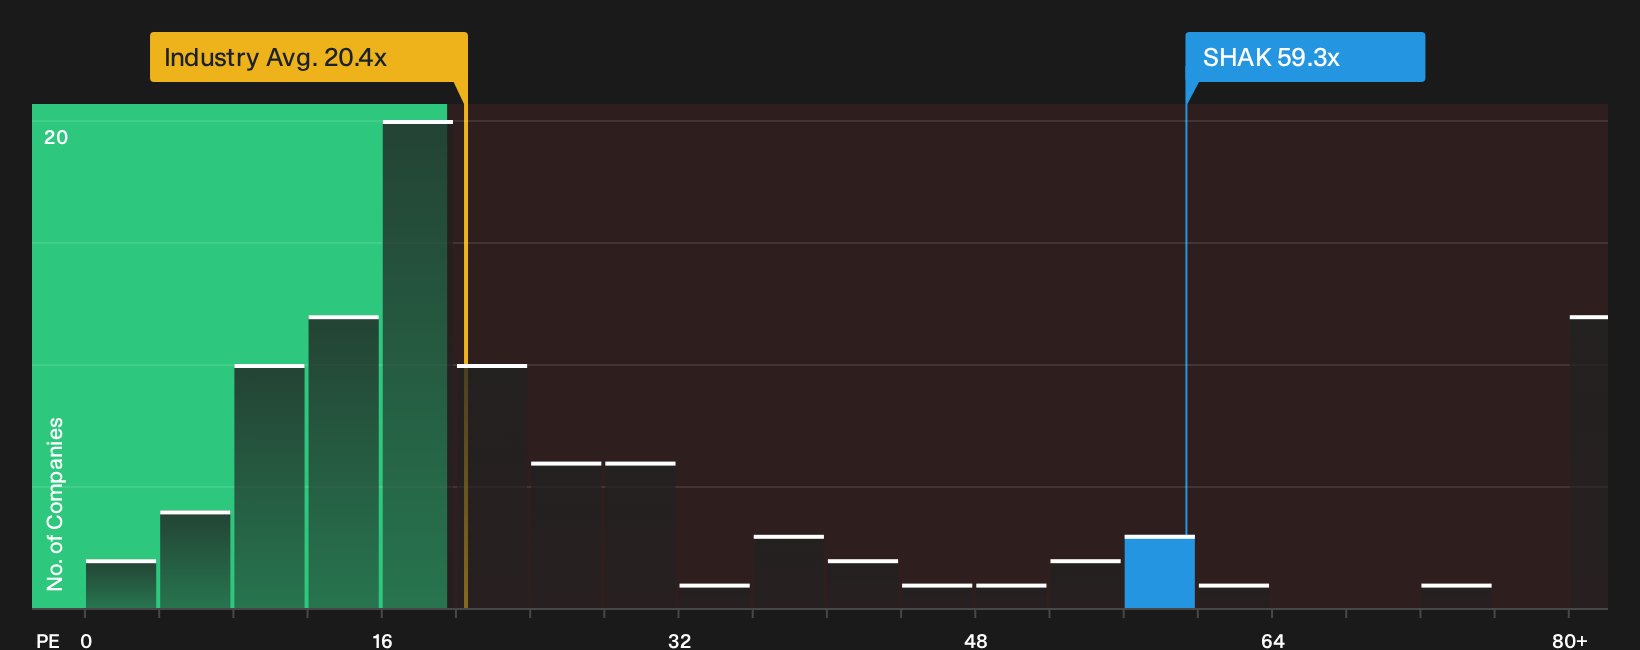
That 27% discount to an $79.70 fair value tells only one story. On earnings, Shake Shack trades on a P/E of 59.3x, compared with a fair ratio of 23.4x, the US Hospitality average of 20.9x, and a peer group around 17.4x. That gap points to real valuation risk if sentiment shifts again.
See what the numbers say about this price in our valuation breakdown, including how the fair ratio could become a reference point if expectations reset, by reading the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the Shake Shack story so far. Use the full data set to pressure test the bullish and bearish cases by reviewing the 3 key rewards.
Looking For More Investment Ideas Beyond Shake Shack?
If Shake Shack has you rethinking your watchlist, use this moment to widen your search with fresh ideas that match your risk and income goals.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (22 results) that combine financial strength with room for future plans.
- Hunt for value opportunities by checking the 34 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them yet.
- Build a steadier income stream by reviewing the 6 dividend fortresses that focus on higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com