


Progressive (PGR) Stock Looks About Right Given Its Earnings Power
Progressive has delivered a powerful long run for shareholders, yet the current share price raises a clear question for anyone looking at the stock today. After such a strong stretch, the issue is whether the valuation that investors now pay is adequately supported by the insurer's earnings power.
- Over the past 5 years, Progressive has returned 168.7%, which puts a lot of weight on the idea that its profit engine can justify that kind of compounding.
- The business model leans heavily on underwriting discipline and investment income, so any shift in claim costs or pricing power can reshape what investors are really paying for in terms of earnings.
- Your read on Progressive is one view; the desks covering it have another. See what analysts think Progressive's shares could be worth.
The issue now is whether Progressive's current share price around US$221 reflects an earnings profile that still stacks up against the Fair Ratio benchmark.
If you want to test the same earnings question you are asking of Progressive across a wider field, compare it with 34 high quality undervalued stocks.
Is Progressive Fairly Priced on Earnings?
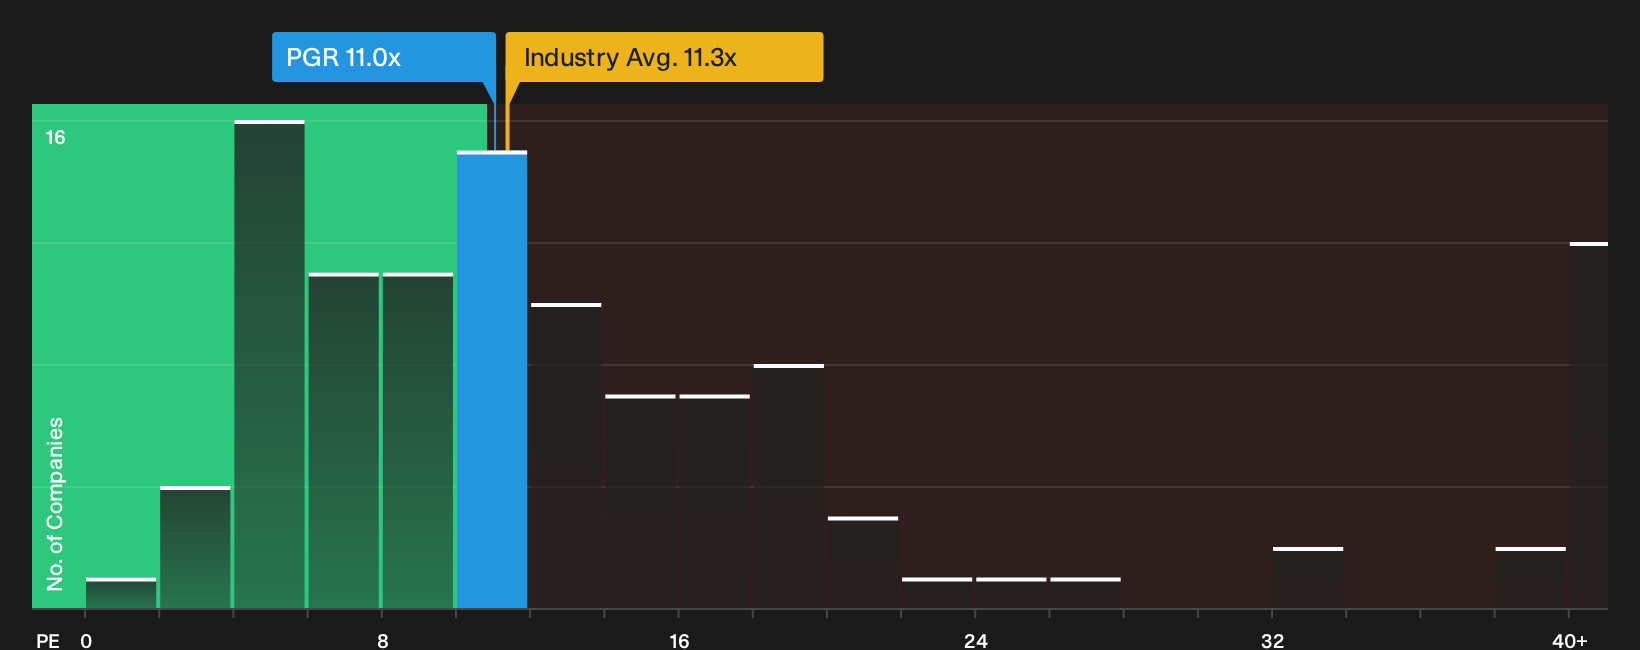
P/E works well for Progressive because earnings sit at the center of how investors judge an insurer that depends on underwriting results and investment income. On this lens, the stock changes hands at about 11.0x earnings, which is very close to the Insurance sector average of roughly 11.3x.
Peers in the same space trade nearer 8.3x, so Progressive carries a premium to that group, yet the current P/E lines up with the level suggested by the Fair Ratio model that blends the company’s growth outlook, profitability profile and risk. That keeps the current earnings multiple more in the “about right” camp than clearly cheap or expensive, and leaves the real question on how durable those earnings prove to be over time. Explore the numbers behind Progressive's P/E valuation.
The Progressive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Progressive valuation question leaves off. They spell out which paths for Progressive's future margins, policy growth and earnings would need to play out for the stock to look meaningfully higher or lower than today. Each one treats fair value as a thesis about the business that you can keep tracking over time instead of a one-off snapshot.
Progressive splits opinion, with one camp arguing its edge in pricing and data is underappreciated, while the other worries the auto cycle and regulation cap what investors should pay.
Bull case: 20% undervalued
"Progressive's early and aggressive investments in telematics and usage-based insurance uniquely position it to capture the accelerating consumer shift to personalized, digital-first insurance products."
Discover why this Narrative puts Progressive at 20% undervalued.
Bear case: 12% overvalued
"Persistent inflation in auto repair, labor, and healthcare costs may continue to outpace rate increases, while ongoing state-level regulatory scrutiny can further restrict pricing flexibility."
Explore why this Narrative puts Progressive at 12% overvalued.
Progressive's price is only one piece of the decision
Valuation frames where Progressive trades today, yet the expectations built into professional earnings projections a few years out offer a separate lens on what you are really paying for. Explore where analysts expect Progressive to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com