


BCE (TSX:BCE) Stock Still Looks Undervalued Following Bell AI Fabric Expansion
BCE Inc. has spent the past few years under pressure, yet the stock still attracts investors who care about dependable earnings. With the share price around $31.90 after a mixed return pattern, the question now is whether what you pay for BCE is in line with what the business earns.
- Over 5 years the share price has fallen 31.1%, which puts the focus squarely on whether current earnings can support a long term recovery case.
- The planned expansion of Bell AI Fabric in Saskatchewan, together with management’s focus on higher return assets and dividend sustainability, may support expectations for steadier earnings and cash generation that matter for valuation.
- The analysts covering BCE have run their own numbers. See what analysts think BCE's shares could be worth.
For investors, the debate is whether BCE’s current share price is justified by the earnings power of the business today.
If you want to test the same earnings question you are asking of BCE across a wider set of companies, scan through 3 high quality undervalued stocks.
Is BCE a Bargain on Earnings?
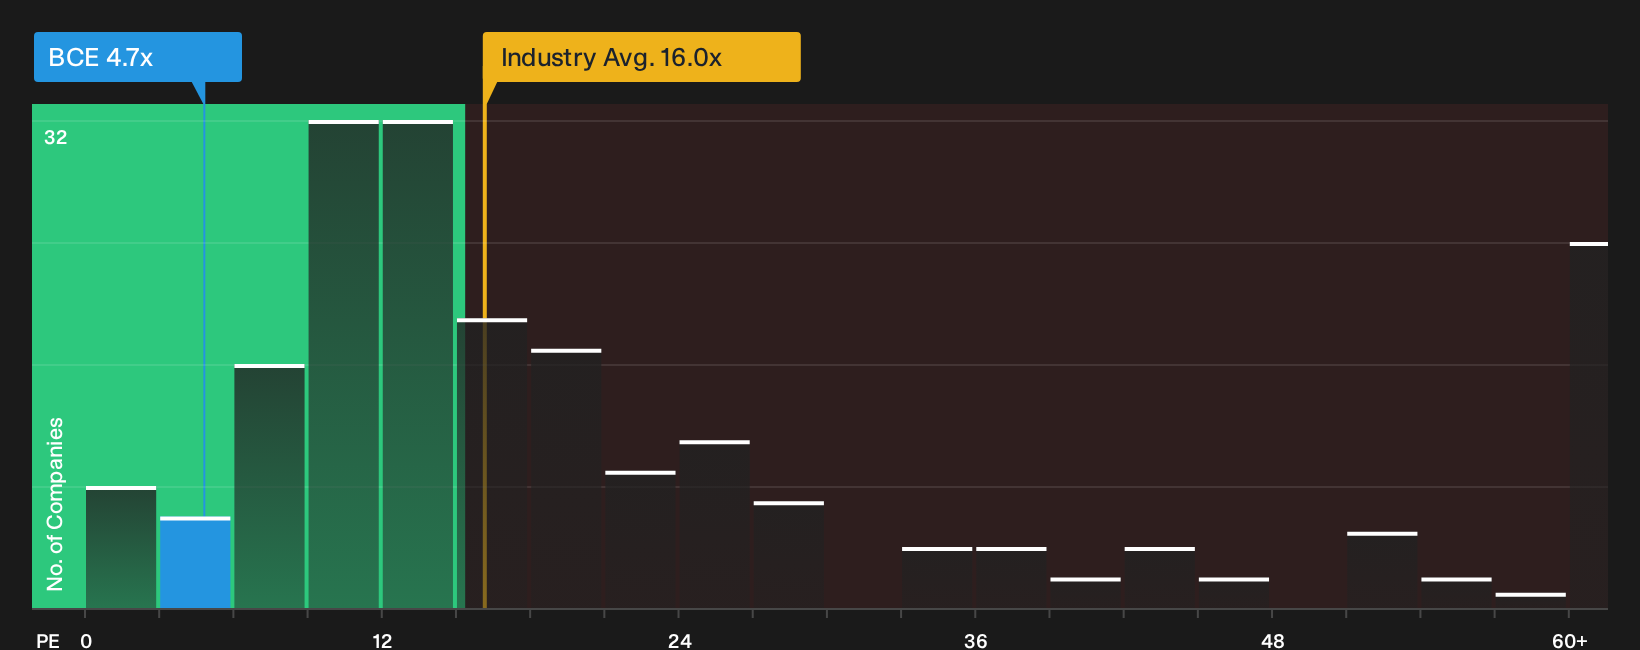
The P/E ratio works well for BCE because investors watch its earnings stream closely when they think about the dividend and capital spending profile. On current numbers the stock trades on about 4.7x earnings, which is far below the Telecom sector average of roughly 16.0x and well under peers at about 20.4x. For a large incumbent like BCE that gap signals that the market is applying a clear discount to each dollar of profit today.
The fair-value model, which adjusts for BCE’s growth setup, margins, size and risk, points to a higher P/E than where the shares trade, so the current multiple screens as undervalued against that tailored yardstick. Because the Bell AI Fabric expansion and related Saskatchewan investment plans are capital heavy, the low P/E suggests investors are not paying up for those projects despite the attention they have drawn. Explore the numbers behind BCE's P/E valuation.
The BCE Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that valuation gap around BCE and spell out the future conditions on growth, margins and earnings that would need to hold for the stock to trade meaningfully higher or lower than today’s price, all set out on the Community page. Each scenario is framed as a thesis about BCE's fair value that can be revisited over time, so you can see how the argument holds up as new information arrives.
One of the top community narratives on BCE: roughly fairly valued
"BCE's strategic pivot toward enterprise technology, particularly its role as the backbone of Canada's AI ecosystem through Bell AI Fabric, introduces new, unregulated revenue streams and high-growth free cash flow…"
Discover why this Narrative puts BCE at roughly fairly valued.
Before you act on BCE's valuation, there is one more angle to weigh
Price, earnings and plans for Bell AI Fabric only tell part of the story for BCE. The decisions and incentives of the people in charge can shift how those numbers play out over time. See who runs BCE and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com