


Bayer (XTRA:BAYN) Stock Still Looks Like A Bargain As It Jumps 81%
Bayer has had a strong run over the past year, which puts fresh attention on whether the current share price lines up with what its sales can support. With the stock recently closing at €48.71, investors are asking how much of the recent news flow is already reflected in the revenue multiple.
- The share price has gained 81.3% over the past 12 months, which increases the focus on how much revenue the stock is being asked to support.
- Regulatory progress such as the accelerated approval for HYRNUO in HER2-mutated lung cancer and ongoing work in crop science and pharmaceuticals can shape expectations for Bayer's future sales mix and the timing of revenue from new products.
- There is a second opinion on Bayer worth weighing. See what analysts think Bayer's shares could be worth.
The issue now is whether Bayer's current market value is justified by its sales when set against the Fair Ratio benchmark.
If you are weighing whether Bayer’s €48.71 share price is justified by its sales, it can help to compare it with other companies screened for 194 high quality undervalued stocks.
Is Bayer a Bargain on Sales?
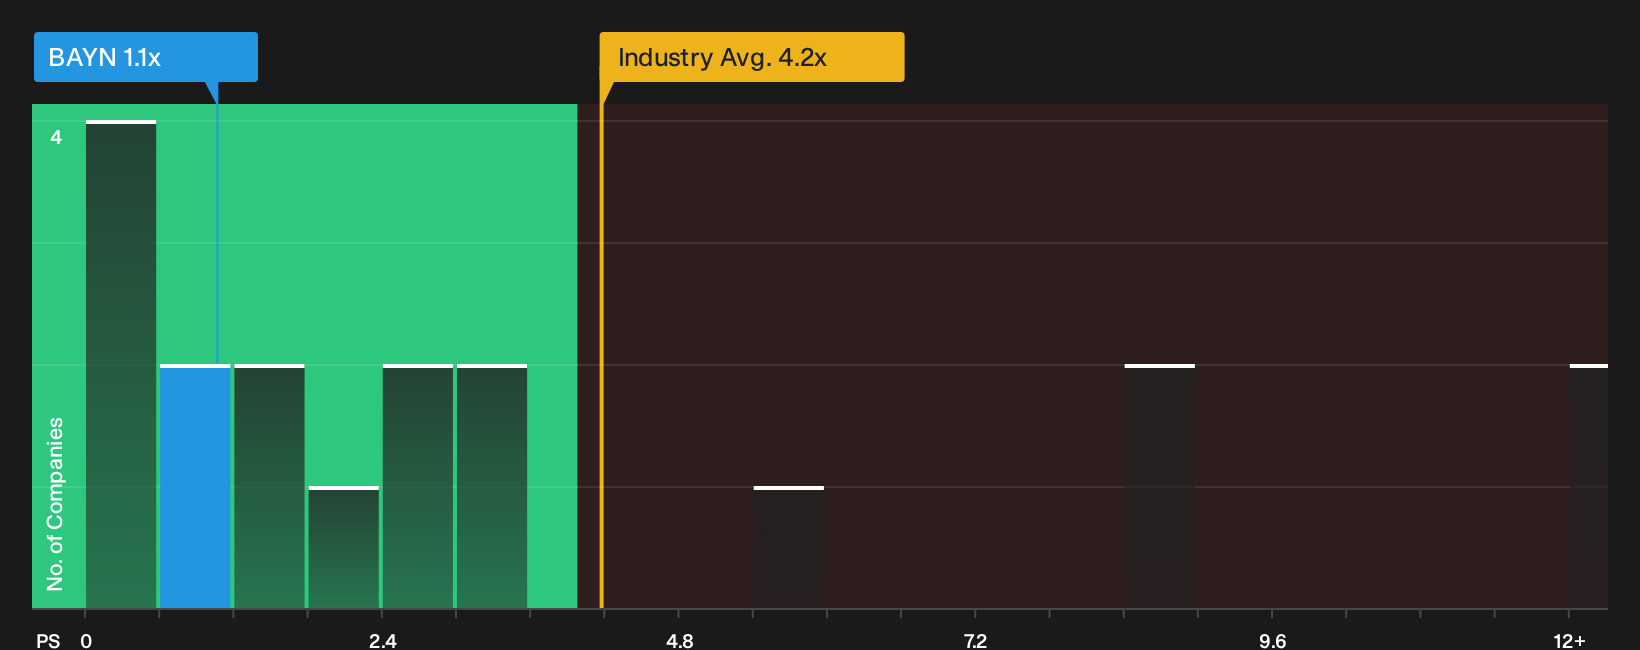
The P/S ratio suits Bayer because investors are paying close attention to how the share price stacks up against the revenue base while legal and product headlines keep coming. At the current level, the stock trades on a P/S of about 1.1x, compared with a pharmaceuticals industry average of roughly 2.6x and a peer group around 3.7x. This means the market is paying a lower price for each euro of Bayer’s sales than for many similar businesses.
The Fair Ratio model, which blends factors like Bayer’s margins, size, sector and risk profile into a tailored benchmark, also indicates that the current P/S sits below the level implied by those fundamentals. On this metric, the shares screen as undervalued. Because the Roundup settlement process still hangs over the group, the discount suggests investors are treating legal risk as a key reason to demand a lower revenue multiple even after recent drug approvals and pipeline updates. Explore the numbers behind Bayer's P/S valuation.
The Bayer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Bayer pick up where the P/S discussion leaves off by spelling out which paths for Bayer's future revenue, profitability and earnings would need to play out for the current share price to look either too low or too high. Instead of a single output from a ratio or model, Narratives describe the future those numbers depend on so you can see what would need to occur and monitor whether that picture still matches reality over time on the Community page.
Bayer attracts two very different storylines right now, with one group focused on litigation clean up and another worried that the turnaround ask is still high.
Bull case: 14% undervalued
"Progress on litigation containment, including large case settlements at low average cost, strategic provision management, and an articulated multi-pronged legal strategy with a target to largely resolve legacy glyphosate and PCB exposures by end-2026…"
Discover why this Narrative puts Bayer at 14% undervalued.
Bear case: 22% overvalued
"O mercado vê a Bayer com um misto de cautela e otimismo moderado, com o preço-alvo médio das ações girando em torno de €31-35 por ação…"
Explore why this Narrative puts Bayer at 22% overvalued.
One more Bayer checkpoint that belongs beside the valuation math
Price multiples and legal overhangs frame the story today, yet analyst projections for Bayer a few years out offer a separate reference point that lets you test whether the current market view lines up or drifts apart. Explore where analysts expect Bayer to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com