


Learn Why The Bull Case For ResMed Stock Could Change Following Earnings Beat
- ResMed reported Q4 2026 results with revenue of $1.46b, up 8.6% year on year, and an adjusted EPS beat alongside operating margin pressure from higher R&D and supply chain costs.
- The medical device group delivered the weakest revenue performance against expectations in its sector, putting its spending on product development and logistics under sharper investor scrutiny.
- Now the focus shifts to how ResMed's long term investment narrative holds up against Q4 margin compression driven by heavier R&D spending.
ResMed Investment Narrative Recap
To own ResMed, you need to be comfortable with a business leaning into higher R&D and supply chain spend to support its sleep and breathing devices plus software platforms. The key near term swing factor is whether that heavier investment translates into steadier top line growth without further squeezing operating margins after the recent Q4 compression.
The biggest current risk sits on the cost side. If elevated R&D, logistics and regulatory related expenses persist without clear operating leverage, earnings could lag even with revenue at $1.46b and 8.6% year on year growth. The latest quarter nudges this risk higher but does not fundamentally alter ResMed's demand drivers.
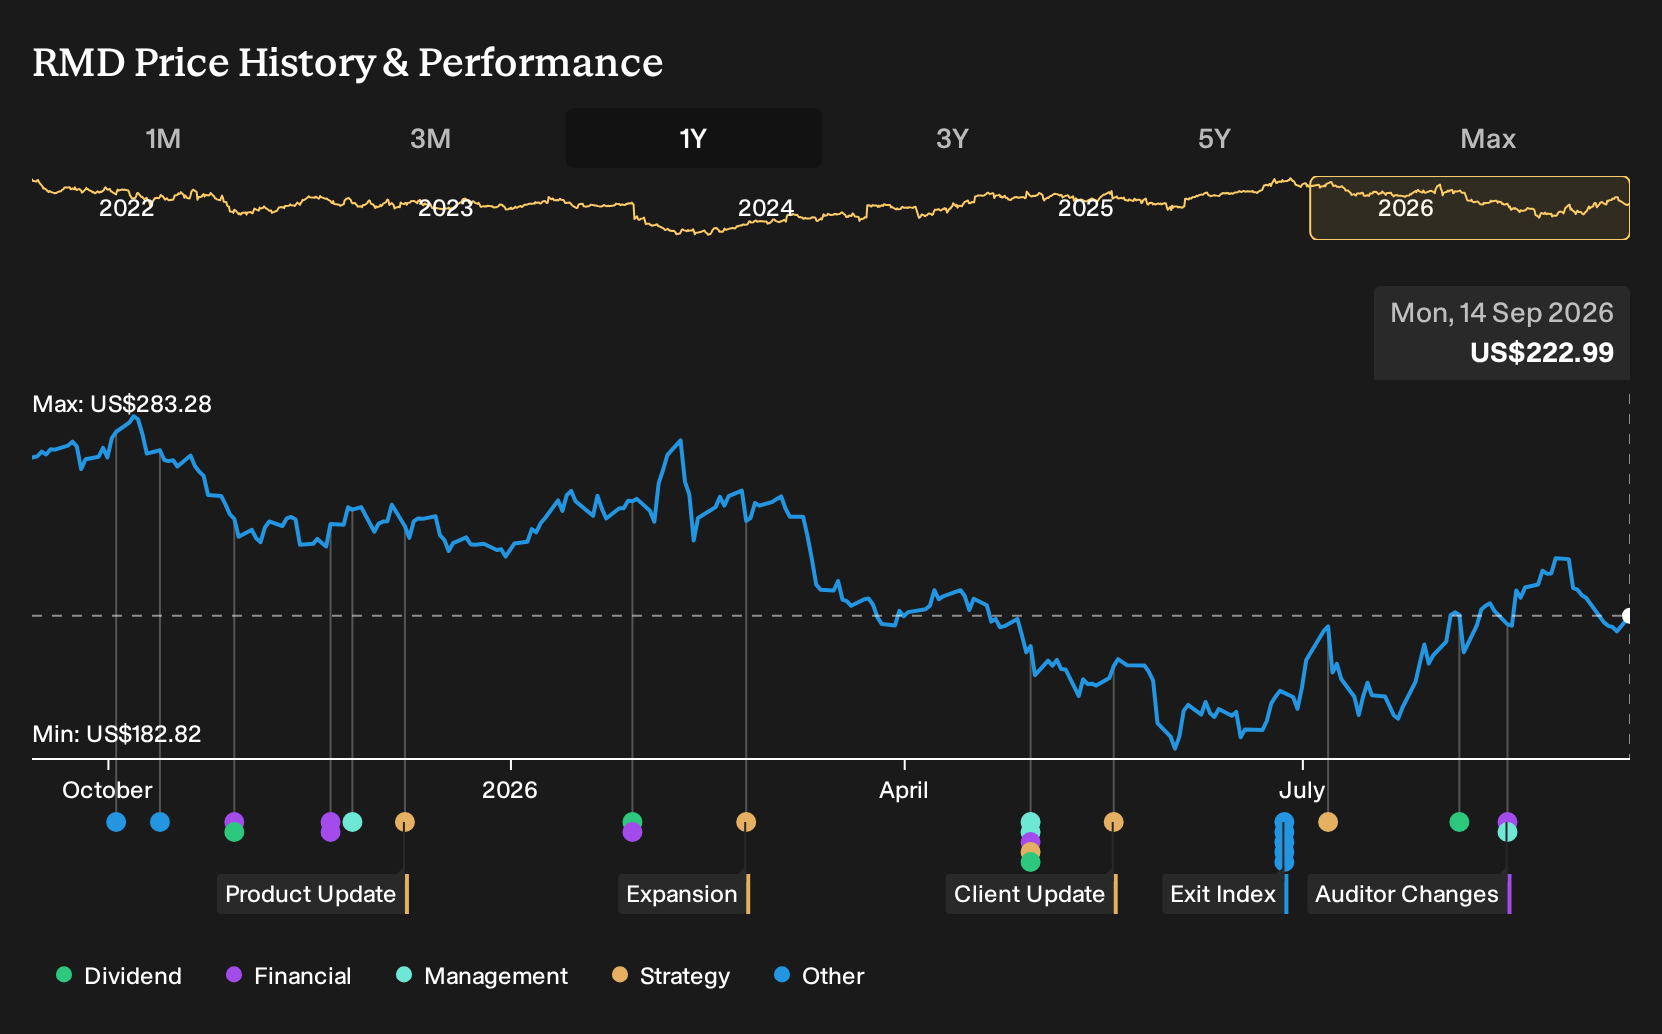
The Q4 2026 update is the relevant catalyst here. ResMed delivered 8.6% year on year revenue growth to $1.46b with an adjusted EPS beat, yet the stock still slipped 2.3% after the release and 5.1% on August 7 as investors reacted to margin pressure from higher R&D and supply chain costs.
That mix of solid revenue and EPS against weaker operating leverage feeds directly into how you think about ResMed's execution from here. A big part of the thesis rests on scaling its cloud connected devices and Residential Care Software while maintaining attractive net margins. Persistent cost inflation or tougher reimbursement and competition would be the catalysts that most threaten that balance.
What Analysts Are Baking Into The ResMed Story
ResMed's narrative projects US$6.5b revenue and US$1.8b earnings by 2029. This assumes 5.4% yearly revenue growth and about US$300m earnings increase from US$1.5b today.
Analyst models effectively ask you to accept a slow and steady build rather than a sharp snap back after the Q4 2026 margin squeeze. Revenue is pencilled in to rise at 5.4% a year over the next three years, with profit margins nudging from 27.4% to 27.5% by 2029. That framing fits a business that leans on recurring device usage and software fees rather than one that chases rapid volume spikes.
Earnings expectations work the same way. Consensus points to profit growing from US$1.5b today to US$1.8b by 2029, with analysts also assuming earnings per share of US$13.86 helped by a 0.93% annual reduction in share count. For you, the key question is whether the heavier R&D and supply chain spend seen in Q4 can co-exist with that modest margin uplift or whether extra costs keep biting into that earnings bridge.
On these numbers, ResMed would be generating US$6.5b of revenue and US$1.8b of earnings in 2029 and trading on a P/E of 24.3x, up from 18.2x today and still below the current 26.4x multiple for the broader AU medical equipment sector. That valuation setup assumes investors remain willing to pay a premium for a business with cloud connected hardware, subscription like software and a long runway of underdiagnosed sleep apnea patients, even with ongoing regulatory and reimbursement risk.
Uncover why ResMed's fair value indicates an 8% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on ResMed focuses on GLP 1 weight loss drugs as a real risk rather than a tailwind. The most cautious analysts were already modeling only 3.3% yearly revenue growth to about US$6.2b and earnings of US$1.7b by 2029 before this Q4 margin squeeze. That more muted script might shift again after these results, so consider this as one of several viewpoints worth comparing.
Explore 4 other ResMed fair value estimates, including one that suggests it could be worth just $224.10.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ResMed research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ResMed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ResMed's overall financial health at a glance.
Looking For More Investment Ideas Beyond ResMed?
If the ResMed story has you thinking about portfolio gaps, use this moment to widen your opportunity set. The Simply Wall St Screener can help you quickly surface other businesses with cash flow profiles, balance sheets and risk levels that match what you are looking for next.
- For investors who want income that does more of the heavy lifting, scan for companies offering resilient payouts through the 6 dividend fortresses.
- If capital preservation sits higher on your priority list right now, filter for sturdier candidates with the 11 resilient stocks with low risk scores.
- When you are ready to hunt for potential future leaders before they become widely followed, shortlist prospects using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com