


How Lawsuits And CFO Exit At Pentair (PNR) Have Changed Its Investment Story
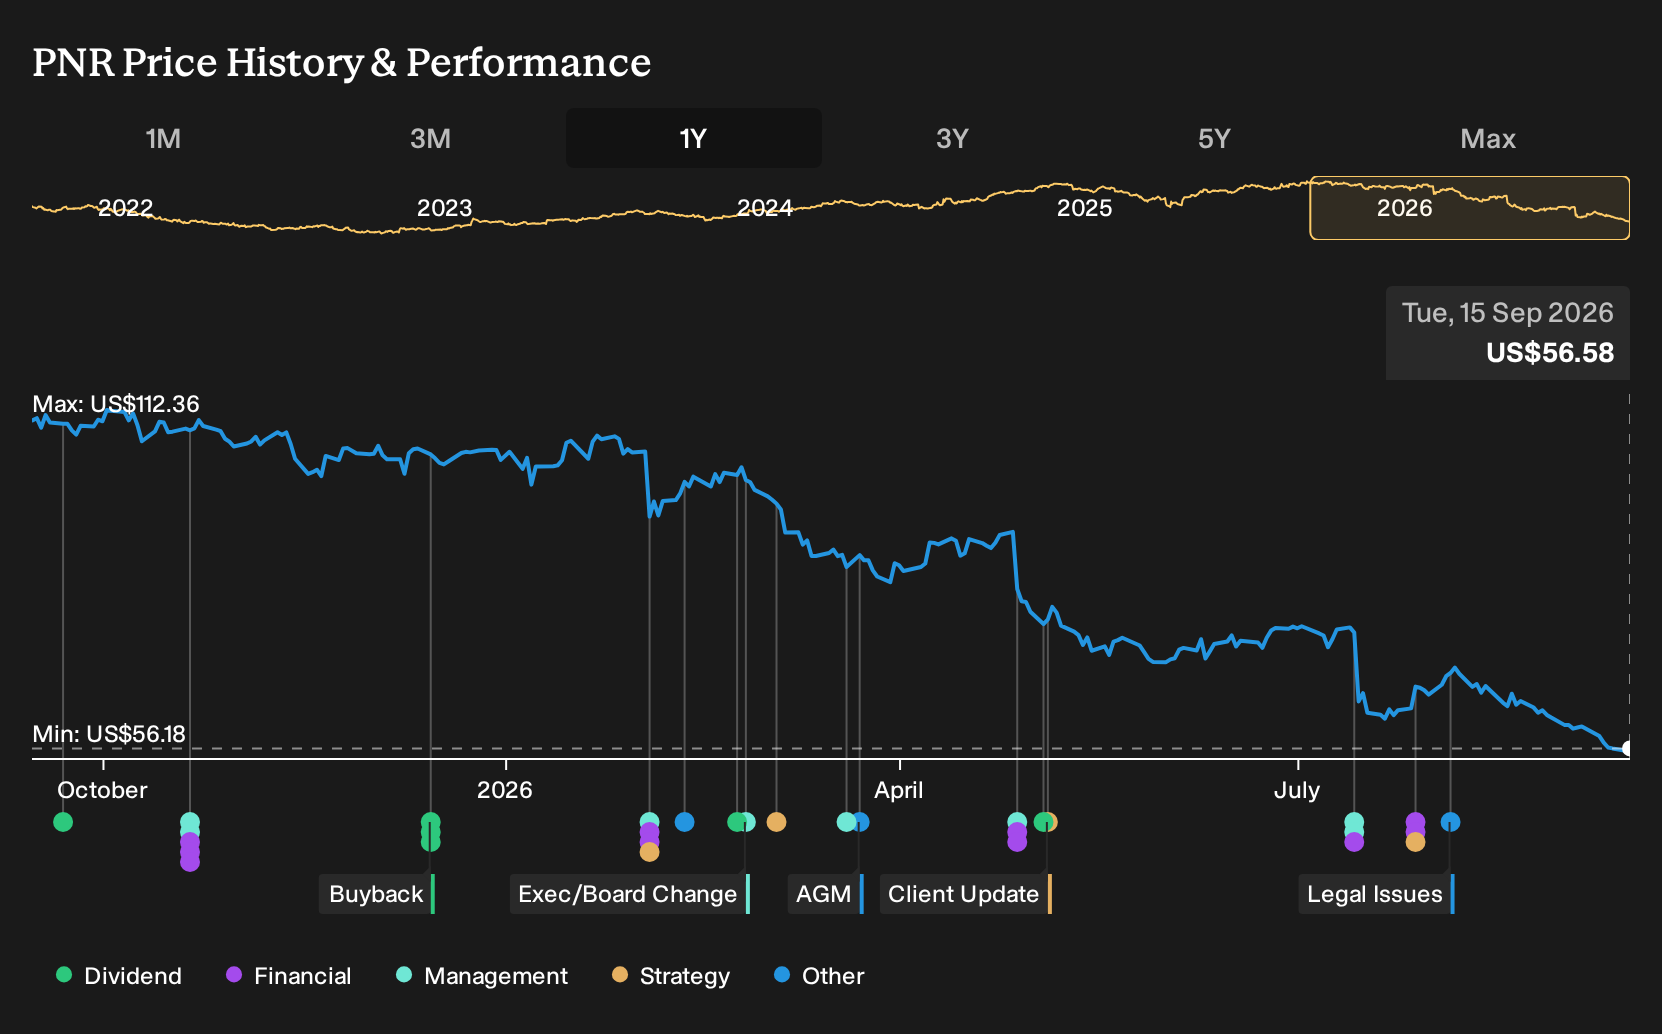
- Pentair disclosed in July 2026 that Pool segment sales and income were hit by inventory destocking, cut its 2026 guidance, and announced the immediate departure of its Chief Financial Officer, prompting several securities class action lawsuits over prior disclosures.
- The wave of litigation centers on whether Pentair accurately described channel inventory and Pool demand, raising fresh questions about how management oversight and sales practices align with the long-term water technology narrative that investors had been focused on.
- Attention now shifts to how Pentair's longer term water technology investment narrative holds up against allegations over Pool destocking disclosures and CFO turnover.
Compare Pentair's legal and inventory issues with those of other water and industrial peers by reviewing our curated list of list of solid balance sheet and fundamentals (22 results).
Pentair Investment Narrative Recap
Pentair is still largely an investment in long term demand for water treatment, filtration, and pool equipment, backed by earnings that have grown 6.1% per year over the past 5 years. For a shareholder, the key belief is that industrial and infrastructure water projects and aftermarket filtration can offset pressure in cyclical residential pools.
The recent disclosure of Pool destocking, guidance cuts, and the CFO exit puts the near term focus squarely on inventory clean up and channel health. The biggest near term risk is that residential pool equipment volumes stay weak while price increases lose traction, which would pressure margins and limit any quick sentiment reset.
The most relevant recent announcement is Pentair’s July 14, 2026 pre release. It flagged Pool segment destocking, a roughly $170 million hit tied to the channel, a sharp guidance reduction, and the immediate CFO departure. That update also triggered several securities class actions and a one day share price drop of about 15% on July 15, 2026.
For you, that disclosure is now the reference point for near term catalysts. Evidence that Pool sell through is stabilizing, that inventory in the channel is reverting to healthier levels, and that the broader Flow and Water Solutions segments stay on track would support the longer term water technology story. Prolonged legal uncertainty, slower Pool volume recovery, or further forecast resets would keep operational risk in focus.
Pentair's current analyst narrative points to forecast revenues of $4.5b and projected earnings of $933.3 million by 2029, based on an assumed 4.1% yearly revenue growth rate and an earnings increase of about 47% from the $635.5 million reported today.
Uncover how Pentair's fair value indicates a 35% potential upside to its current price before that gap closes.
Exploring Other Perspectives
One alternate view on Pentair focuses on the risk that transformation and 80/20 programs have already captured the easiest savings. That is why the most cautious analysts were only assuming 3.5% yearly revenue growth and about US$871.2 million of earnings by 2029. Today's lawsuits and guidance reset may push those assumptions even lower or prompt fresh scenarios. Explore these differing viewpoints so you can judge where your own expectations sit between the consensus view and the bearish end of the range.
Explore 4 other Pentair fair value estimates, including one that suggests it could be worth just $60.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Pentair research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pentair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pentair's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pentair?
Once you have a view on Pentair, it can help to widen the lens and see how other opportunities line up on quality, risk, and income potential using the Simply Wall St Screener.
- If capital preservation sits high on your list, start with a basket of companies that score well on resilience through our 11 resilient stocks with low risk scores.
- If you care most about finding financially robust businesses, then compare Pentair with a wider list of solid balance sheet and fundamentals (22 results) that emphasises strong balance sheets and solid fundamentals.
- If income is a priority for your portfolio, scan for reliable cash distributors through a curated 6 dividend fortresses that focuses on higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com