


Emerson Electric (EMR) Could Be 14% Below Fair Value On Growth Narrative
Emerson Electric (EMR) has jumped onto many investors' screens after appearing among the most searched stocks on Zacks.com, just as earnings estimates for the industrial software group are being revised higher.
Recent trading tells a mixed story for Emerson Electric. The 1 month share price return is down 9.91% and the stock is off 3.38% over the past week, yet the year to date share price return of 8.23% sits alongside a 1 year total shareholder return of 15.72% and a 5 year total shareholder return of 73.17%. This points to longer term momentum still in place despite near term volatility.
Scan for other industrial names showing similar earnings momentum and screening interest by comparing Emerson Electric with our curated list of 34 high quality undervalued stocks.
Bulls point to Emerson Electric’s earnings momentum and long term returns. Bears see a stock that has already run and recently pulled back. Which side does the current valuation lean toward next?
Most Popular Narrative: 14% Undervalued
Emerson Electric last closed at $147.00, while the most followed narrative assigns a fair value of $171.81 based on long cycle project exposure and software economics. That gap puts the focus squarely on how LNG, power and automation demand could support the current setup.
Large-scale investments in power generation, LNG, and life sciences driven by rising energy security concerns, electrification, and sustainability initiatives are driving significant greenfield and modernization projects, particularly in regions like North America, Asia, and the Middle East. This is visible in sharply higher orders and is expected to continue supporting revenue and earnings growth over the coming years.
See why 50 investors see Emerson Electric as 14% undervalued.
Result: Fair Value of $171.81 (UNDERVALUED)
Still, Emerson Electric’s story can break if large LNG and power projects face delays, or if tariffs and currency swings pressure profitability harder than analysts expect.
Find out about the key risks to this Emerson Electric narrative.
Another View: Emerson Electric On Earnings Multiples
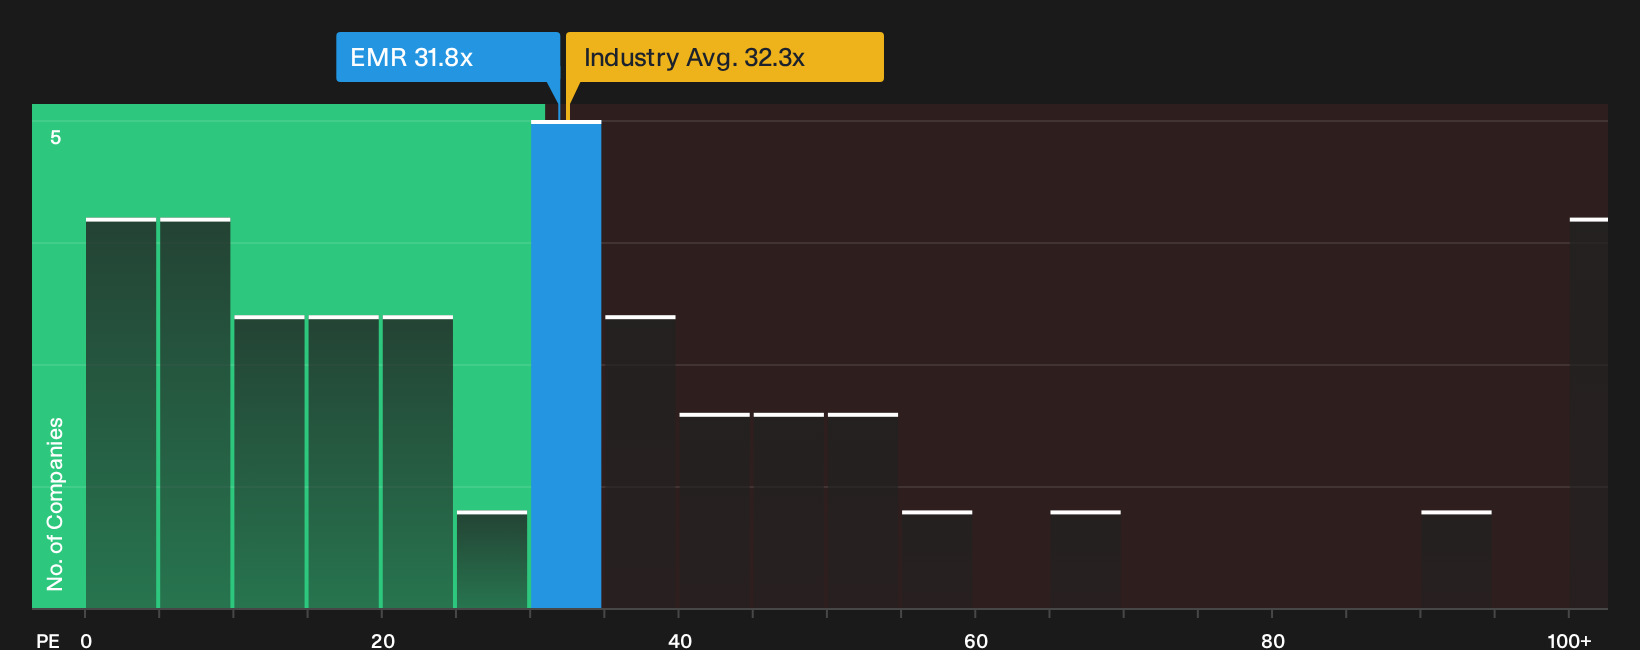
There is a different message in the plain P/E math. Emerson Electric trades on 31.8x earnings, slightly below the US Electrical sector at 32.3x and well under the 41.2x peer average, yet above its own fair ratio of 30.3x. That mix hints at some valuation risk as much as opportunity, so which side do you think the market closes in on next?
To see how those earnings multiples stack up in more detail, take a closer look at our valuation breakdown for Emerson using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Emerson Electric is split, which is exactly when it helps to move fast, dig into the data, and decide where you stand. To weigh both the concerns and the potential upside in one place, start with the 4 key rewards and 2 important warning signs.
Looking for more Emerson Electric investment ideas?
If Emerson Electric has your attention, do not stop here. Widen your watchlist now and give yourself more options before the next setup appears.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing valuations using the 34 high quality undervalued stocks.
- Lock in potential income streams by checking out companies with robust payouts and yields through the 6 dividend fortresses.
- Prioritise capital protection first by focusing on financially resilient businesses using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com