


Is Daido Steel (TSE:5471) Fairly Valued Following Permanent Magnet Market Growth Hopes?
Fresh research on the global permanent magnets market has put Daido Steel (TSE:5471) back in focus for investors, as rising demand from electric vehicles, renewable energy, automation, and robotics highlights its role as a key supplier.
The latest move in Daido Steel’s share price, up 2.01% on the day to ¥2,331.5, comes after a year-to-date share price return of 44.41% and a 1-year total shareholder return of 82.62%. This points to strong momentum rather than a short-lived bounce.
Scan other permanent magnet players with similar momentum by running a targeted screen of 28 best rare earth metal stocks, aligned with the same electric vehicle and renewable energy tailwinds driving interest in Daido Steel.
After a 44.41% gain this year and a 3 year total return close to 2x, Daido Steel now faces a harder question: does the current valuation still leave enough upside to justify the risk from here?
Price-to-Earnings of 13.2x: Is it justified for Daido Steel?
On earnings, Daido Steel trades on a P/E of 13.2x, which sits below the broader JP market but above its closest metals and mining peers.
The P/E ratio compares the current share price with net profit per share and gives you a rough sense of how much investors are paying for each unit of earnings. For a diversified steel and materials producer like Daido Steel, it is a quick way to line up the stock against the wider Tokyo market and its own sector.
At 13.2x, the stock is priced a little cheaper than the JP market average P/E of 13.8x. Yet it trades at a premium to both the domestic metals and mining industry on 11.1x and the peer group average on 11.9x. The estimated fair P/E of 15.2x is higher than where the shares change hands today. This suggests the multiple could move closer to that level if the market continues to accept the recent track record of 5.1% annual earnings growth over five years and an improvement in net profit margin from 4.9% to 5.9%.
Explore the SWS fair ratio for Daido Steel.
Result: Price-to-Earnings of 13.2x (ABOUT RIGHT)
Still, the narrative around Daido Steel can be affected by weaker demand for specialty steel and magnetic materials, or by higher input costs compressing already modest margins.
Find out about the key risks to this Daido Steel narrative.
Another view on Daido Steel’s valuation
The P/E points one way, but the SWS DCF model pulls in the opposite direction. At ¥2,331.5, Daido Steel trades well above the model’s estimate of future cash flow value at ¥1,392.43. This frames the shares as overvalued on this lens and raises a simple question for you: Which signal matters more?
Look into how the SWS DCF model arrives at its fair value.
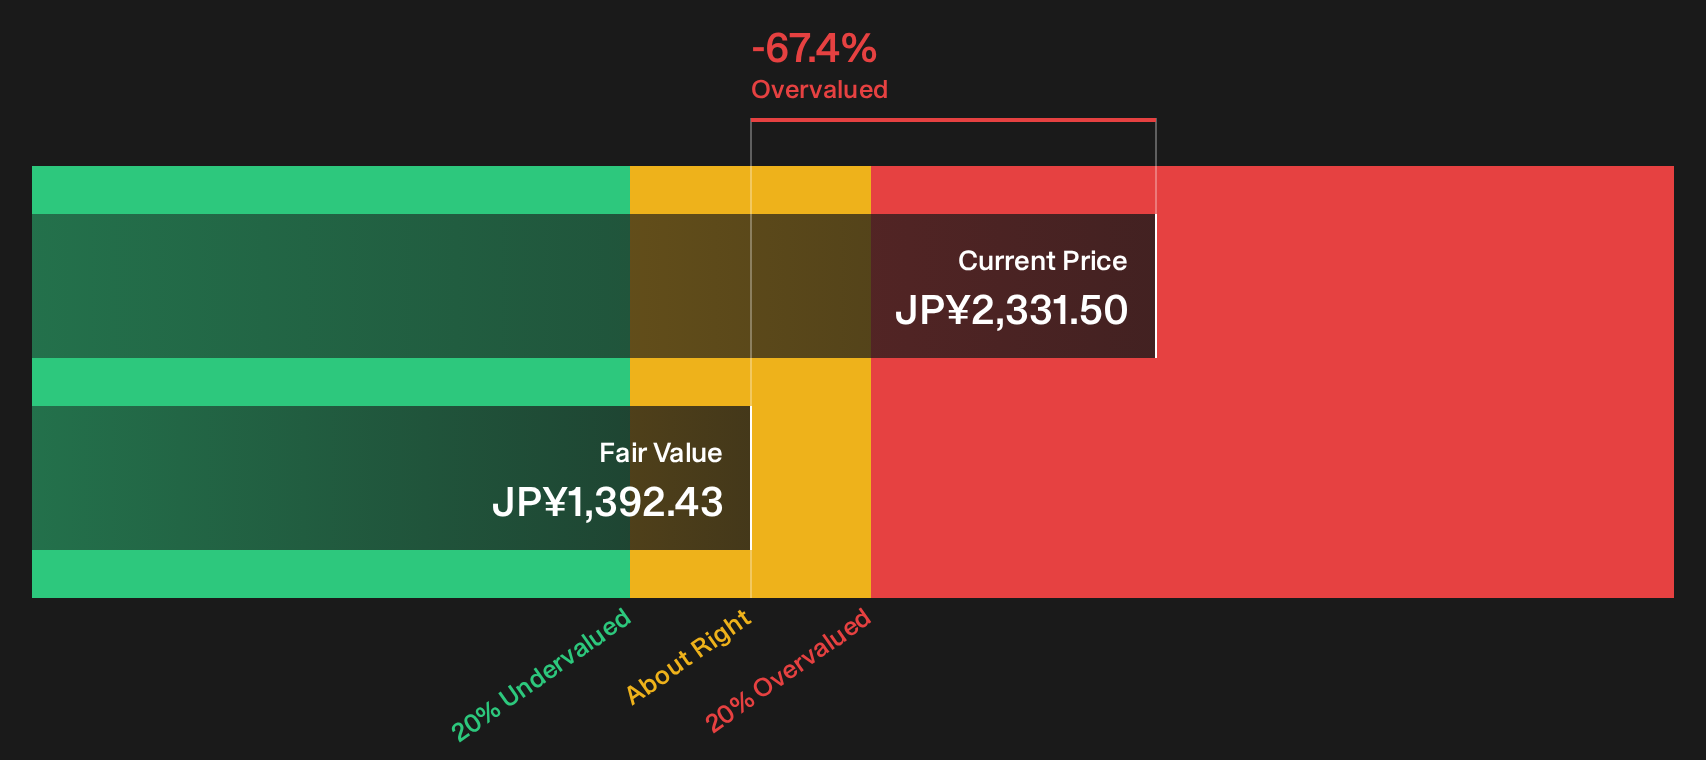
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Daido Steel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Daido Steel so far. If you want to move quickly yet stay grounded in your own judgment, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Daido Steel?
If Daido Steel has you thinking more broadly about opportunities, do not stop at one stock. Use screeners to quickly spot other ideas that match your style.
- Target resilient compounding potential by scanning for companies with healthy fundamentals and attractive valuations through the 18 high quality undervalued stocks.
- Prioritise capital strength and staying power by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (20 results).
- Hunt for underfollowed potential by focusing on lesser-known outfits with strong metrics via the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com