


Walmart (WMT) Could Be 30% Undervalued On Marketplace Expansion Narrative
Walmart (WMT) is back in focus after ADT Blu, a do it yourself home security system, launched on Walmart.com, highlighting how the retailer keeps widening its marketplace mix.
Despite upbeat headlines around marketplace partners like ADT Blu and RocketSports-1, Walmart’s share price has eased, with a 30-day return down 6.23% and a 90-day move down 8.50%. At the same time, the 1-year total shareholder return of 5.39% and 3-year total shareholder return of about 2x indicate that longer term momentum has been stronger than the recent pullback.
Spot 16 high quality undiscovered gems that, similar to Walmart’s marketplace partners, are quietly using scale and distribution reach to push under-the-radar growth stories into the mainstream.Bulls point to Walmart’s marketplace, e-commerce and advertising mix, while bears focus on the recent share pullback and premium multiple. Which side does the current valuation actually support?
Most Popular Narrative: 30% Undervalued
Walmart’s most followed valuation story pegs fair value at $154.58 a share, well above the last close of $108.09. This puts the current pullback in a very different light.
Walmart’s “Other” SBU is described as being positioned for continued success, leveraging innovation and agility to capture new market share. While risks exist, the segment’s performance and strategic initiatives are noted as supporting a positive outlook. Investors and stakeholders are encouraged to monitor developments in digital integration and specialty category expansion as potential drivers of future growth.
See why 54 investors see Walmart as 30% undervalued.
Result: Fair Value of $154.58 (UNDERVALUED)
Still, the Walmart story can break if execution stumbles in the high-growth “Other” segment or if the premium P/E multiple decreases because of shifting investor sentiment.
Find out about the key risks to this Walmart narrative.
Another View On Walmart’s Valuation
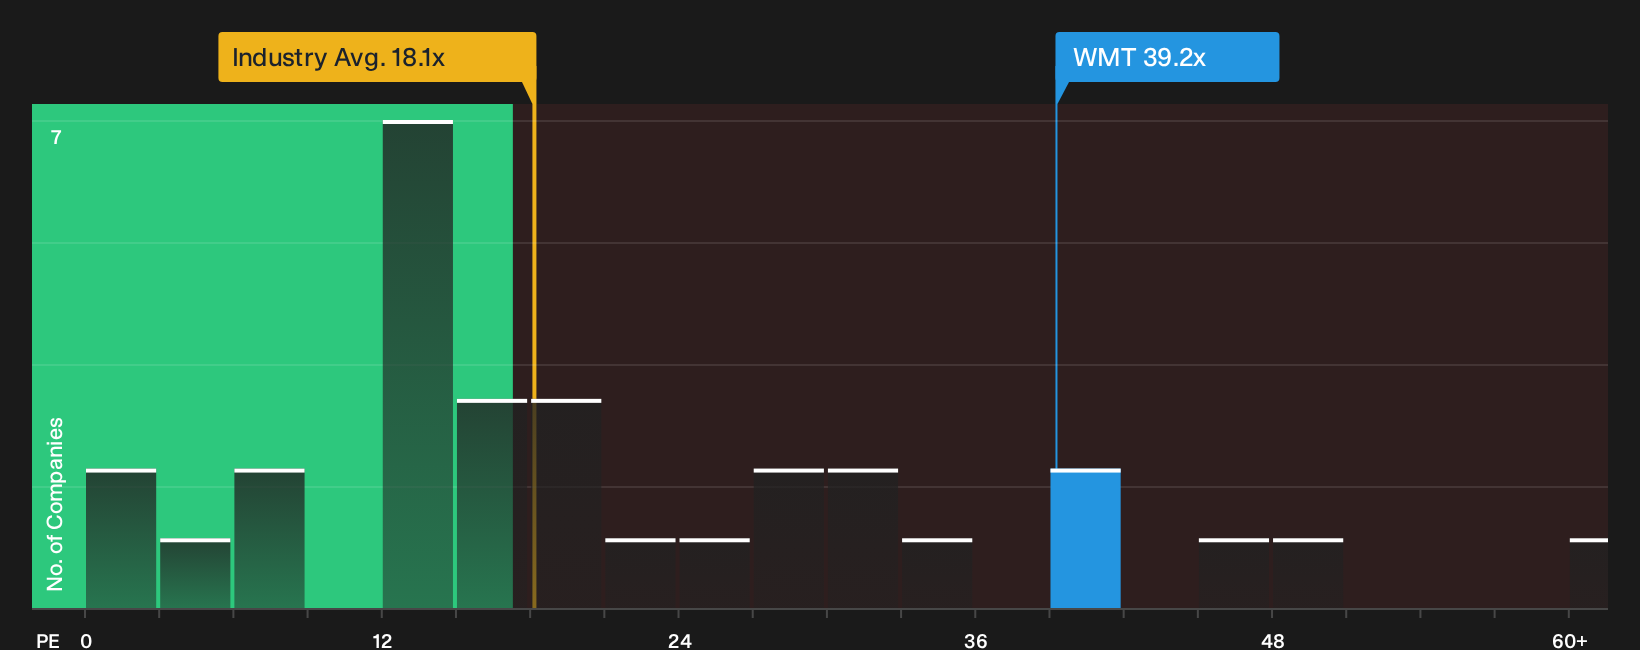
The user narrative frames Walmart as about 30% undervalued at $154.58 a share, yet the current P/E of 38.8x tells a different story. That multiple is far above the US Consumer Retailing average of 18.1x, the peer group at 22.6x, and even the 37.1x fair ratio.
This gap means investors are already paying a premium price for each dollar of Walmart earnings, which raises the bar for future execution and leaves less room for disappointment. If sentiment shifts or growth expectations cool, how comfortable are you owning a stock that already trades above its own fair ratio and sector benchmarks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Walmart is mixed right now, so consider promptly stress testing the narrative against your own expectations and risk tolerance, then weigh those perceived strengths against the 2 key rewards.
Looking for more investment ideas beyond Walmart?
If Walmart’s story has you thinking harder about price, quality and risk, do not stop here. Broaden your watchlist so you are not relying on a single narrative.
- Target potential mispricings by scanning a focused group of 34 high quality undervalued stocks that may offer more compelling entry points than widely followed giants.
- Stack potential income streams by reviewing a curated set of 6 dividend fortresses that put reliable cash returns at the center of their appeal.
- Dial down portfolio stress by concentrating on 11 resilient stocks with low risk scores designed to keep volatility and financial red flags in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com