


Wolfspeed (WOLF) Stock May Look Fully Valued On Its Sales Base
Wolfspeed has logged a mixed share-price story this year, with a strong run earlier in 2026 followed by a sharp pullback. This puts fresh focus on whether the current valuation still lines up with its sales base. With the stock now changing hands around US$24.02, the question for investors is how much revenue is really being priced into Wolfspeed today.
- The share price is still up 26.9% year to date. This means a lot of this year's gains rest on the strength and durability of Wolfspeed's sales profile.
- The business is heavily tied to semiconductor materials and related products, so expectations for future demand and the timing of revenue growth can have a direct impact on how investors frame its sales multiple.
- There is a second opinion on Wolfspeed worth weighing. See what analysts think Wolfspeed's shares could be worth.
The stock's next move may depend on whether the current share price can be squared with Wolfspeed's recent and expected sales performance.
If you want to test this same sales driven valuation question beyond Wolfspeed, compare it with other chip related names screened through 60 AI infrastructure stocks.
Is Wolfspeed Getting Expensive on Sales?
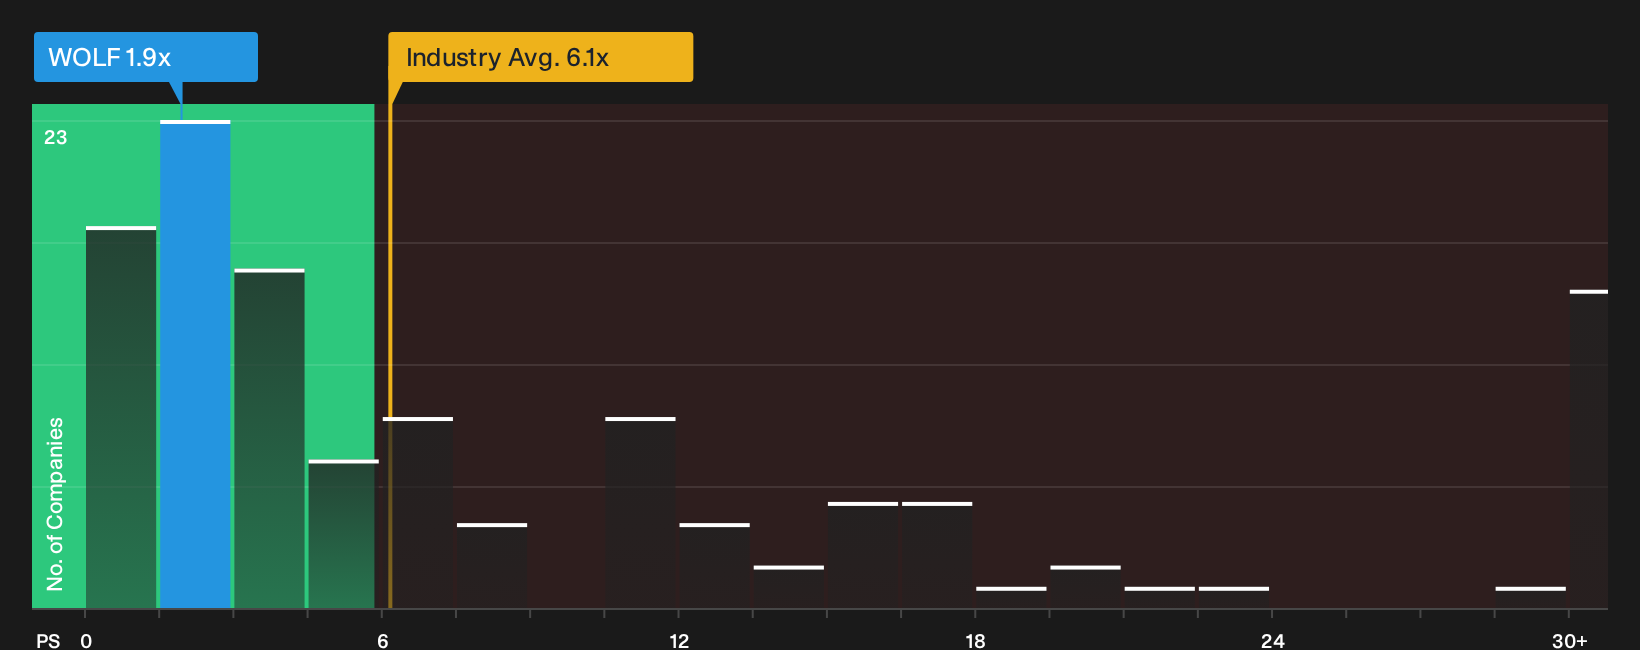
P/S fits Wolfspeed because investors are focused on what each dollar of revenue is worth while free cash flow and earnings remain pressured. On that yardstick, the stock trades on a P/S of 1.9x, which is well below the semiconductor industry average of 6.1x and also below a broader peer group closer to 9.0x.
The model that blends Wolfspeed specific factors like scale, margins and risk points to a higher P/S than where the shares change hands today. As a result, the current multiple screens as overvalued relative to that tailored yardstick, despite looking cheap against raw sector numbers. For anyone tracking Wolfspeed, the key question is whether the revenue base and business quality justify paying above what this fair ratio suggests, or whether the apparent discount to peers simply reflects those underlying pressures already. Explore the numbers behind Wolfspeed's P/S valuation.
The Wolfspeed Narrative: What Would Justify Today's Price?
Wolfspeed Narratives on Simply Wall St pick up where the P/S puzzle leaves off and explain which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one treats fair value as a hypothesis about Wolfspeed's business that can be revisited over time, so you can see how the story holds up as new information arrives, on the Community page.
One of the top community narratives on Wolfspeed: 13% undervalued
"Expansion of AI and high performance computing data centers is increasing demand for higher efficiency 800 volt and high voltage power architectures…"
Discover why this Narrative puts Wolfspeed at 13% undervalued.
Before focusing only on Wolfspeed's valuation, check what the risk checks are saying
Price tags only tell part of the Wolfspeed story. Separate research flags specific concerns that could change how you weigh the whole case once you see them. Take a closer look at 4 warning signs (3 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com