


3 Small Cap Stocks With Strong Revenue Growth And Low Debt
The 10-year US Treasury yield just touched 5%, a level last seen before the 2008 crisis. That shift in borrowing costs puts highly leveraged companies under real pressure. Investors who want growth but worry about heavy debt may find this screener timely. This article breaks down three small caps with strong revenue and low leverage that could fit that kind of portfolio focus.
The three stocks covered below are just a sample set. The full screen surfaced 154 more small caps with similar financial profiles and equally compelling stories that are not included in this article.
If you want to rapidly identify and analyze those high-conviction ideas built around strong revenue and low debt, head straight into the Small Caps With Strong Revenue and Low Debt screener.
Optimi Health (OPTH)
Overview: Optimi Health manufactures and sells MDMA, psilocybin and mushroom-based drug products. This links revenue growth directly to regulated psychedelic demand.
Operations: The business currently reports about CA$0.18 million from farming, processing and distributing agrifood-related mushroom products.
Market Cap: CA$35 million
Optimi Health is included in this high growth, low debt screen because of its forecast 78.4% annual revenue expansion and its in-house psychedelic drug production, which can scale without relying on large amounts of borrowing. The opportunity is characterized by very early stage sales, ongoing losses and equity funding, so changes in how that financing burden aligns with clinical progress could be important for investors.
The most-followed narrative on the Simply Wall St community about Optimi Health argues that the company may be being overlooked despite already selling pharmaceutical-grade MDMA and psilocybin into Australia’s regulated market. It highlights Optimi’s manufacturing capacity and the potential for high margins as patient numbers grow. It also highlights its valuation discount to peers. The Community Author’s belief is that this disconnect could close as Optimi scales and accesses larger markets.
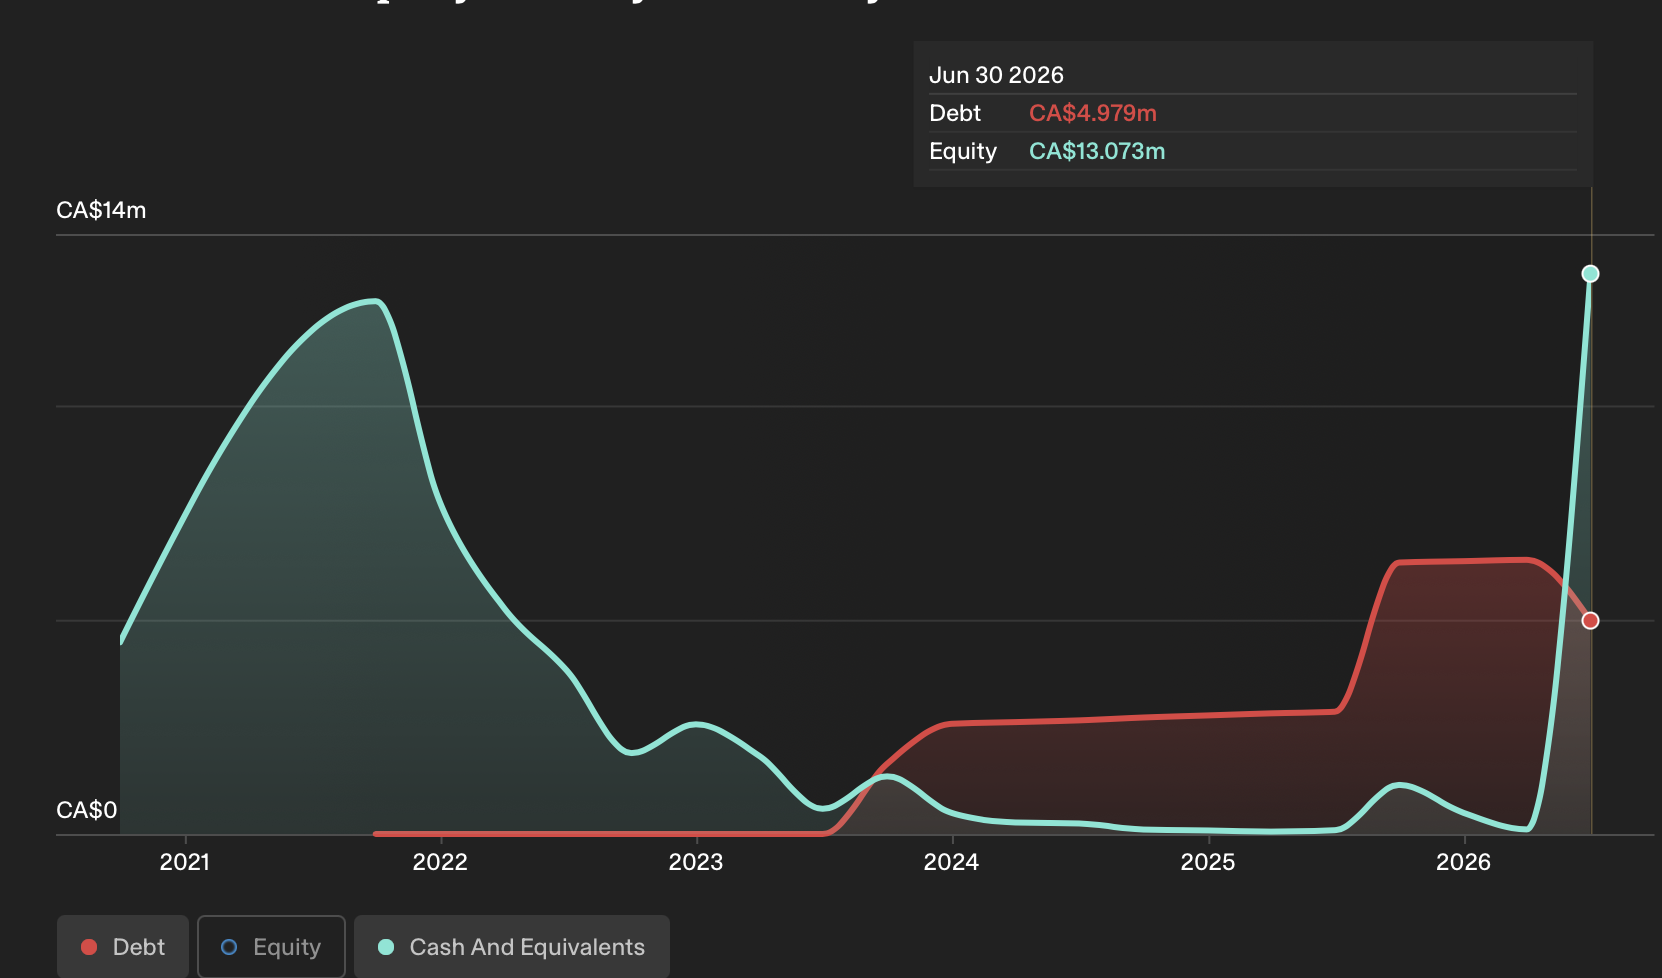
Bright Minds Biosciences (CNSX:DRUG)
Overview: Bright Minds Biosciences is a New York based biotech developing 5 HT2 serotonin agonist drugs for epilepsy and neuropsychiatric disorders, with late stage BMB 101 driving its low debt and high growth screener fit.
Market Cap: CA$872 million
Bright Minds Biosciences gives you exposure to late stage epilepsy and neuropsychiatric drug candidates tied to a 69.19% revenue growth forecast. At the same time, it keeps balance sheet risk lower than many small cap peers that rely heavily on borrowing. The trade off is substantial dilution and ongoing losses, which makes everything hinge on how one clinical and valuation pressure ultimately resolves.
When so much rides on that single clinical and valuation break point, the 3 key rewards and 4 important warning signs (3 are major!) shows what might be masking or amplifying the upside.
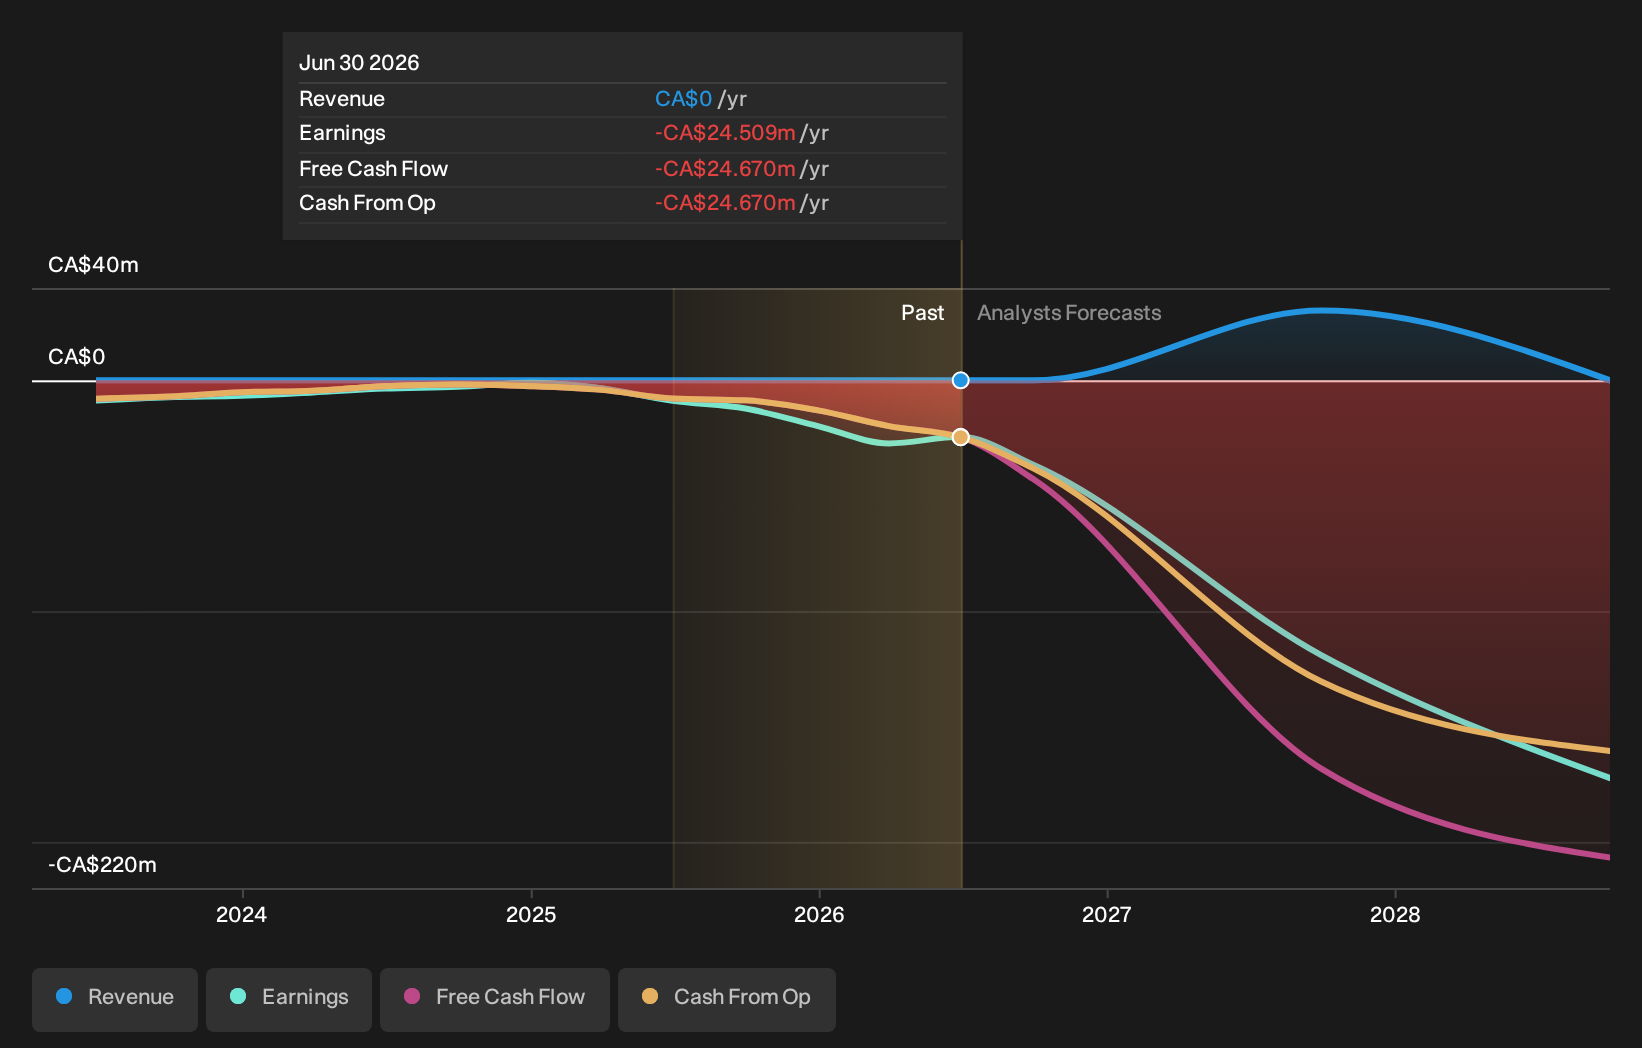
Lineage Cell Therapeutics (LCTX)
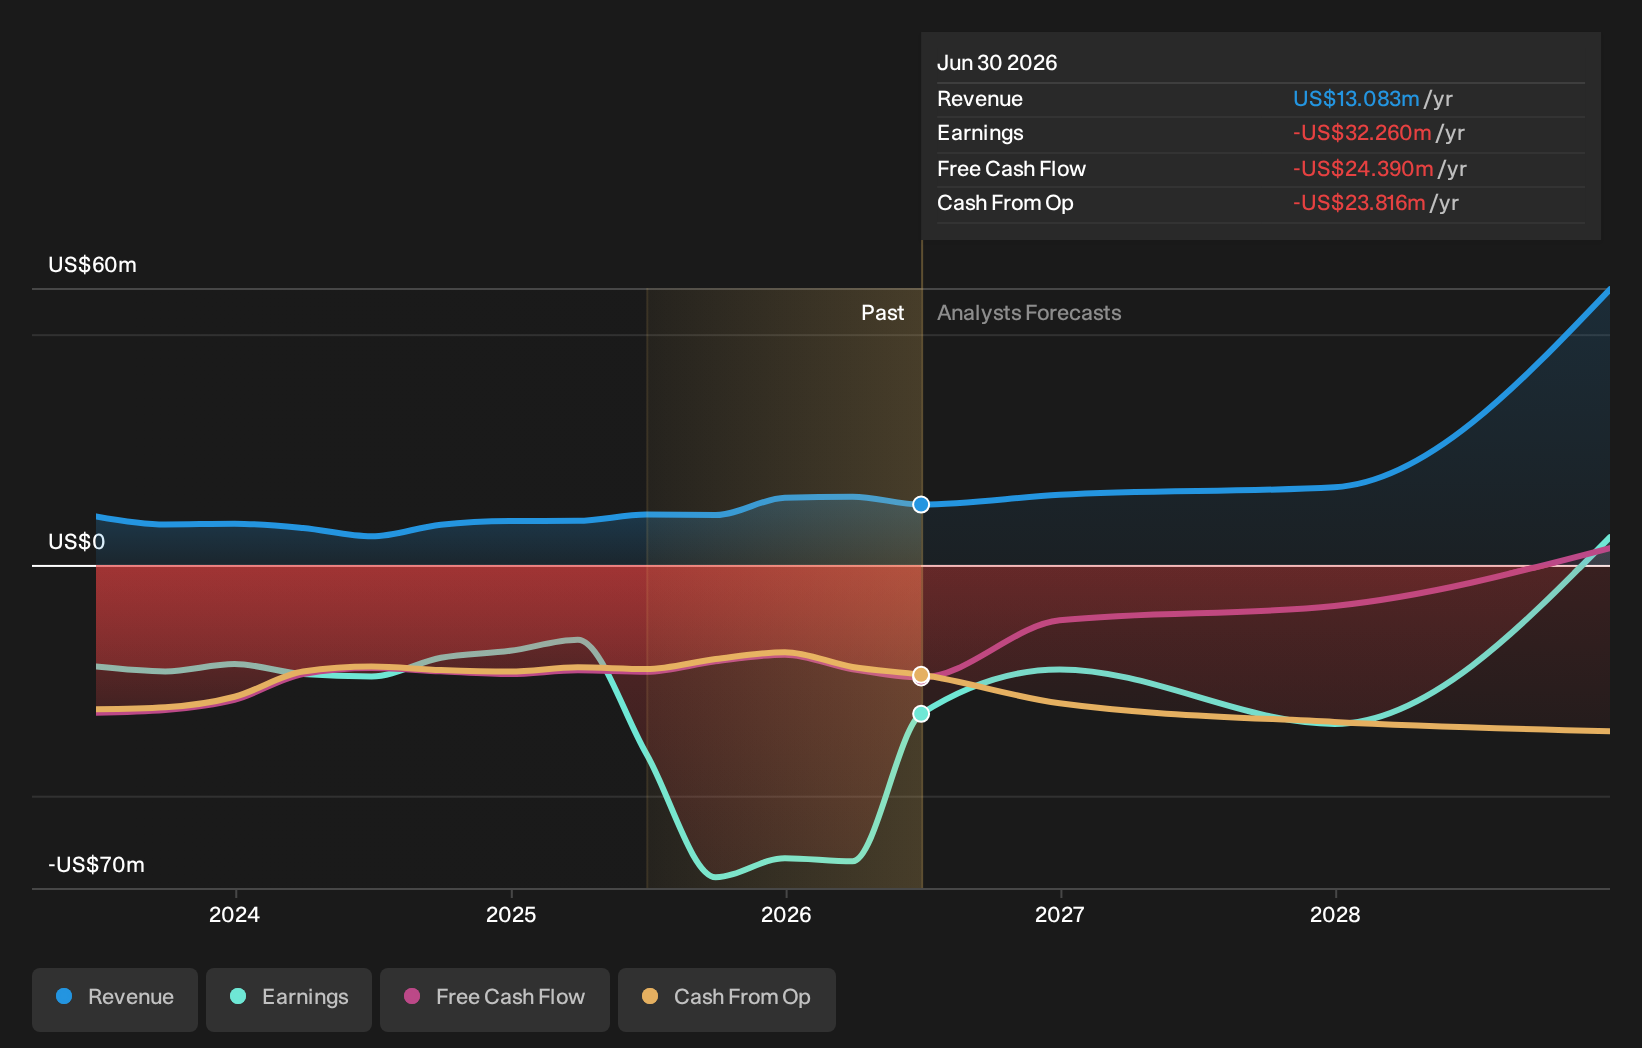
Overview: Lineage Cell Therapeutics develops off the shelf cell replacement therapies such as OpRegen and OPC1 for age related blindness and spinal cord injuries. This gives the screener exposure to a late stage, low debt regenerative medicine pipeline rather than mature product revenue.
Operations: Lineage generated about US$13 million from research and development of therapeutic products, reflecting its focus on advancing cell therapy programs.
Market Cap: US$255 million
Lineage Cell Therapeutics fits this small cap, low leverage list through its regenerative medicine portfolio, where OpRegen and OPC1 contribute to the revenue story while keeping the balance sheet relatively clean of heavy borrowing.
"The ongoing global increase in age-related and degenerative diseases, particularly dry AMD, combined with emerging long-term benefits from OpRegen's clinical trials (3-year sustained vision gains), positions Lineage to tap into a rapidly expanding patient population, likely driving substantial future top-line revenue growth as population aging continues."
What happens to future margins and funding needs depends heavily on how one underappreciated pressure around external financing plays out.
That pressure point is the real hinge for Lineage Cell Therapeutics, and the full narrative for Lineage Cell Therapeutics explains how external funding, partnerships, and trial outcomes could be decoupling near term risk from long term opportunity.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the best breakout ideas rarely stay under the radar for long. Scan these fresh stock lists before momentum is fully established and consider acting while conditions are still developing.
- Identify resilient compounders before they become widely followed by running the 1 resilient stocks with low risk scores while prices and risk profiles remain potentially appealing for disciplined investors.
- Focus on earnings momentum instead of hype by scanning the 75 profitable AI stocks that aren't just burning cash while these cash-generating AI companies may still be attracting less attention.
- Review the 38 power grid technology and infrastructure stocks to evaluate opportunities related to power infrastructure before demand and pricing dynamics potentially evolve further.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Simply Wall St analyst Andrew Legget and Simply Wall St have no position in any of the companies mentioned. This article is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.