


Honeywell International (HON) Launches Marine Corps Security Upgrade As Undervalued Narrative Faces A Test
Honeywell International (HON) is back in focus after Honeywell Technologies rolled out a modernized LenelS2 OnGuard access control platform for the U.S. Marine Corps, supporting the Barracks 2030 security modernization effort.
The news comes at a tougher time for Honeywell International, with the 30 day share price return down 13.05% and the 90 day move down 55.51%. By contrast, the 3 year total shareholder return of 12.20% and the 5 year figure of 6.23% indicate a more modest long haul outcome. Recent announcements around defense focused access control and an upcoming appearance at Morgan Stanley’s Laguna Conference are potential catalysts that may be shaping how investors weigh Honeywell’s growth optionality against perceived execution and earnings risk at the current US$203.44 share price.
Scan how Honeywell International’s security push compares with handpicked peers by reviewing 38 robotics and automation stocks that are shaping the next wave of automated defense and infrastructure control.
After a 55.5% slide over 90 days and a share price near US$203, Honeywell International now forces a simple check: Is meaningful upside still ahead, or has most of the rerating already happened?
Most Popular Narrative: 36% Undervalued
The most followed narrative on Honeywell International pitches a fair value of $320.19 per share against the recent $203.44 close. This frames the recent slide as a potential gap between price and story rather than a simple loss of confidence.
Process Automation & Technology, which houses UOP, Honeywell’s energy technology licensing division, reported a 6% organic revenue decline in Q1 2026. The market read that as weakness. It was timing.
See why 65 investors see Honeywell International as 36% undervalued.
Result: Fair Value of $320.19 (UNDERVALUED)
Still, the narrative around Honeywell International could unravel if organic growth remains closer to low single digits, or if the planned multiple re rating fails to show up.
Find out about the key risks to this Honeywell International narrative.
Another View: Honeywell International Through The DCF Lens
The narrative fair value for Honeywell International sits at $320.19, yet our DCF model points in the opposite direction. On those cash flow assumptions, HON at $203.44 is trading above an estimated value of $136.46, which frames the stock as overvalued using this method.
That gap between a 36% narrative discount and a DCF premium raises a simple question for investors: Which set of assumptions feels closer to how Honeywell International will actually convert its backlog and margins into future cash generation, and how much patience are you willing to have while that plays out?
Look into how the SWS DCF model arrives at its fair value.
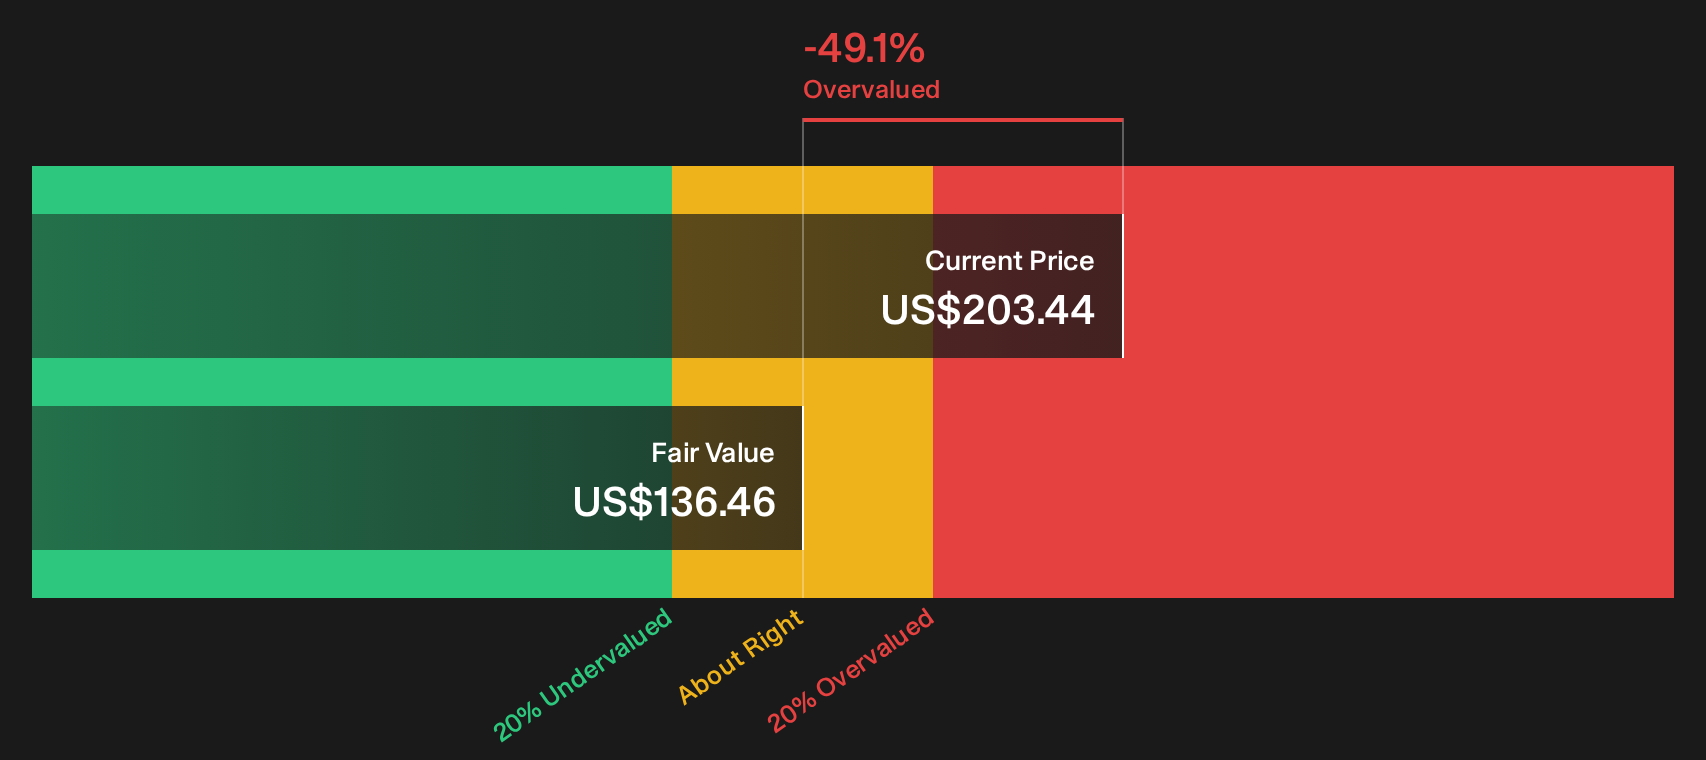
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and concern around Honeywell International feels unsettled, move quickly to review the underlying data points yourself, then weigh the 4 key rewards and 5 important warning signs.
Looking for more Honeywell International sized ideas?
Do not stop your research with Honeywell International. The next move often comes from a company you have not studied yet, so give yourself options.
- Spot potential mispricings early by reviewing our 34 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them.
- Strengthen your downside protection by scanning a 11 resilient stocks with low risk scores that screens for resilient operations and steadier risk profiles.
- Get ahead of the crowd by checking a 16 high quality undiscovered gems that highlights under followed businesses with solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com