


Rare Earth Study Could Be A Big Deal For Mosaic Stock (MOS)
- Rainbow Rare Earths announced that a Pre-Feasibility Study has started for the Uberaba rare earths project in Brazil with Mosaic. The study targets on-site processing of approximately 2.7 Mtpa of phosphogypsum waste over an initial 30-year life, using a flowsheet derived from Mosaic’s Phalaborwa work.
- This collaboration positions Mosaic to test whether rare earth extraction from phosphogypsum can turn a legacy waste stream into a separate high-purity NdPr and SEG+ product line. This development could influence how its Brazilian phosphate operations are valued and managed.
- Attention now turns to how Mosaic's existing fertilizer-focused investment narrative could be influenced by the Uberaba rare earths Pre-Feasibility Study.
Mosaic Investment Narrative Recap
For Mosaic, the big picture is still about a fertilizer producer working to make its concentrated phosphate and potash operations more reliable and less volatile. Investors need to believe that cost work in Brazil and the U.S., together with a broader distribution network, can help offset cyclical pricing. At the same time, an unprofitable starting point and interest coverage pressure remain front of mind.
The Uberaba rare earths study adds an option for turning phosphogypsum into a higher value stream, but it does not change the primary near term catalyst, which is stabilising earnings from core nutrients. It also does not remove key risks related to dividend coverage, Brazilian credit conditions, and potential environmental and remediation spending.
The Uberaba Pre-Feasibility Study announcement is the most relevant development here because it directly links Mosaic’s existing phosphate operations in Brazil to a new processing concept for waste phosphogypsum. The plan is to process about 2.7 Mtpa of residue over an initial 30 year life and produce separated NdPr oxide and SEG+ rare earth products at high purity levels.
For catalysts, this project is still at an early stage and sits alongside efforts such as automation, reliability initiatives, and growth in value added fertilizers and biosciences. The key watchpoints are PFS execution through the expected completion in the second half of 2027, test work on the 6 tonnes of shipped feedstock, capital intensity, and how any new rare earth revenue might interact with fertilizer price cycles and Mosaic’s current loss making status.
Mosaic's narrative projects US$12.7b revenue and US$421.4m earnings by 2029. Analysts assume revenue stays broadly flat over that period, while earnings would need to rise by about US$376m from US$45.0m today to reach the consensus forecast.
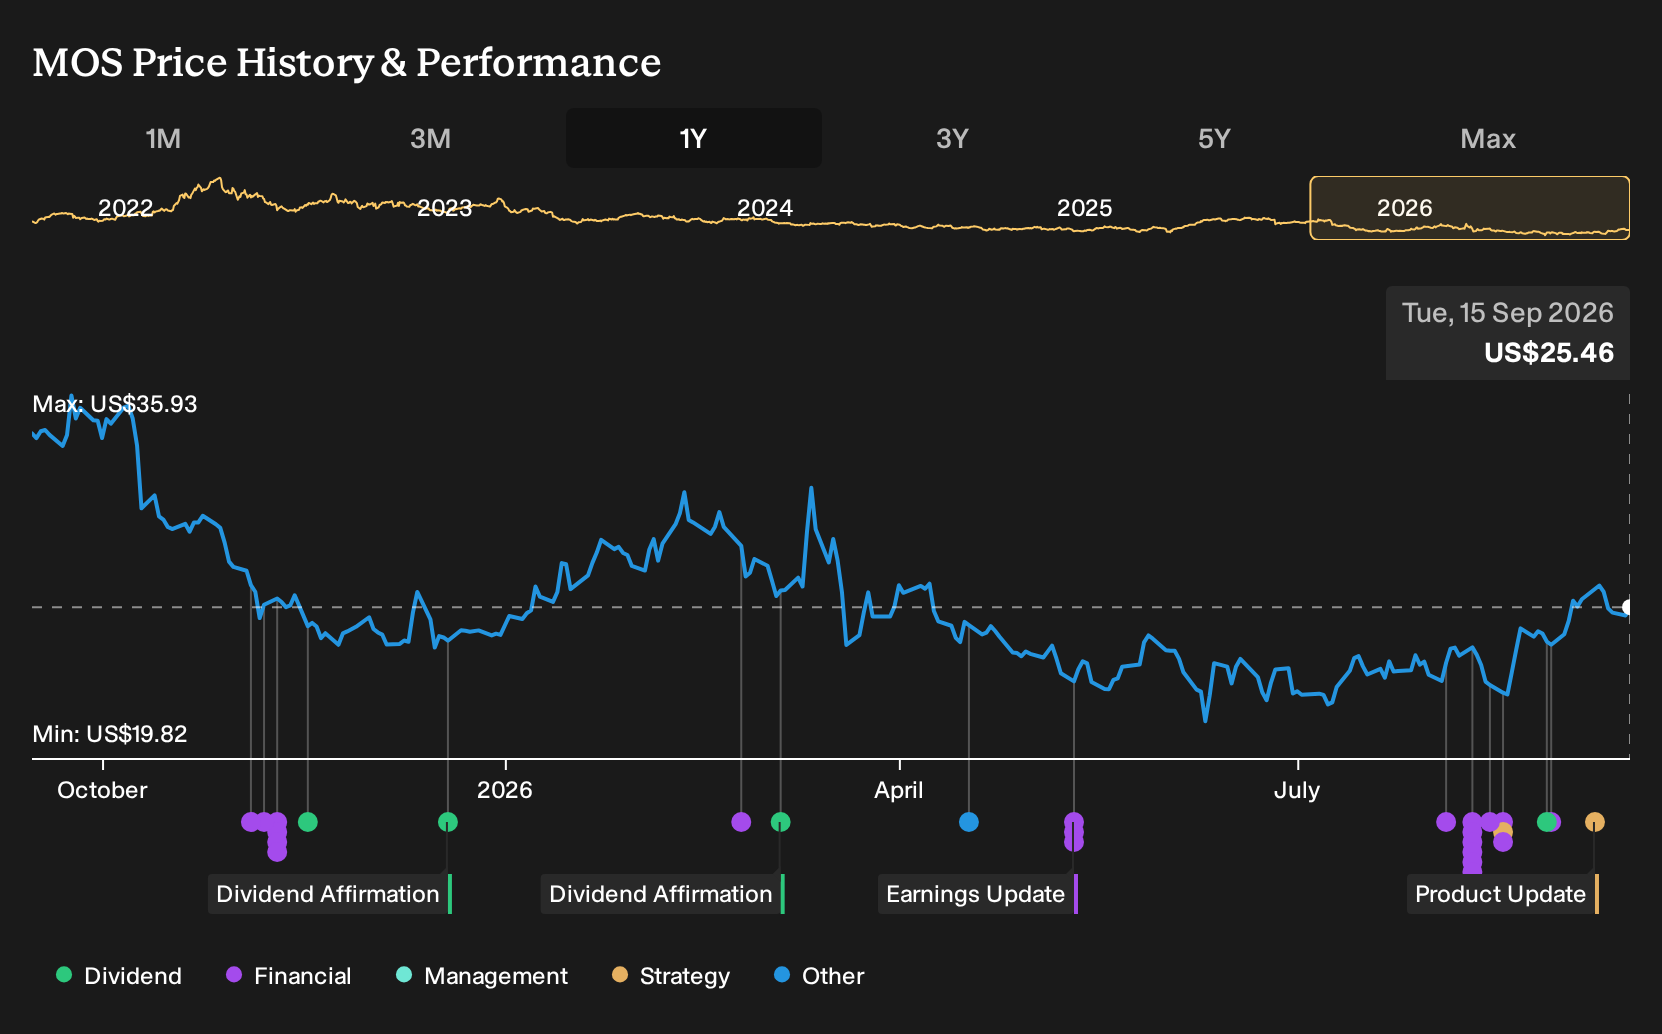
Uncover why Mosaic's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can look at the Uberaba news through a different lens. The most pessimistic Mosaic analysts already expected revenue to slip about 2.6% a year and earnings to climb from a loss of US$638.5m to US$391.4m by 2029. That cooler view might shift if rare earths start to matter more in forecasts.
Explore 5 other Mosaic fair value estimates, including one that suggests as much as 29% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Mosaic research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mosaic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mosaic's overall financial health at a glance.
Looking For More Ideas Beyond Mosaic?
If Mosaic's rare earths angle has sparked new questions about where to put fresh capital to work, it can help to line it up against a broader watchlist. Use the Simply Wall St Screener to compare businesses across quality, resilience and income potential, then decide which stories deserve a deeper look.
- Target resilience first by scanning a 11 resilient stocks with low risk scores that can help you focus on companies with steadier risk profiles when market sentiment swings.
- If value is your priority, check a 34 high quality undervalued stocks that surfaces businesses combining stronger cash generation with what looks like conservative pricing.
- For investors who want income on top of potential capital gains, filter for a 6 dividend fortresses that highlights higher yield opportunities with the numbers to back them up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com