


Why ASML Holding (NasdaqGS:ASML) Is Getting Fresh Attention Now
ASML Holding (NasdaqGS:ASML) drew fresh attention after a recent pullback, with the share price down about 14% over the past month and roughly 15% over the past 3 months.
Recent momentum for ASML Holding has cooled, with the 7-day share price return down 9.75% and the 30-day return down 13.63%, even though the year-to-date share price return is 36.86% and the 1-year total shareholder return is 82.33%.
Scan how ASML Holding stacks up against other chipmakers by reviewing hand-picked 60 AI infrastructure stocks riding the same semiconductor and AI buildout trend.
ASML Holding runs a crucial part of the chip industry, yet the recent pullback has reset expectations. After such a strong 1-year run, do current multiples still make sense for new money today?
Preferred P/E of 49.8x: Is it justified?
Valuation has shifted quickly for ASML Holding, with the stock now trading on a P/E of 49.8x after the pullback, compared with 44.5x for the wider US Semiconductor industry and peer levels of 43.4x.
The P/E ratio benchmarks what investors are willing to pay today for each dollar of ASML Holding's earnings. For a capital intensive chip equipment supplier with high net profit margins of 30.1% and a long track record of profitability, that earnings multiple becomes a shorthand for how much faith the market is putting in future profit growth and returns on capital.
ASML's earnings are described as high quality, with net income growing 21.5% annually over the past year and 14.4% per year across the last 5 years, while return on equity sits at 48.7% and is forecast to reach 59.8%. Against that backdrop, the SWS fair P/E estimate of 40.3x implies the current 49.8x valuation is rich and would require strong execution for the share price to remain at these levels over time.
The current multiple also runs hotter than the rest of the sector, with ASML Holding trading above both the US Semiconductor average P/E of 44.5x and the 43.4x peer group reference level. This suggests the market is willing to pay a clear premium relative to comparable chip stocks and above the 40.3x fair ratio that the market could eventually gravitate toward.
Explore the SWS fair ratio for ASML Holding.
Result: Price-to-earnings of 49.8x (OVERVALUED)
Still, ASML Holding faces risks if high China exposure draws tighter export controls or if chipmakers slow equipment orders and strain today’s premium P/E story.
Find out about the key risks to this ASML Holding narrative.
Another view on ASML Holding's value
On a different yardstick, the SWS DCF model suggests ASML Holding at $1,592.73 is trading well above an estimated future cash flow value of $952.43. That points to an overvalued reading on this framework and raises a simple question for you: Which signal carries more weight, earnings multiples or long term cash flows?
Look into how the SWS DCF model arrives at its fair value.
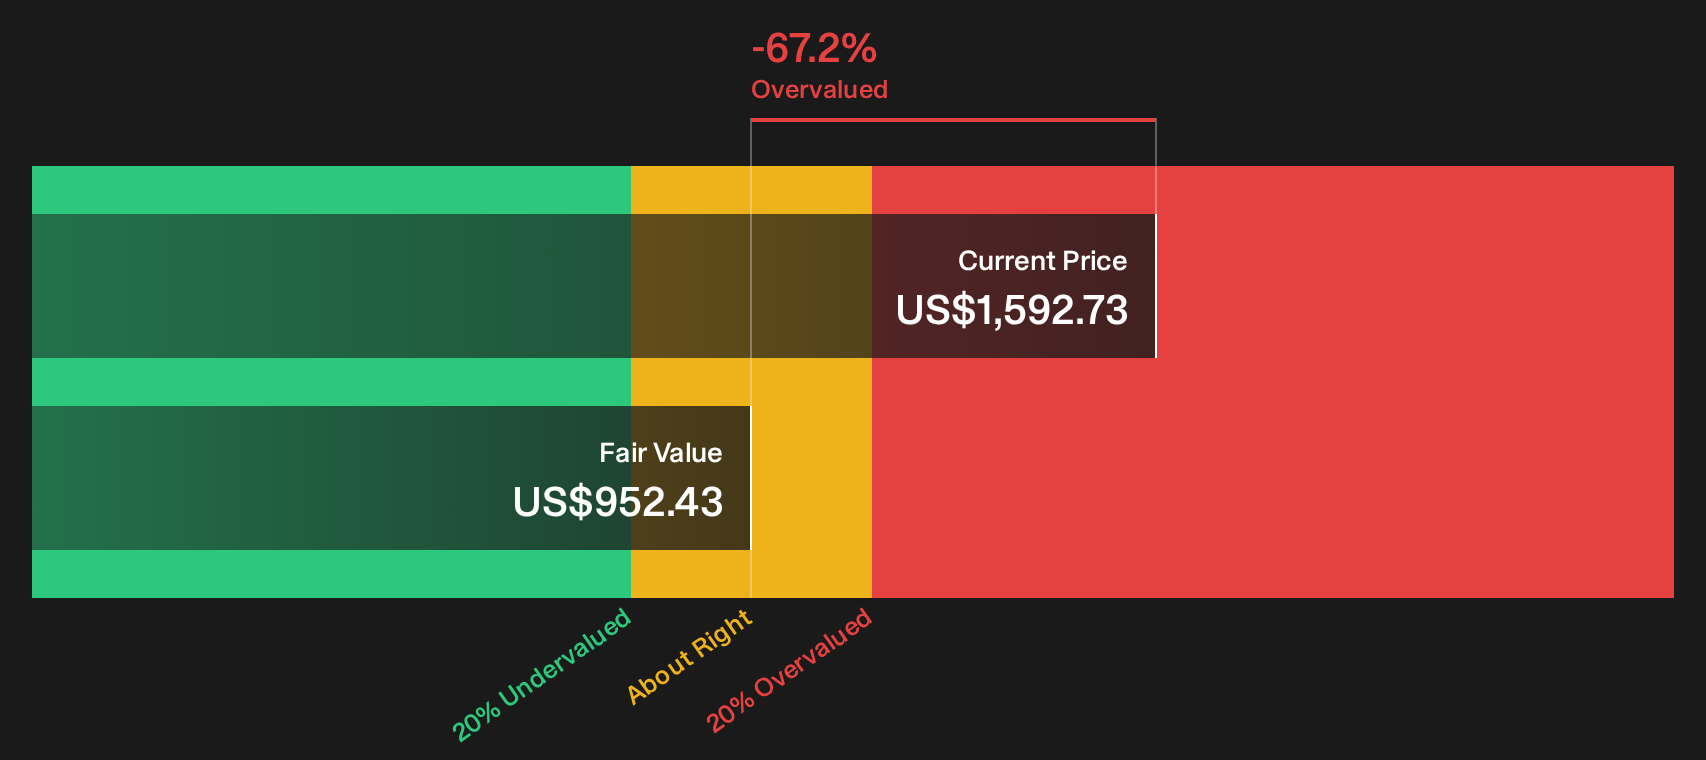
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASML Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this ASML Holding story points to stretched expectations, so it makes sense to pressure test the numbers yourself and move early if your view differs. To see what the optimism in the data looks like in one place, review the 2 key rewards
Looking for more ASML Holding style investment ideas?
You have seen how high expectations can shape ASML Holding. Now widen your watchlist and pressure test fresh opportunities before the market prices them in.
- Target strong cash flows and quality balance sheets by scanning a 34 high quality undervalued stocks that pairs fundamentals with attractive pricing signals.
- Protect your capital base first, then seek upside by reviewing 11 resilient stocks with low risk scores that score well on resilience and financial strength.
- Spot future leaders early by checking a curated 16 high quality undiscovered gems that screens for quality metrics before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com